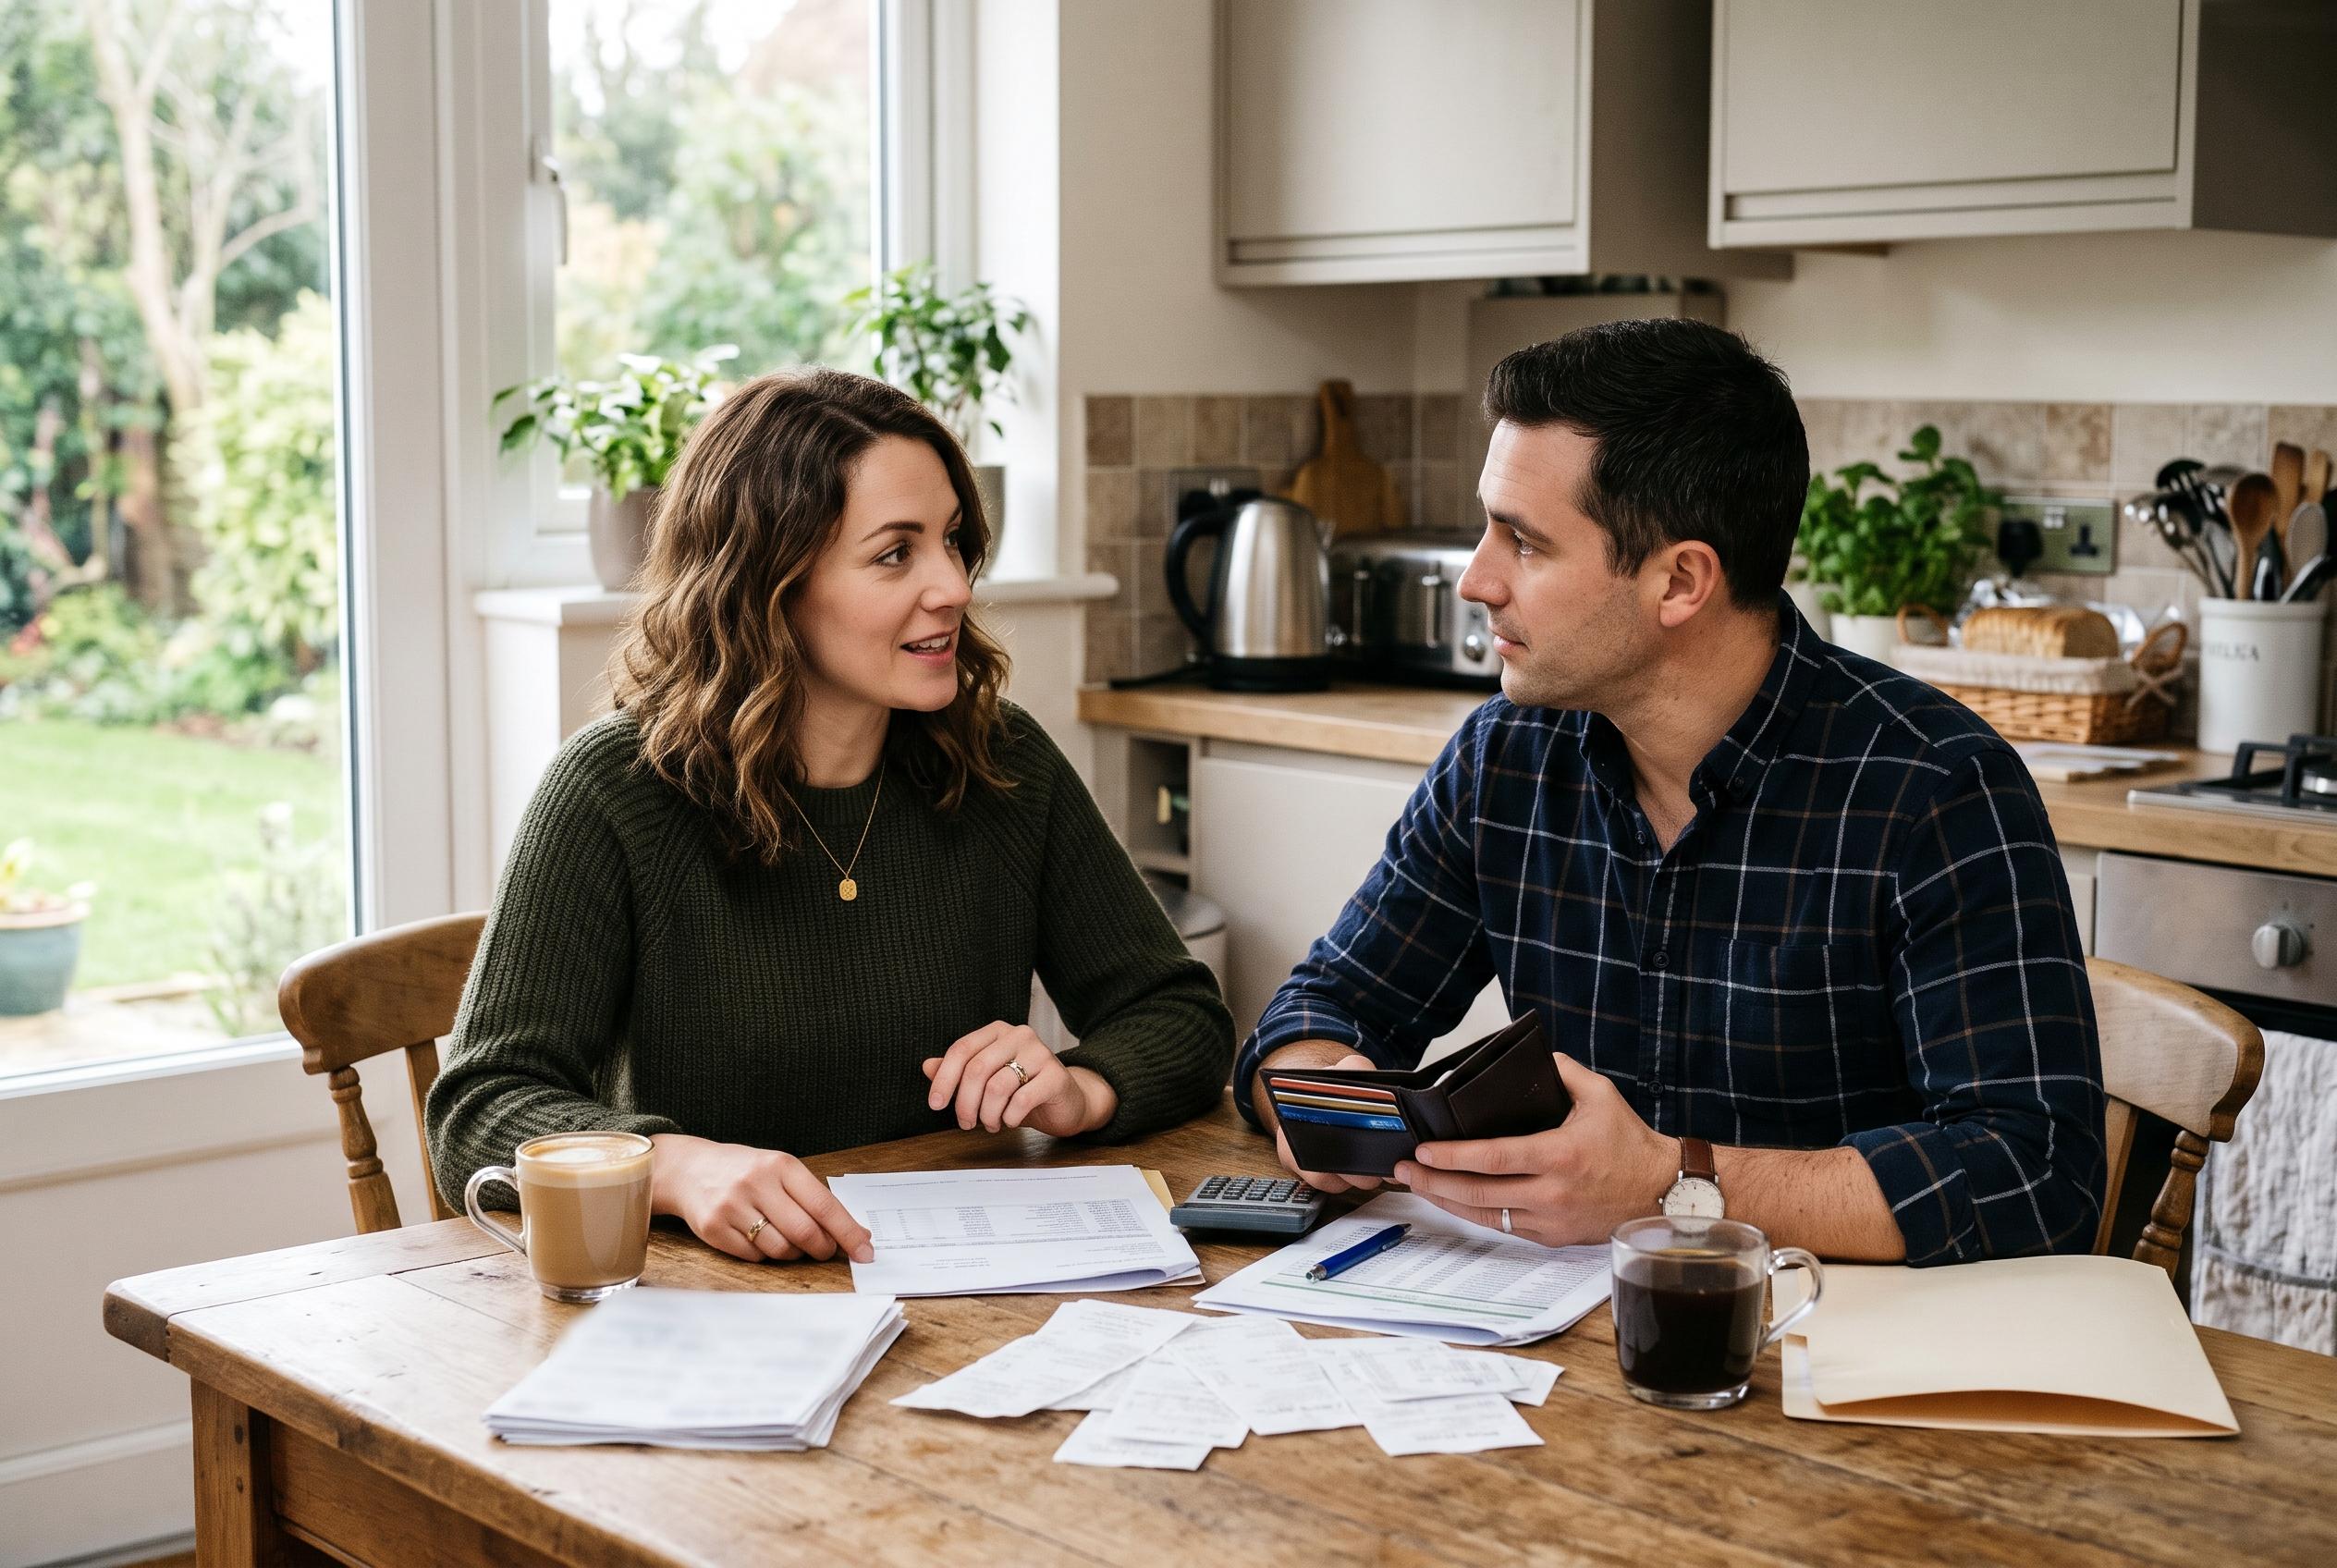

Experts say couples should discuss spending, debt and savings early, with shared costs divided in a way that reflects both income and unpaid household responsibilities.
Money is often where couples discover their biggest differences. According to El Comercio, Celeste Sánchez, a journalist focused on family finance and consumer issues, says many partners wait until a problem forces them to confront spending, debt and savings, rather than discussing those matters early. Her point is that open conversation can prevent small frictions from turning into repeated rows, especially when each person comes into a relationship with different habits, family expectations and ideas about privacy around money.
A common mistake, she argues, is assuming that an equal split is always fair. If one partner earns substantially more than the other, dividing every bill down the middle can leave the lower earner under greater strain. Industry guides on couple finances make a similar point, saying that a proportional split often works better when incomes are uneven because each person contributes in line with their capacity. In practice, many households use a mixed approach, with some costs divided evenly and others handled according to income.
The wider financial picture matters too. Kiplinger notes that secrecy around spending, repeated borrowing, poor credit-card habits and a refusal to plan for the future are among the clearest warning signs that money could damage a relationship. Those problems do not always mean a couple is doomed, but they do suggest that trust and transparency are at risk. For that reason, advisers commonly recommend regular check-ins about budgets, debt, savings and long-term goals, rather than leaving one partner to manage everything alone.
Sánchez also stresses that money is only one part of how a household functions. Domestic work, childcare and other responsibilities also have value, and couples need a way to recognise that contribution when they decide who pays for what. The practical aim is not to impose a single formula, but to agree on shared bills, personal spending allowances and any changes needed as incomes or obligations shift. As several personal-finance guides point out, the best system is usually the one both partners understand, accept and can sustain without resentment.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.