

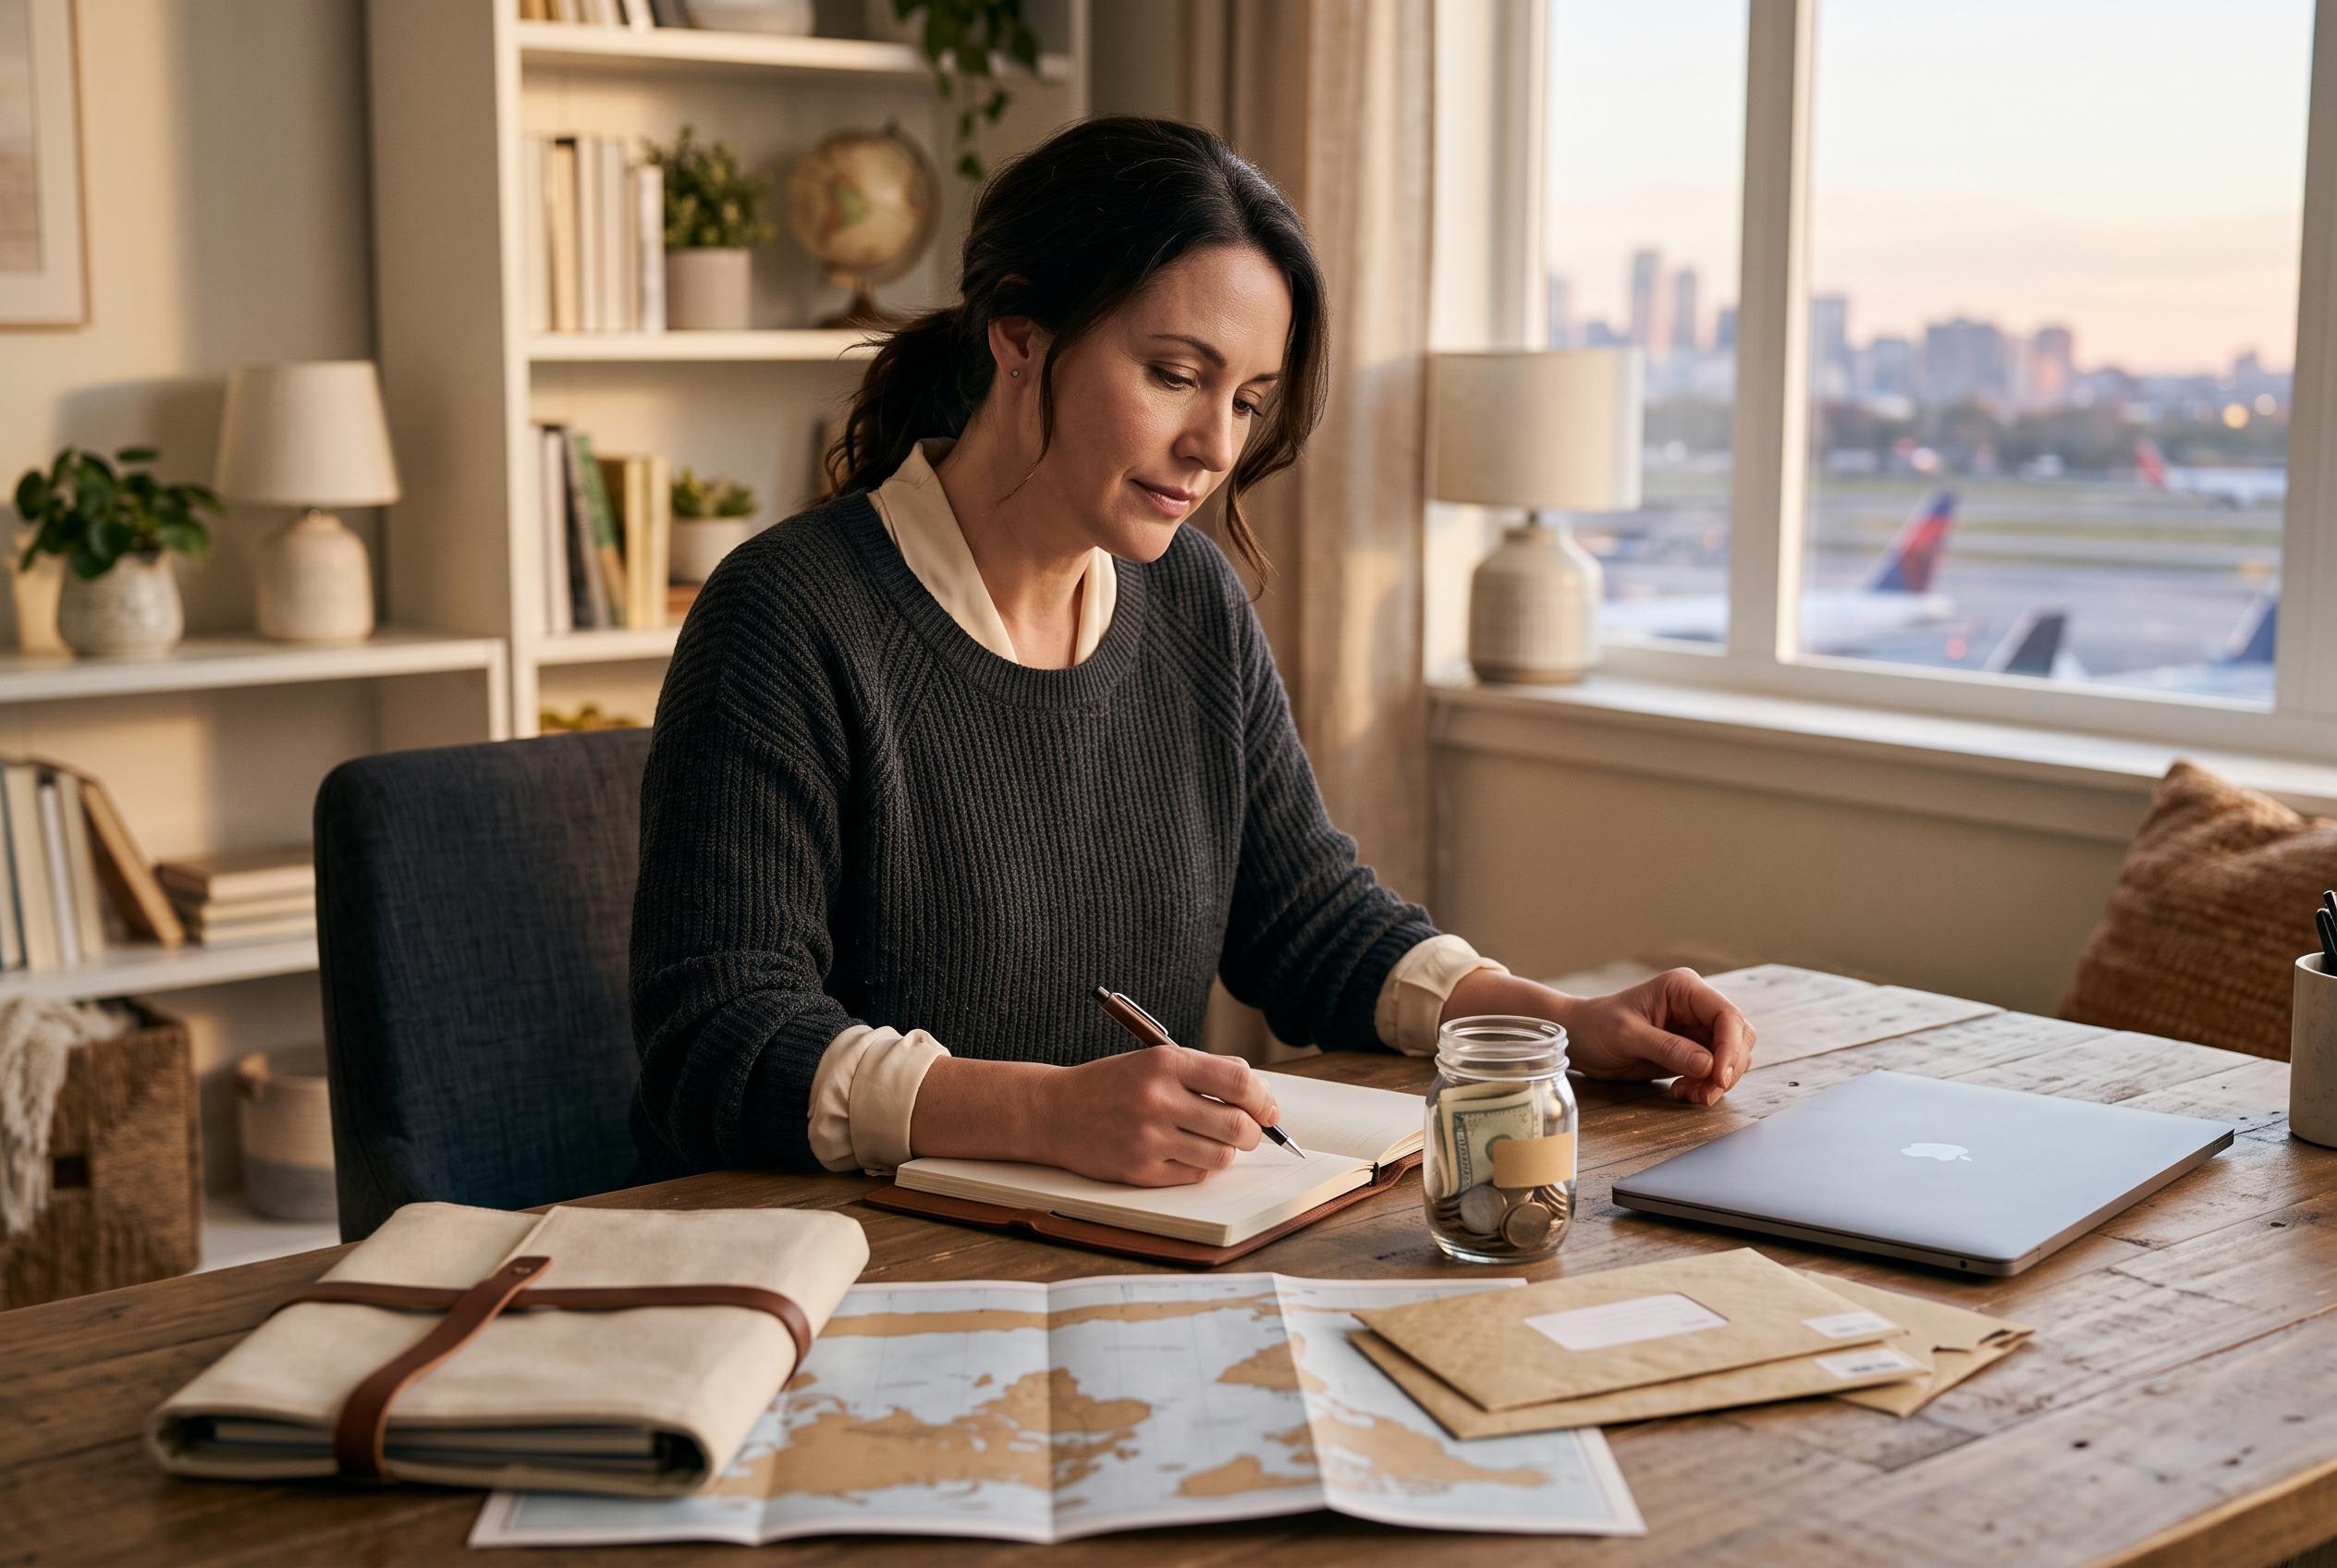

Building travel funds through small, consistent habits and strategic planning can turn distant dreams into achievable reality, according to experts and financial guidance.
Travel rarely becomes possible through one dramatic decision. More often, it is built from small, repeatable habits: setting a target, moving money automatically, trimming wasteful spending and using rewards programmes with care. That approach turns a vague dream of getting away into a practical financial plan, one that can sit alongside bills, savings and everyday life rather than compete with them. According to guidance from Kiplinger and NatWest, the most effective starting point is to define the trip, put a price on it and work backwards from the date you want to leave.
A clear target makes the goal far less intimidating. Fidelity recommends estimating the full cost of a trip, including flights, lodging, food, transport and activities, rather than focusing only on the headline fare. NatWest takes a similar view, encouraging savers to choose a destination and set a deadline so a monthly contribution can be calculated. That kind of planning can also reveal that a journey once assumed to be out of reach may be possible with a shorter stay, a different destination or a more flexible travel window.
Once the target is set, the mechanics matter. Capital One advises keeping travel savings in a separate account so the money is less likely to be spent accidentally, while Fidelity says it can help to make the fund slightly harder to access. Automatic transfers soon after payday can also remove the need for willpower, because the savings happen before the money is absorbed into routine spending. The discipline is less about saving a large amount all at once than about making regular transfers that do not stop.
Another useful step is to examine the money already leaving the account each month. Recurring subscriptions, unused memberships, inflated phone plans and avoidable banking fees can quietly drain the budget. Fidelity recommends reviewing subscriptions and utility costs, and that advice fits a wider pattern: modest cuts in routine spending can create room for travel without forcing a life of permanent austerity. In practice, that means distinguishing between genuine comforts and habits that no longer add value.
Rewards can help, but only if they are used with discipline. NerdWallet notes that travel credit cards often earn points or miles on both travel and everyday purchases, while BestMoney points out that ordinary household spending can generate meaningful value over time. Still, the benefit disappears quickly if the card balance is not cleared in full. High interest charges can overwhelm any rewards earned, so the smarter approach is to treat points and cash-back offers as a modest bonus, not a reason to spend more.
Flexibility can stretch the fund further once the saving is underway. Capital One recommends comparing airports, dates and neighbourhoods rather than assuming the first option is the best one. Off-peak travel, package inclusions and small conveniences such as breakfast or kitchen facilities can sometimes deliver better value than the cheapest sticker price. The same logic applies during the trip itself: keeping a travel budget, monitoring spending and protecting against fraud helps preserve the progress already made. Travel is easier to sustain when it is folded into a broader money routine rather than treated as a one-off splurge.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



