

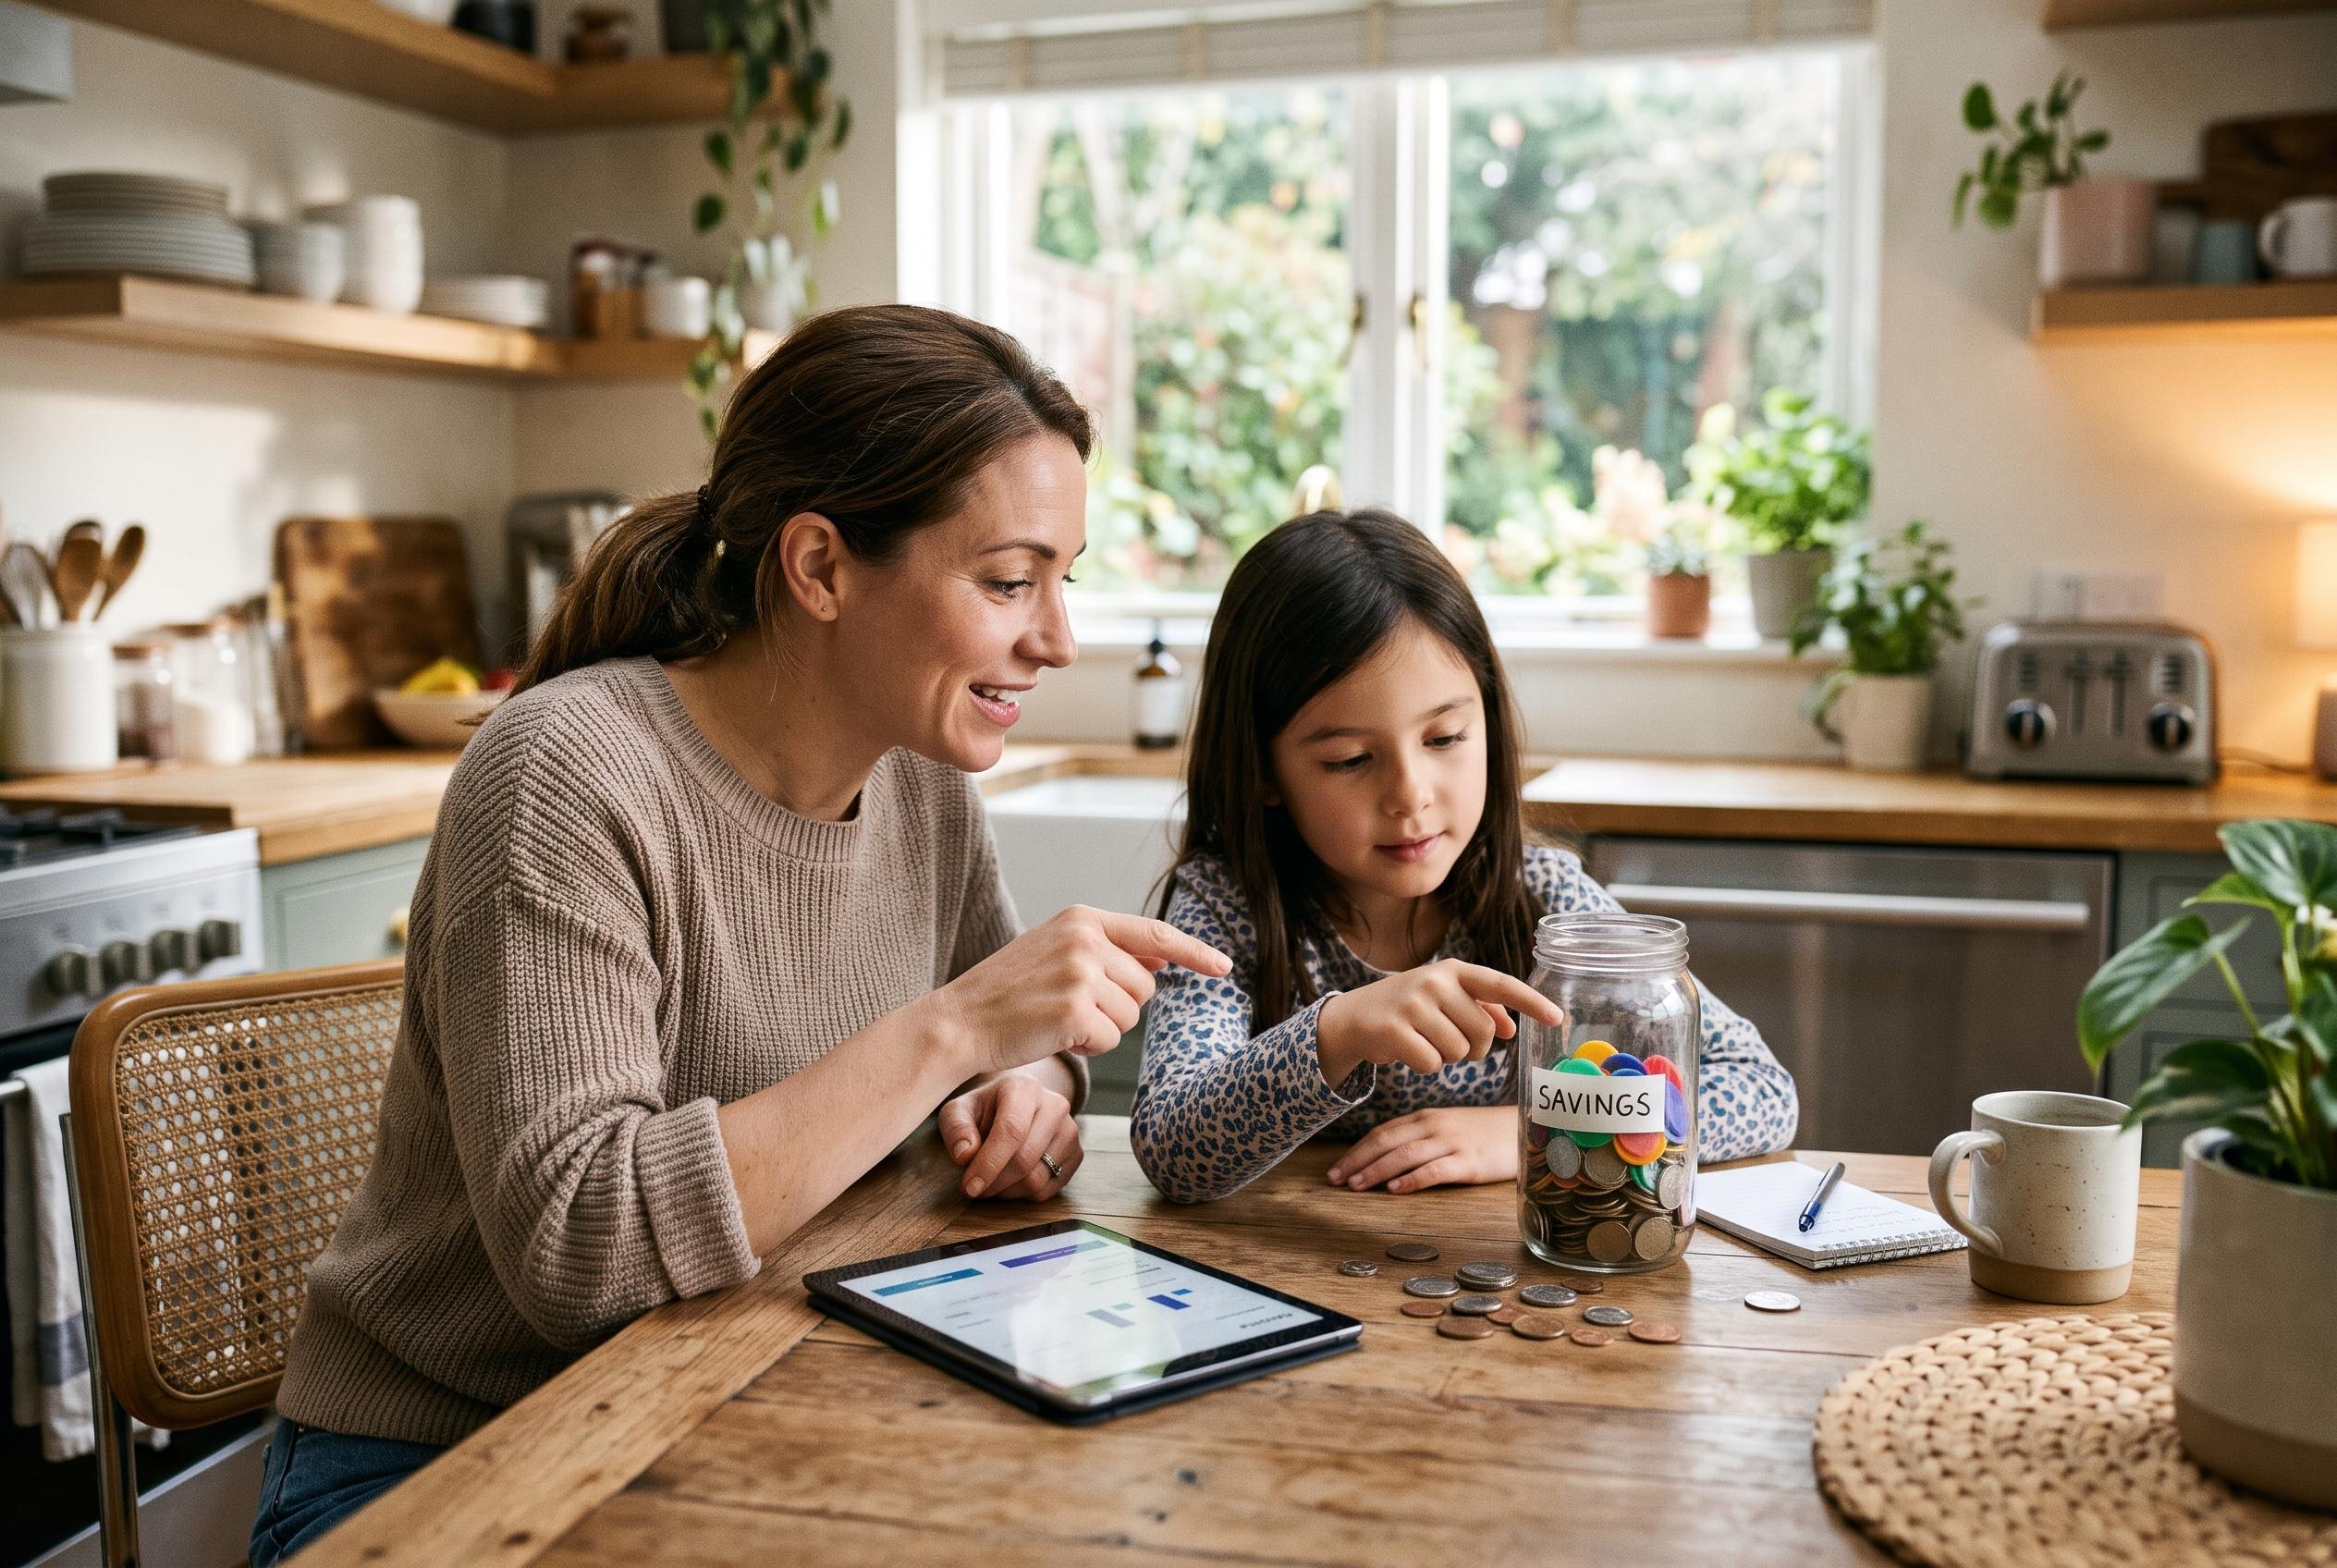

Clear goals, visible progress and everyday banking lessons can help children build patience, understand money and stay safe when using digital payments.
Helping children save towards a goal can do more than build a piggy bank balance. It can teach patience, planning and the value of waiting for something they really want, according to guidance from GetMonty, Outsmart the System Foundation and Penfed. Several parenting and financial education resources also stress that children learn best when savings goals are specific, achievable and visible, so progress feels real rather than abstract.
A simple way to begin is to choose one meaningful target, such as a toy, game or outing, and then break the cost into small steps. Experts cited by Early Life Investments and Rutinerad recommend making the process concrete: children should be able to see how much they have saved, how much is still needed and how each deposit moves them closer to the finish line. That kind of visibility turns waiting into part of the lesson rather than a frustration.
Once the idea of saving is familiar, parents can introduce the language of banking in plain terms. A deposit is money going into an account, a withdrawal is money coming out, and the balance is what remains. Interest can be explained as a small reward a bank may pay for keeping money there. A statement, meanwhile, shows what has happened in the account, helping children understand where money came from, where it went and how much is left. That foundation makes banking feel less mysterious and gives children a practical way to track their own money.
The next step is to show how everyday payments work. Debit cards draw directly from a bank account, while credit cards allow borrowing that must be repaid later, sometimes with interest. ATMs can dispense cash and, depending on the machine and bank, may also let users check balances or move money. Digital payments, whether made through a card, a phone or a banking app, still represent real transactions, so children should understand that tapping a device is not the same as money disappearing into thin air.
Safety matters just as much as convenience. Children should be taught never to share passwords, PINs or other private details, even if a message or caller claims to be from a bank. Families can reinforce a simple habit: pause, check and ask before acting on any urgent request involving money. If something seems suspicious, the safest response is to stop, speak to a trusted adult and contact the bank through its official number or website rather than replying to the message.
As children grow older, parents can also introduce cheques, electronic transfers and the difference between needs and wants. Food, clothing and school supplies are needs; toys, games and other extras are wants. Letting children make small choices in a shop, compare prices and explain their reasoning can sharpen judgement without turning money lessons into a lecture. Used together, these everyday exercises can help children become more thoughtful, confident and careful with money over time.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



