

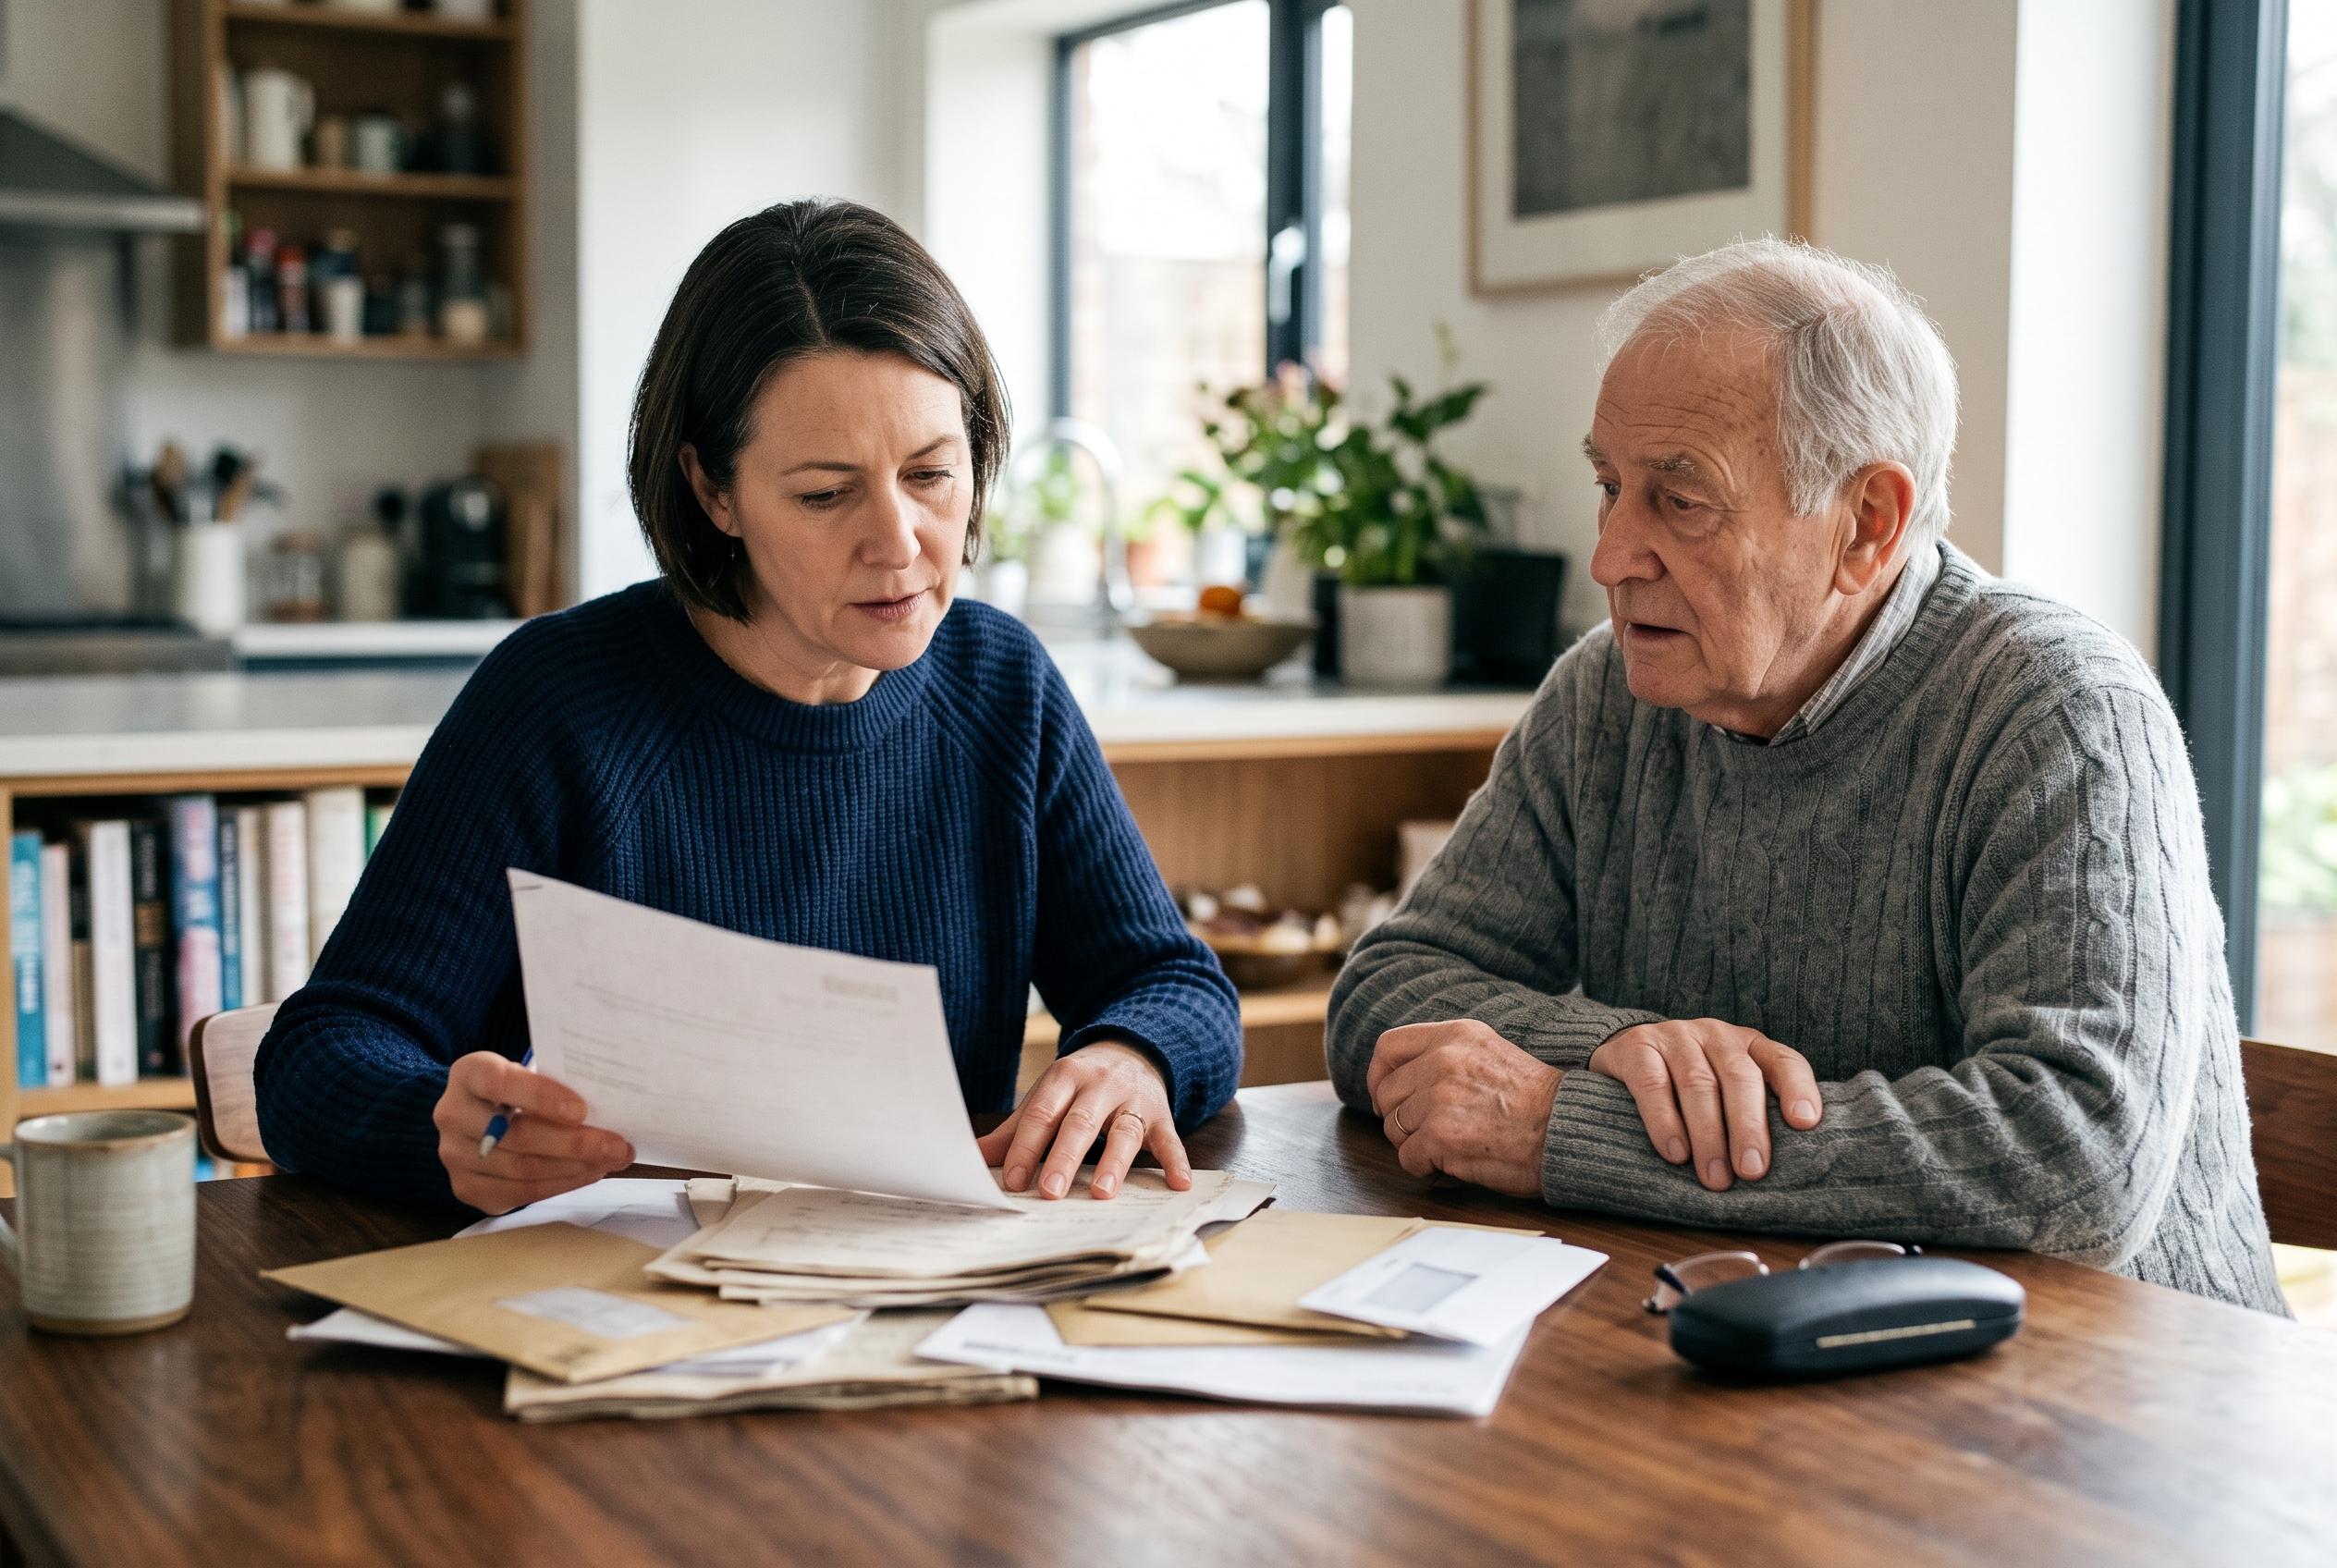

As the baby-boom generation ages, more adults are stepping into the role of financial caregiver for parents, prompting a shift in family dynamics and early planning to avoid crises and disputes over assets.
As the baby-boom generation grows older, more adults are finding themselves acting as the de facto financial chief for their parents long before any inheritance arrives. The role can begin after something as ordinary as an unpaid bill or as serious as a suspicious transfer request, but it can also emerge simply because older relatives have struggled to keep pace with the shift to digital banking and paperless accounts.
Experts say the best place to start is with a calm conversation while parents are still able to make their own decisions. Guidance from Kiplinger, backed by surveys and advice compiled from financial planners, suggests that many families still avoid talking about money, succession and end-of-life plans until a crisis forces the issue. Consumer groups including AARP and Consumer Reports also stress that these talks work best when they are respectful, patient and framed as support rather than takeover.
The next step is to gather the paperwork that shows the full picture. That means account details, monthly bills, debts, insurance policies, property records and estate documents, along with any information needed to access safe-deposit boxes or online accounts. Financial educators say bringing everything together early can help identify whether parents have enough resources for long-term care and reduce the risk of disputes later among heirs.
In many cases, families should also put a financial power of attorney in place so an adult child can legally handle bills, banking and other money matters if a parent becomes unable to do so. Advisers say that authority can be broad or limited, depending on the family’s needs, and that it can also offer protection against scams, fraud and risky mistakes. From there, the estate plan should be checked and updated well before illness or incapacity makes those decisions harder, since wills are only one part of the picture and missing account records often cause the biggest delays for surviving spouses and children.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



