

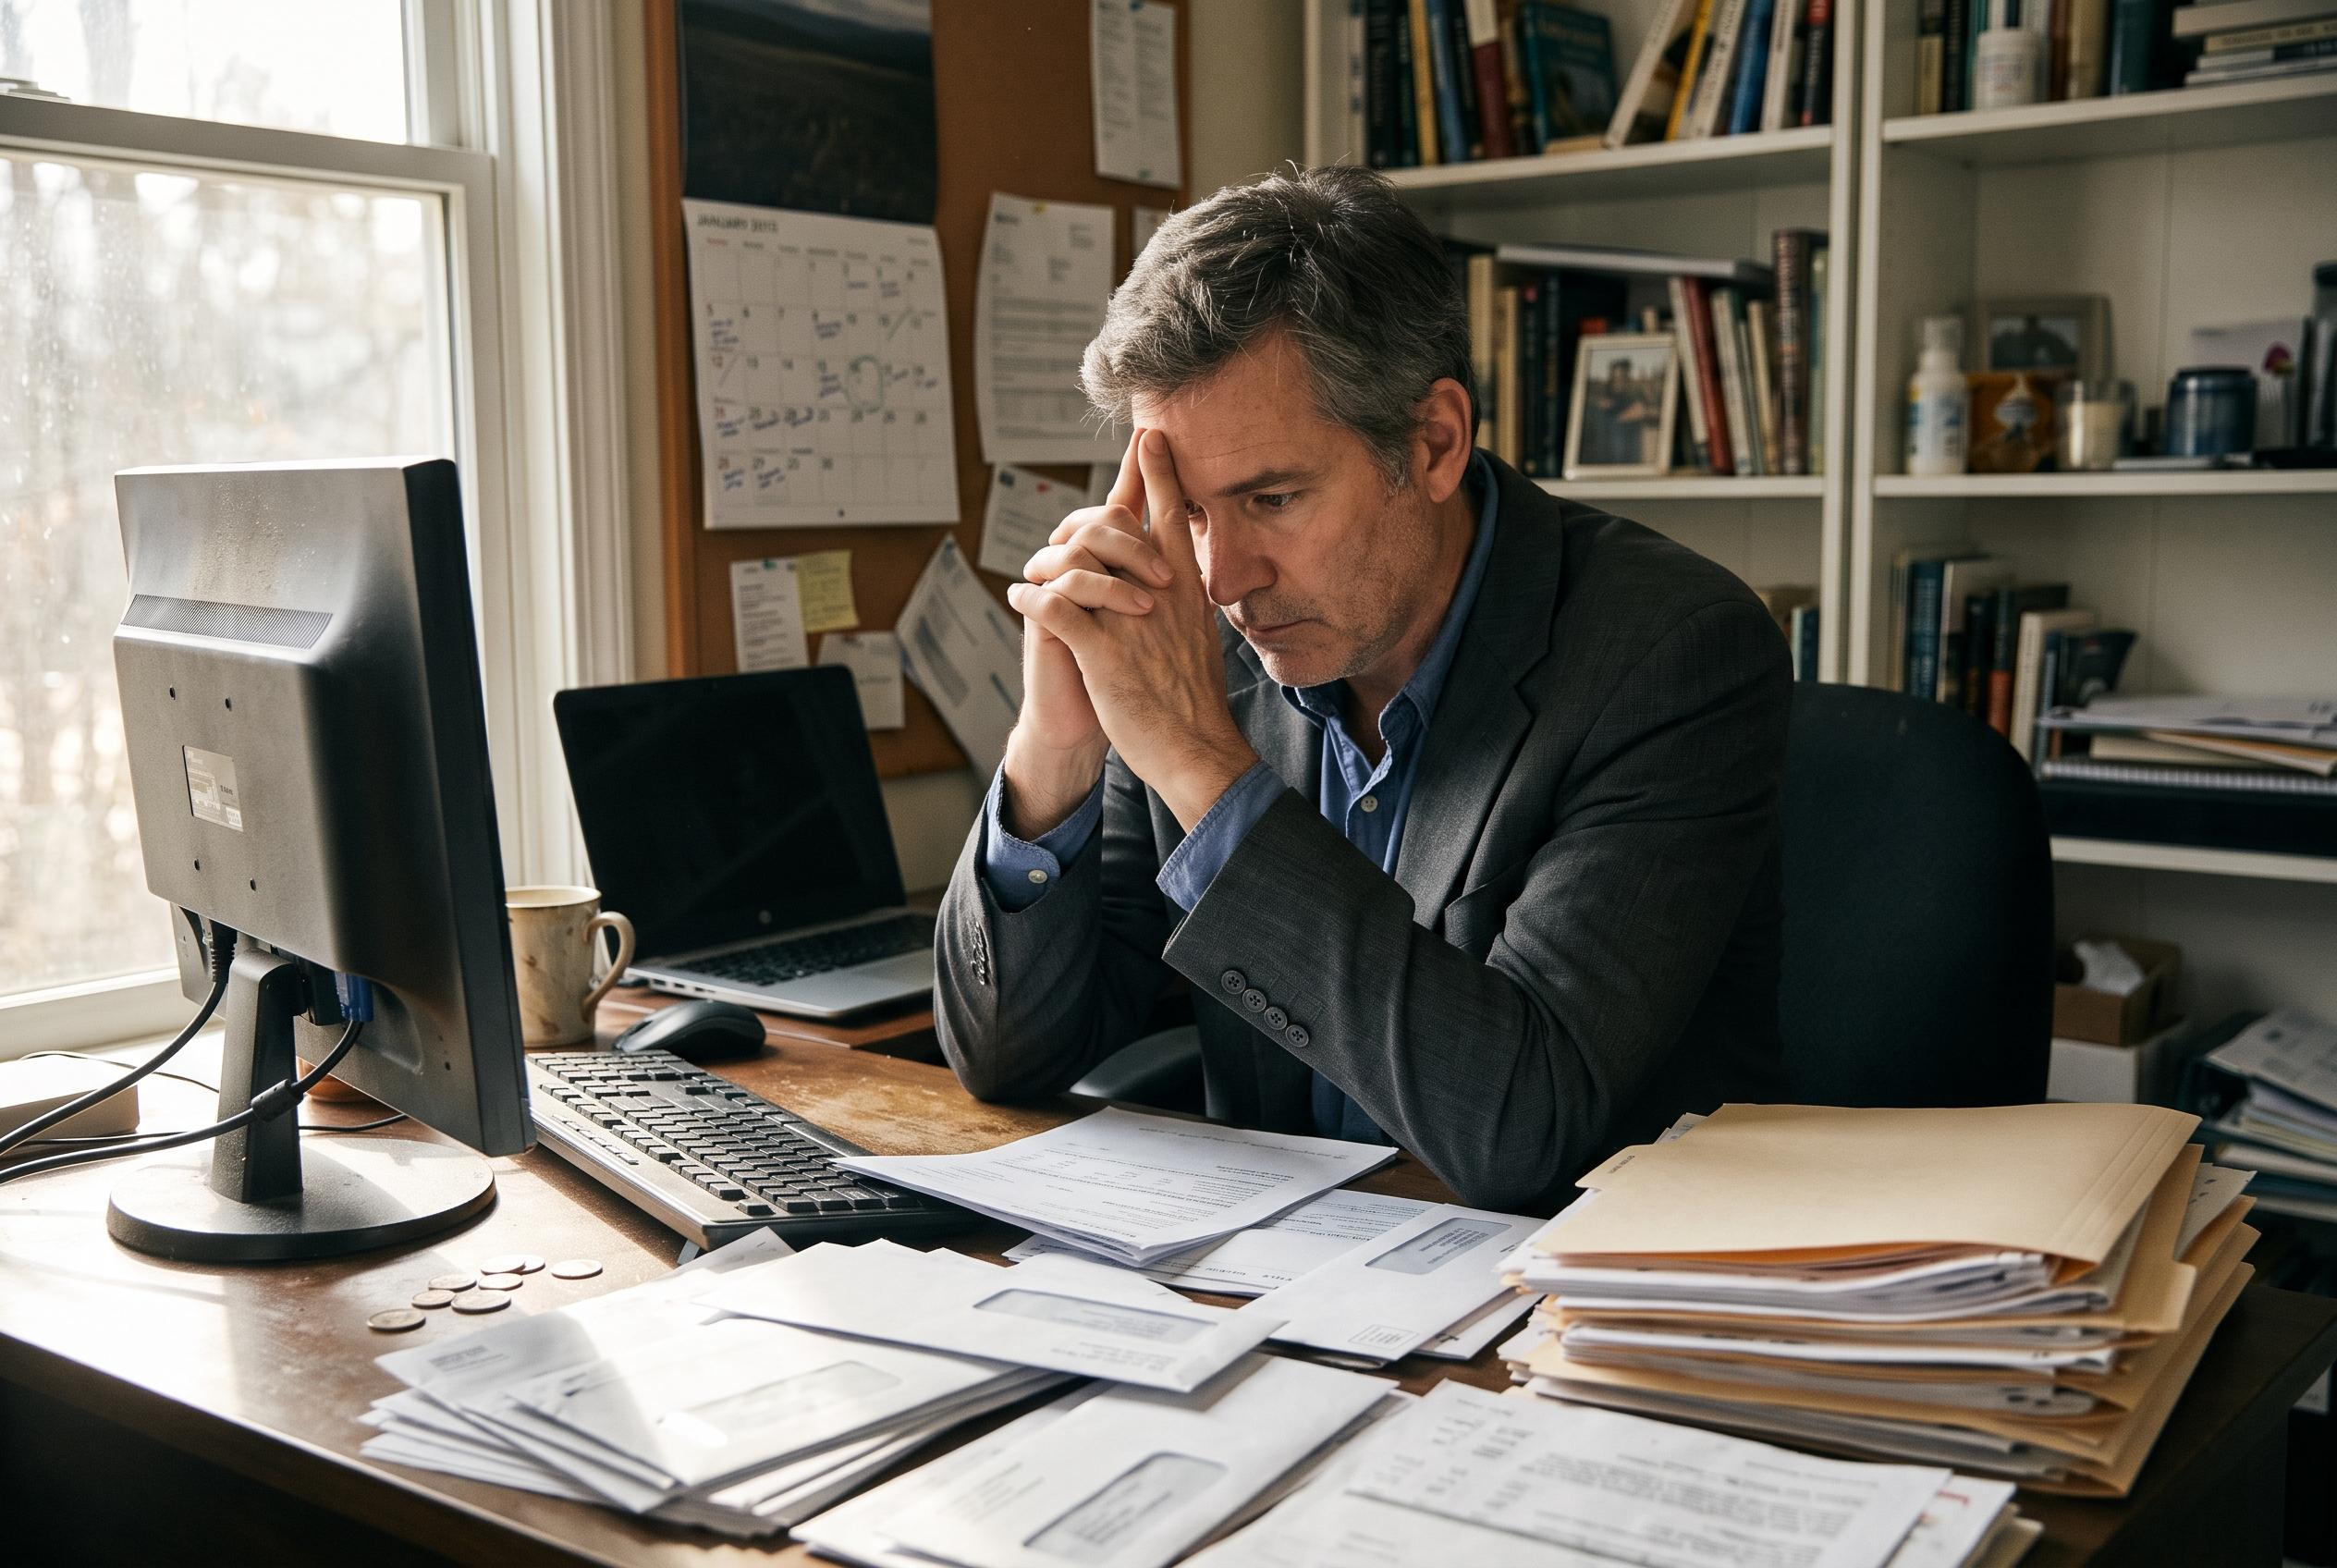

Delays in paying bills, claiming refunds, or managing expenses can quietly drain household resources and disrupt community activities, revealing the true cost of procrastination beyond mere deadlines.
Unfinished bills, ignored reminders and delayed claims may look harmless in the moment, but they can quietly drain a household budget. For families already juggling childcare, housing, food and transport costs, even modest delays can snowball into late charges, higher interest and lost savings. The article argues that the hidden price of procrastination is not just financial: it can also create stress, clutter and friction at home.
That warning is backed by the wider framework of UK penalty rules. According to guidance from accounting and tax firms, HM Revenue & Customs can impose automatic penalties for late tax filing and late payment, while business creditors may also be able to charge statutory interest and fixed compensation on overdue invoices. That means delay can cost more than a single missed deadline; it can trigger a chain of additional charges that are harder to clear once they begin.
The same logic applies to ordinary household spending. Missing an early booking discount for childcare, travel or annual insurance can mean paying full price later, and the article is right to note that these small losses add up over a year. The broader point is that procrastination often turns avoidable costs into permanent ones, especially when families miss refunds, reimbursements or tax repayments that could otherwise have been used to ease weekly spending.
For parents involved in school groups, clubs or other community projects, delay can be even more disruptive. Late expense claims or slow processing of awarded funds can squeeze cash flow and leave less money available for practical needs such as equipment, trips or activities. In that sense, financial admin is not just paperwork; it is part of how families and community groups keep day-to-day plans on track.
The practical advice is straightforward: deal with financial paperwork as soon as it arrives, set reminders before deadlines, block out regular time to review accounts and keep key documents in one place. Used consistently, those habits can reduce fees, improve cash flow and make it easier to spot savings opportunities before they disappear. For many households, the real gain is not only lower costs but less mental load.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



