

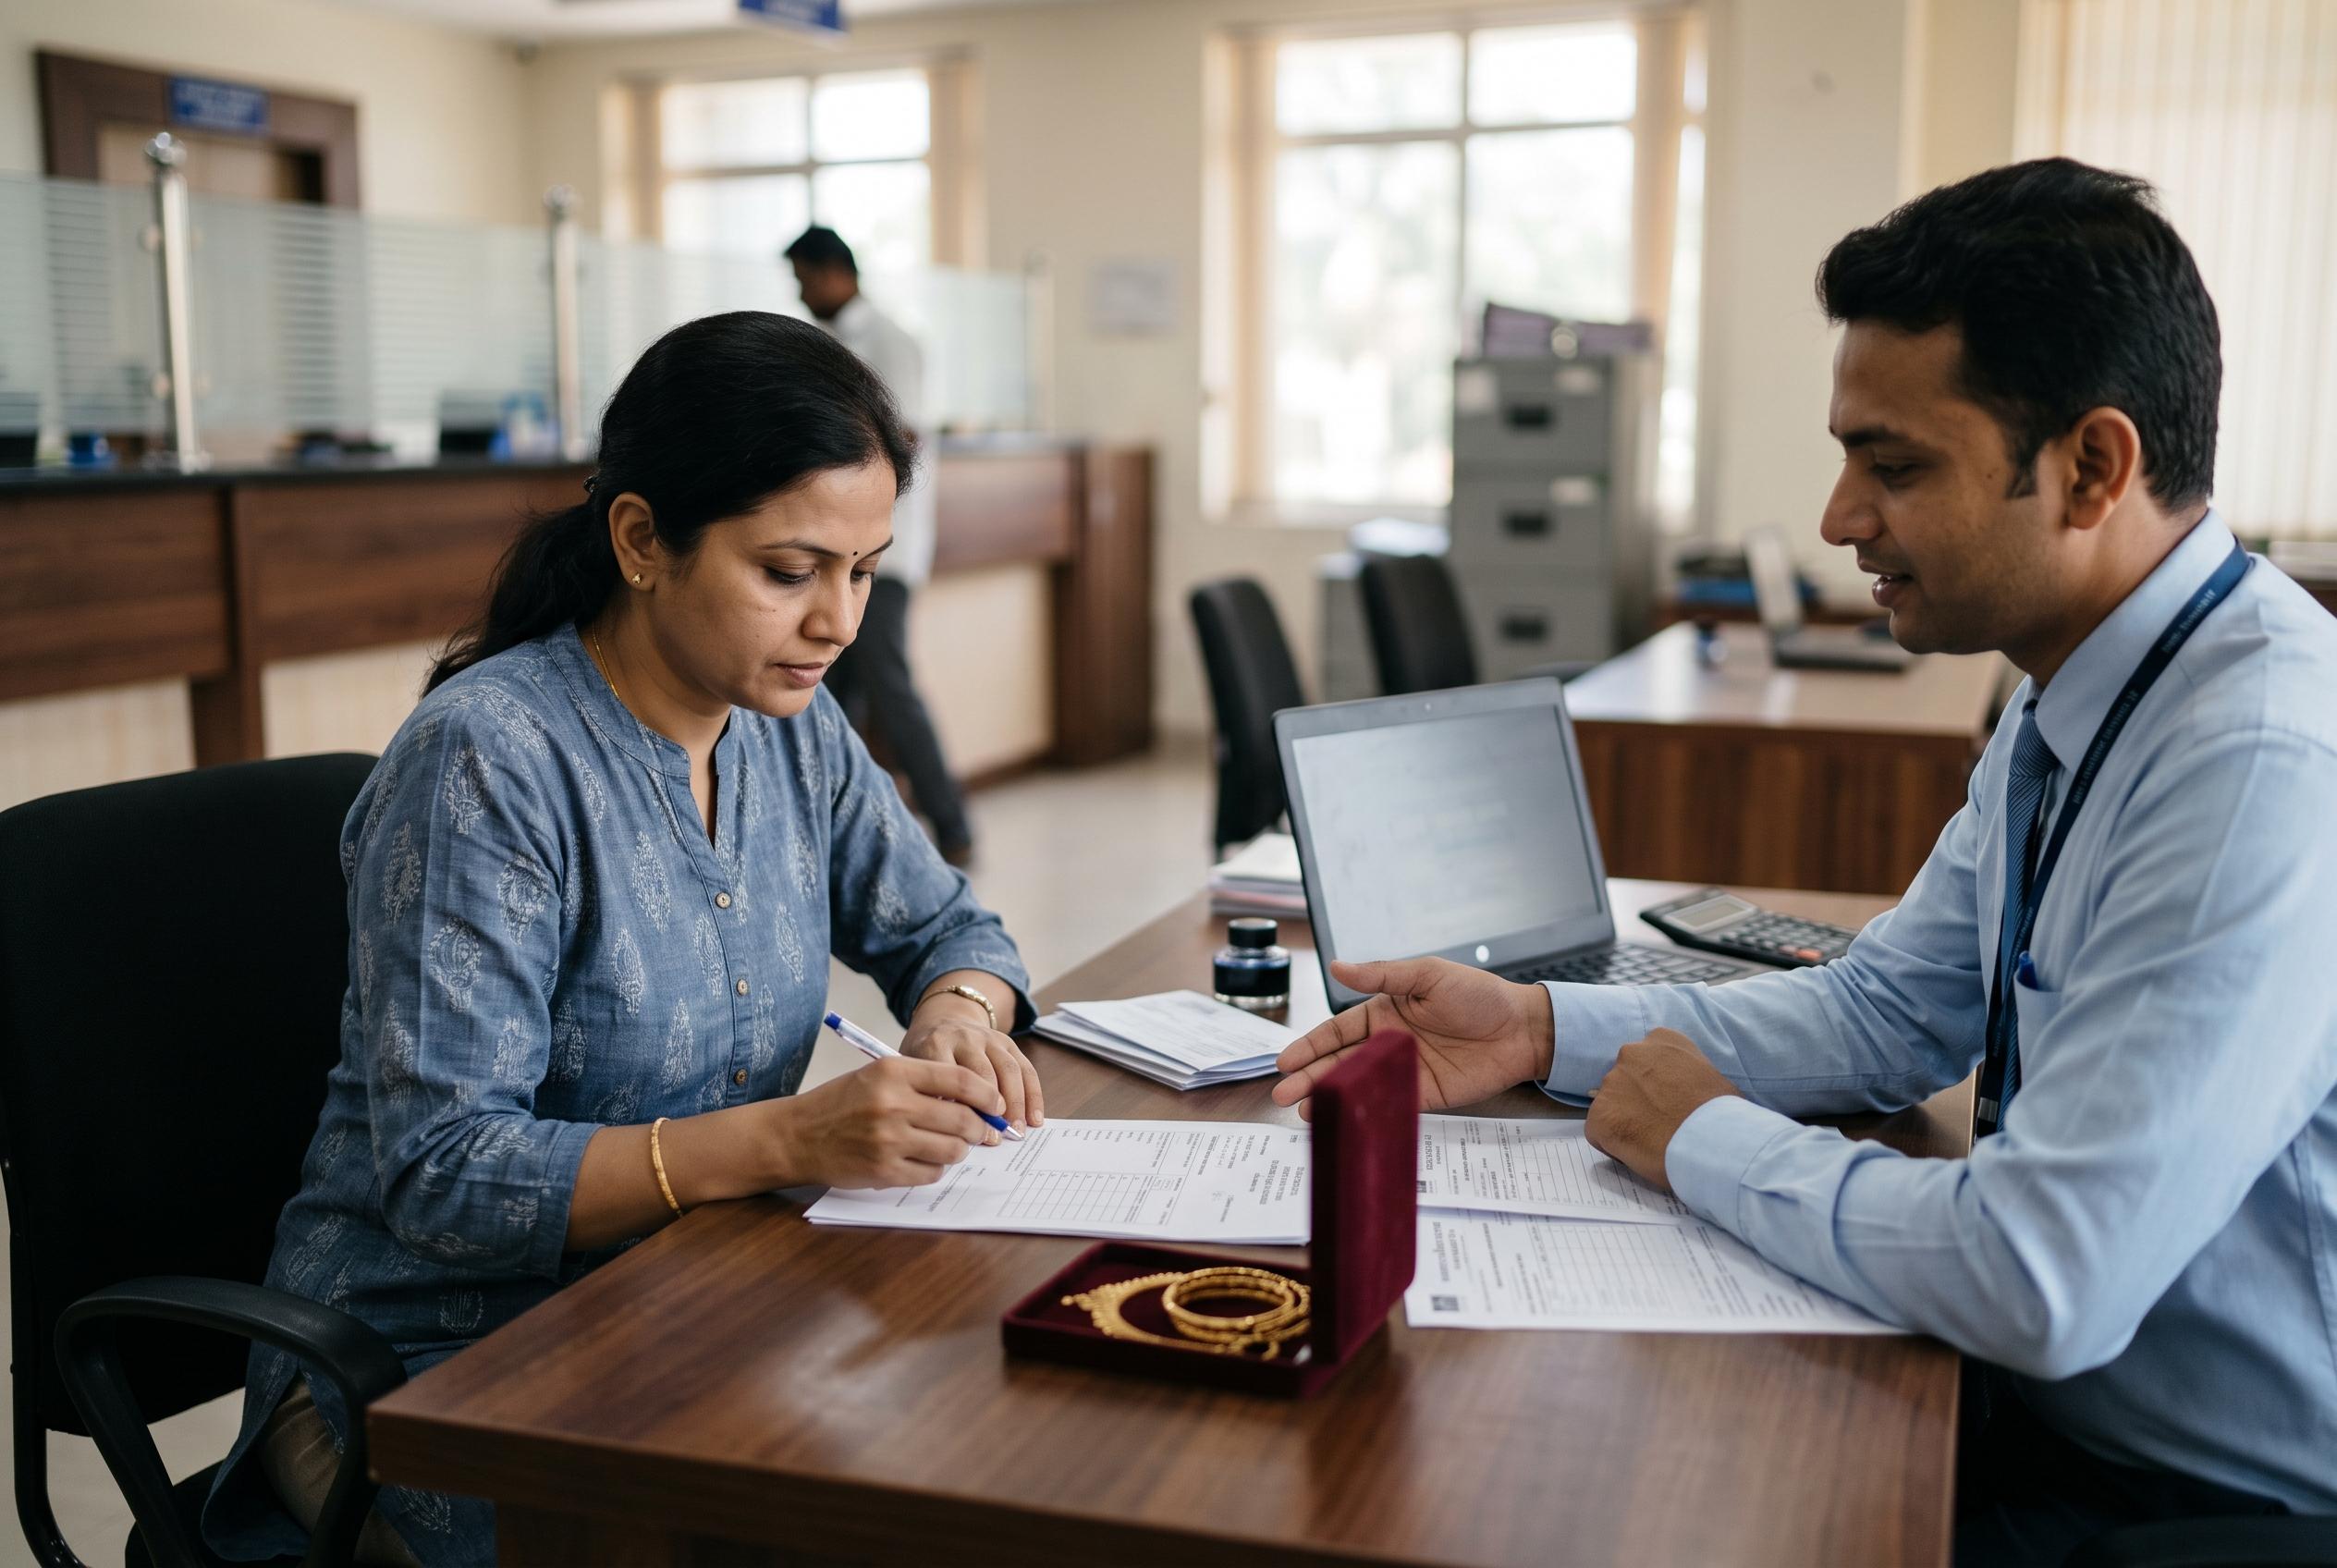

Borrowers can now extend their existing gold loans with quicker, simpler top-up options, providing additional funds without starting a new borrowing process. This shift enhances financial flexibility but requires responsible repayment to avoid rising debt.
A gold loan top-up can offer a practical way to raise extra cash without starting a new borrowing arrangement from scratch. Instead of pledging jewellery again or applying for a separate loan, borrowers can sometimes draw more money against the same gold if there is still room under the lender’s loan-to-value limit. That makes the option especially useful when an existing loan is in place but an unexpected expense still needs to be covered.
According to Muthoot Finance, the attraction of a top-up lies in its speed and simplicity. Because the gold has already been pledged, the process usually involves less paperwork than a fresh application. The lender reassesses the current value of the ornaments, compares that figure with the outstanding balance, and decides whether there is scope to extend more credit. Other lenders, including HDFC Bank, describe the same basic structure: valuation, assessment of the remaining headroom within the applicable loan-to-value ceiling, and then approval if the borrower qualifies.
The additional amount is not automatic. Lenders generally look at repayment discipline, the current market price of gold, and their own internal lending rules before approving a higher limit. IIFL’s guidance on the subject says a clean repayment record and available room under the loan-to-value ratio are central to the decision. A stronger gold price can improve the borrowing headroom, while missed or delayed payments may reduce the chance of approval. Some lenders also say a healthier credit profile can help, even though the loan itself is secured against physical gold.
For borrowers, the main advantage is flexibility. A top-up can help cover medical bills, education costs or household repairs without opening a new loan account. It may also be cheaper than an unsecured personal loan, depending on the lender and the borrower’s profile. At the same time, it should still be treated as serious debt: the repayment terms remain important, and the value of the pledged gold continues to underpin the loan. Used carefully, a top-up can make an existing gold loan more adaptable; used casually, it can simply increase financial pressure.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



