

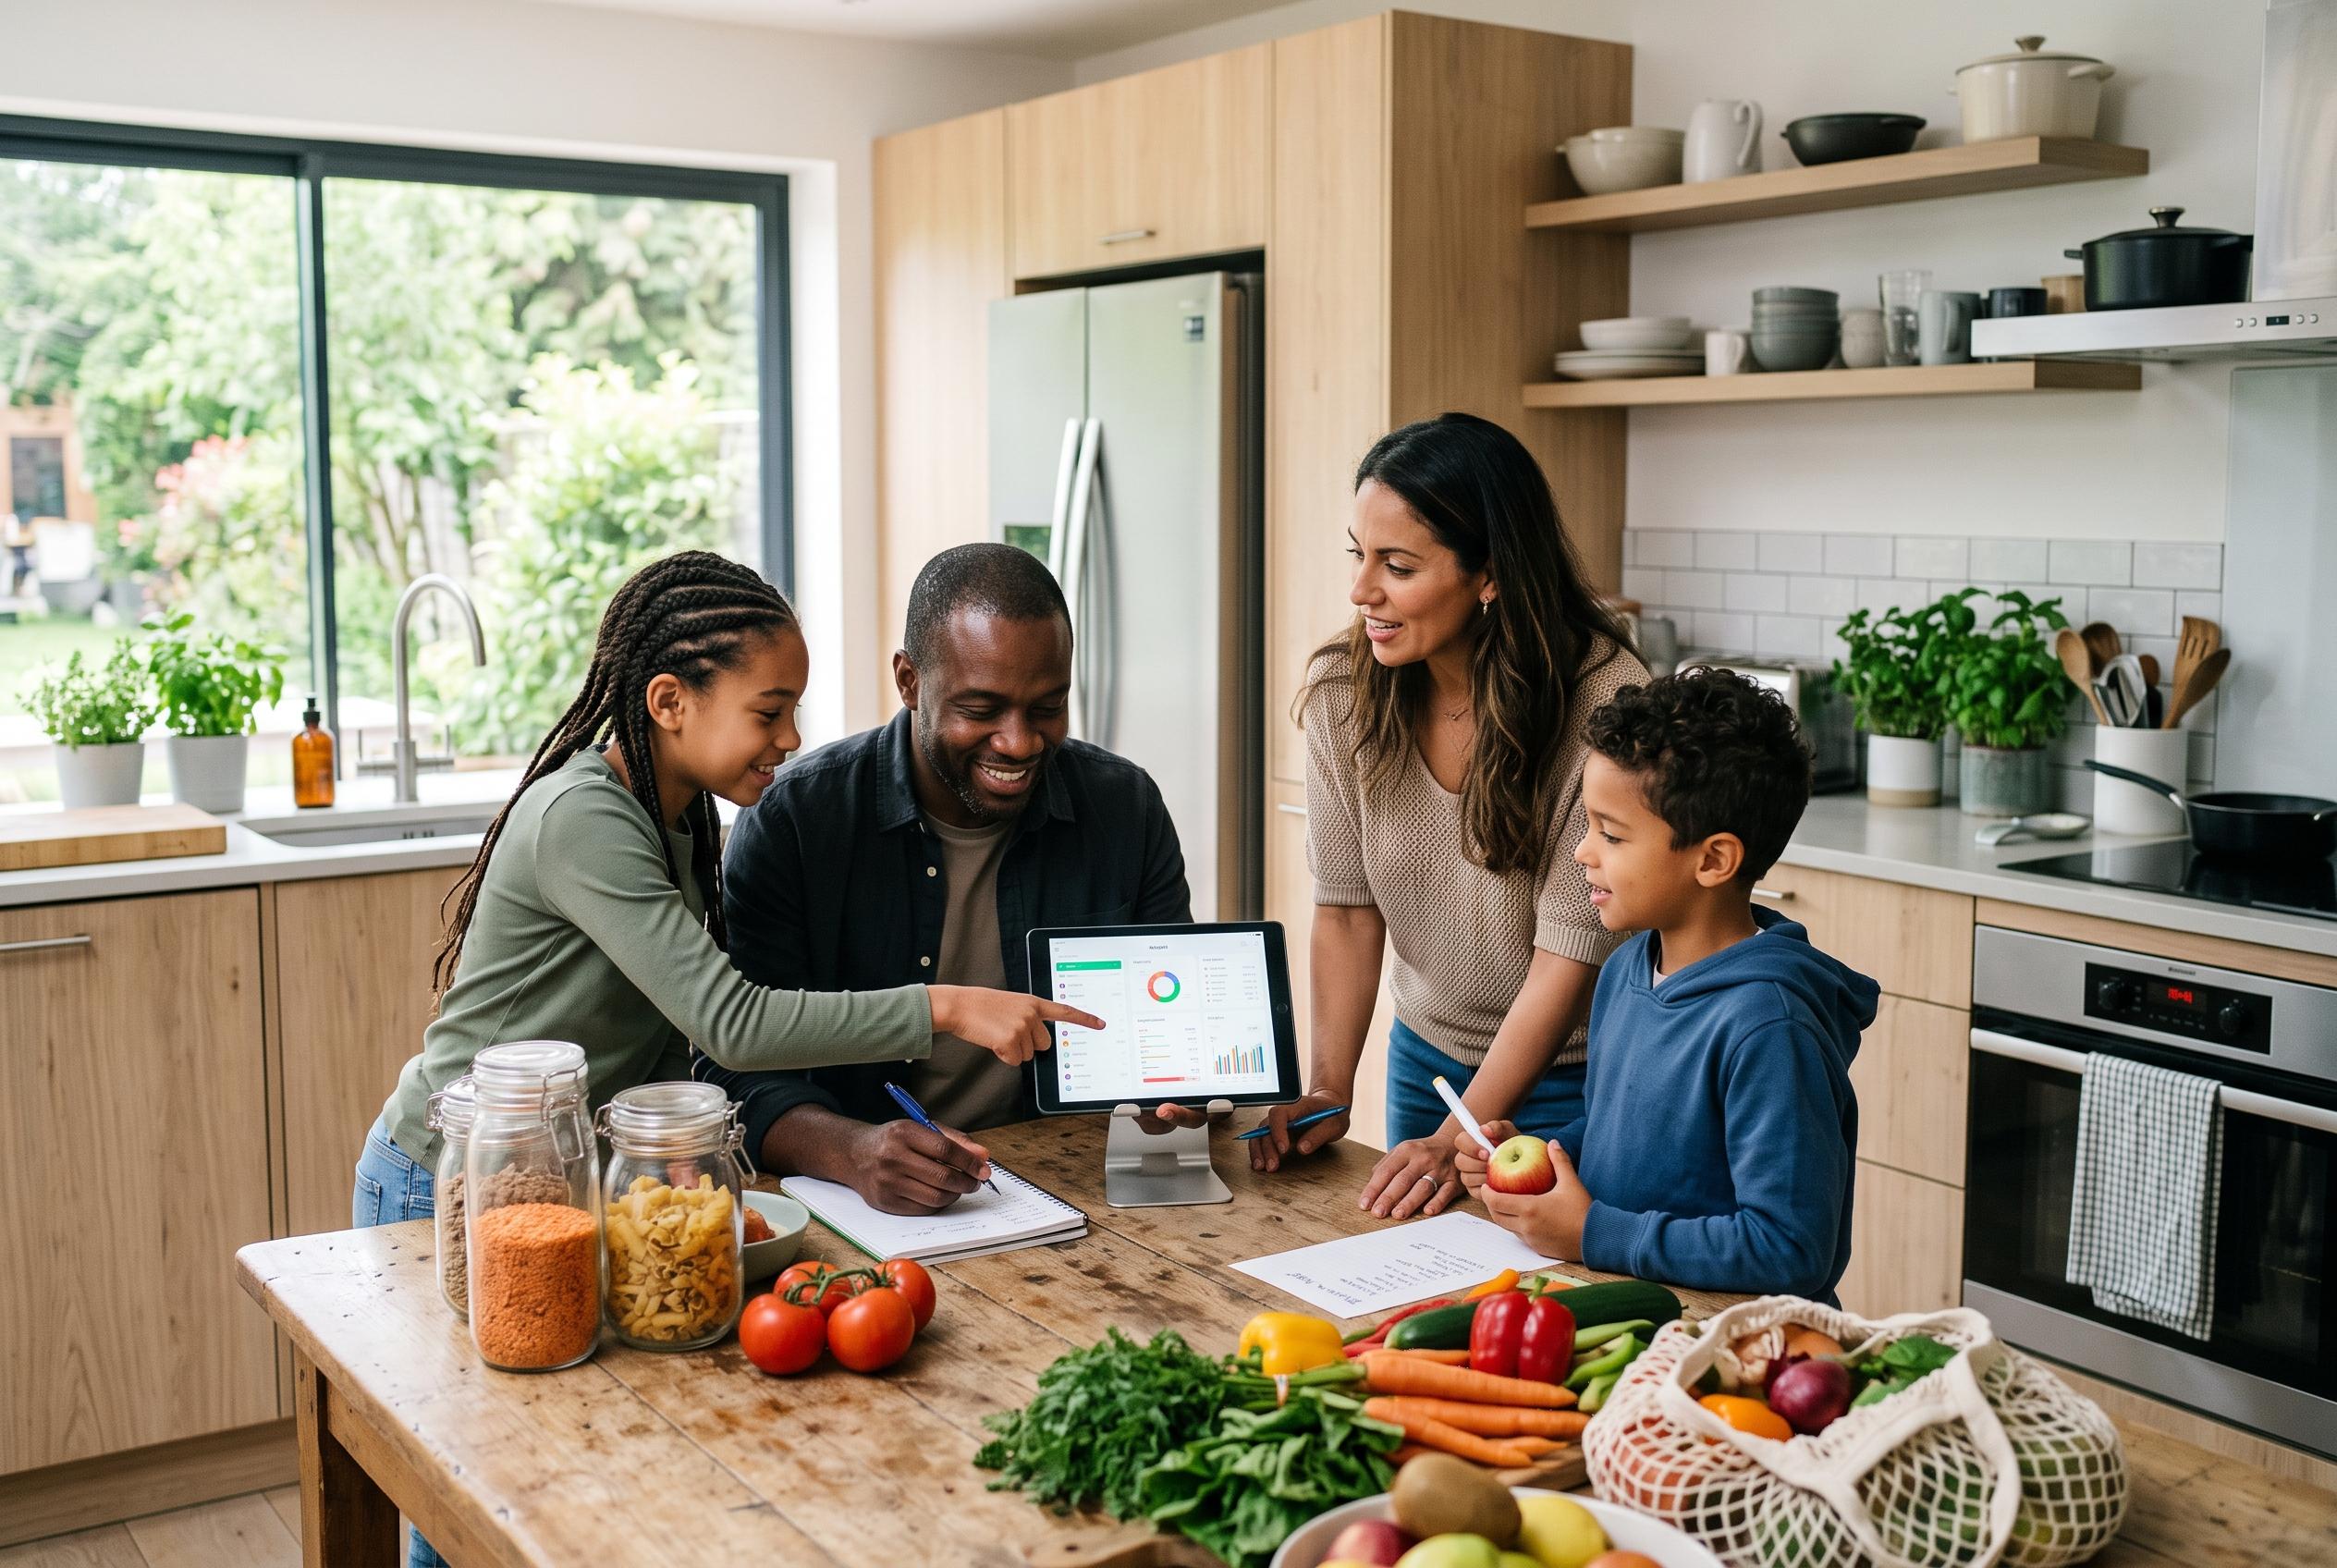

Innovative household strategies such as meal planning, energy efficiency, and disciplined savings are helping families achieve greater financial stability and control, amid ongoing economic challenges.
Managing a family budget is less about stripping life down to the essentials than about making smarter decisions with the money already coming in. Fidelity says many households can find meaningful savings by planning meals, comparing store brands, cooking in larger batches, limiting meals out and trimming transport costs. Chase also notes that a clear budget is the starting point for seeing where income goes and for setting realistic savings goals. The result is not just lower spending, but a more deliberate system that gives families greater control over day-to-day finances.
Small changes at home often create the quickest gains. U.S. Bank says tracking spending patterns can expose waste, while automated payments and a more disciplined routine can prevent money from disappearing unnoticed. Its guidance also points to decluttering as a practical financial tool, since clearing out unused possessions can reduce duplicate purchases and even generate cash from items no longer needed. That idea runs through many household cost-cutting strategies: save a little here, and redirect it towards a more important goal there.
Food and utilities are two of the most obvious places to start. Fidelity recommends meal planning, buying in bulk, using energy-efficient lighting, switching off devices when they are not in use and fitting simple water-saving fixtures. Gerald similarly argues that families can cut monthly food bills by planning ahead, choosing generic brands and reducing the frequency of restaurant meals. In practice, those habits can create a steady buffer, especially when paired with a sinking fund, which Chase describes as a simple way to earmark savings for predictable expenses such as holidays or large annual bills.
Transportation is another area where routine maintenance and better planning can limit financial strain. Fidelity advises households to review auto insurance costs, consider commuting benefits and look for ways to reduce the expense of getting to work and school. Regular upkeep can also avoid the far higher cost of unexpected repairs. In the same spirit, a disciplined approach to vehicle ownership can preserve both cash flow and long-term value, rather than forcing families into emergency spending when something breaks.
Bigger household transitions call for a different kind of planning. U.S. Bank says economising is not only about spending less, but also about using time and space more efficiently. That logic applies to major clear-outs, moves and estate clean-ups, where sorting, selling and donating items can be overwhelming without outside help. In those situations, professional support may preserve more value and reduce stress, particularly when families are dealing with a death, a relocation or the downsizing of a long-held home.
Several of the sources also stress the importance of protecting the home itself. The original article’s advice on backup power, water treatment and filtration fits a broader theme: spending on resilience can prevent larger losses later. A generator may reduce the risk of spoiled food or damage during outages, while cleaner water can ease wear on appliances and plumbing. These are not flashy purchases, but they can shield a household from expenses that are far more disruptive than the initial outlay.
Longer-term security depends on more than cutting costs. Chase and NerdWallet both recommend setting specific savings targets and building a structure that makes progress visible. NerdWallet highlights the 50/30/20 rule as one useful framework, with a portion of income set aside for savings and debt repayment. Chase likewise urges families to define goals, whether that means building retirement savings, paying down debt or saving for predictable future needs. The common thread is discipline: savings work best when they are planned, not improvised.
That same discipline applies to legal and investment planning. The original article’s emphasis on estate documents, wills and wealth management reflects a simple truth: savings are only fully protected when families think ahead. Once immediate expenses are under control, regular investing, tax-aware planning and clear legal instructions can help preserve what has been built. For households willing to combine everyday frugality with longer-term preparation, the payoff is greater than lower bills. It is a sturdier financial foundation, with more room for future choices.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



