

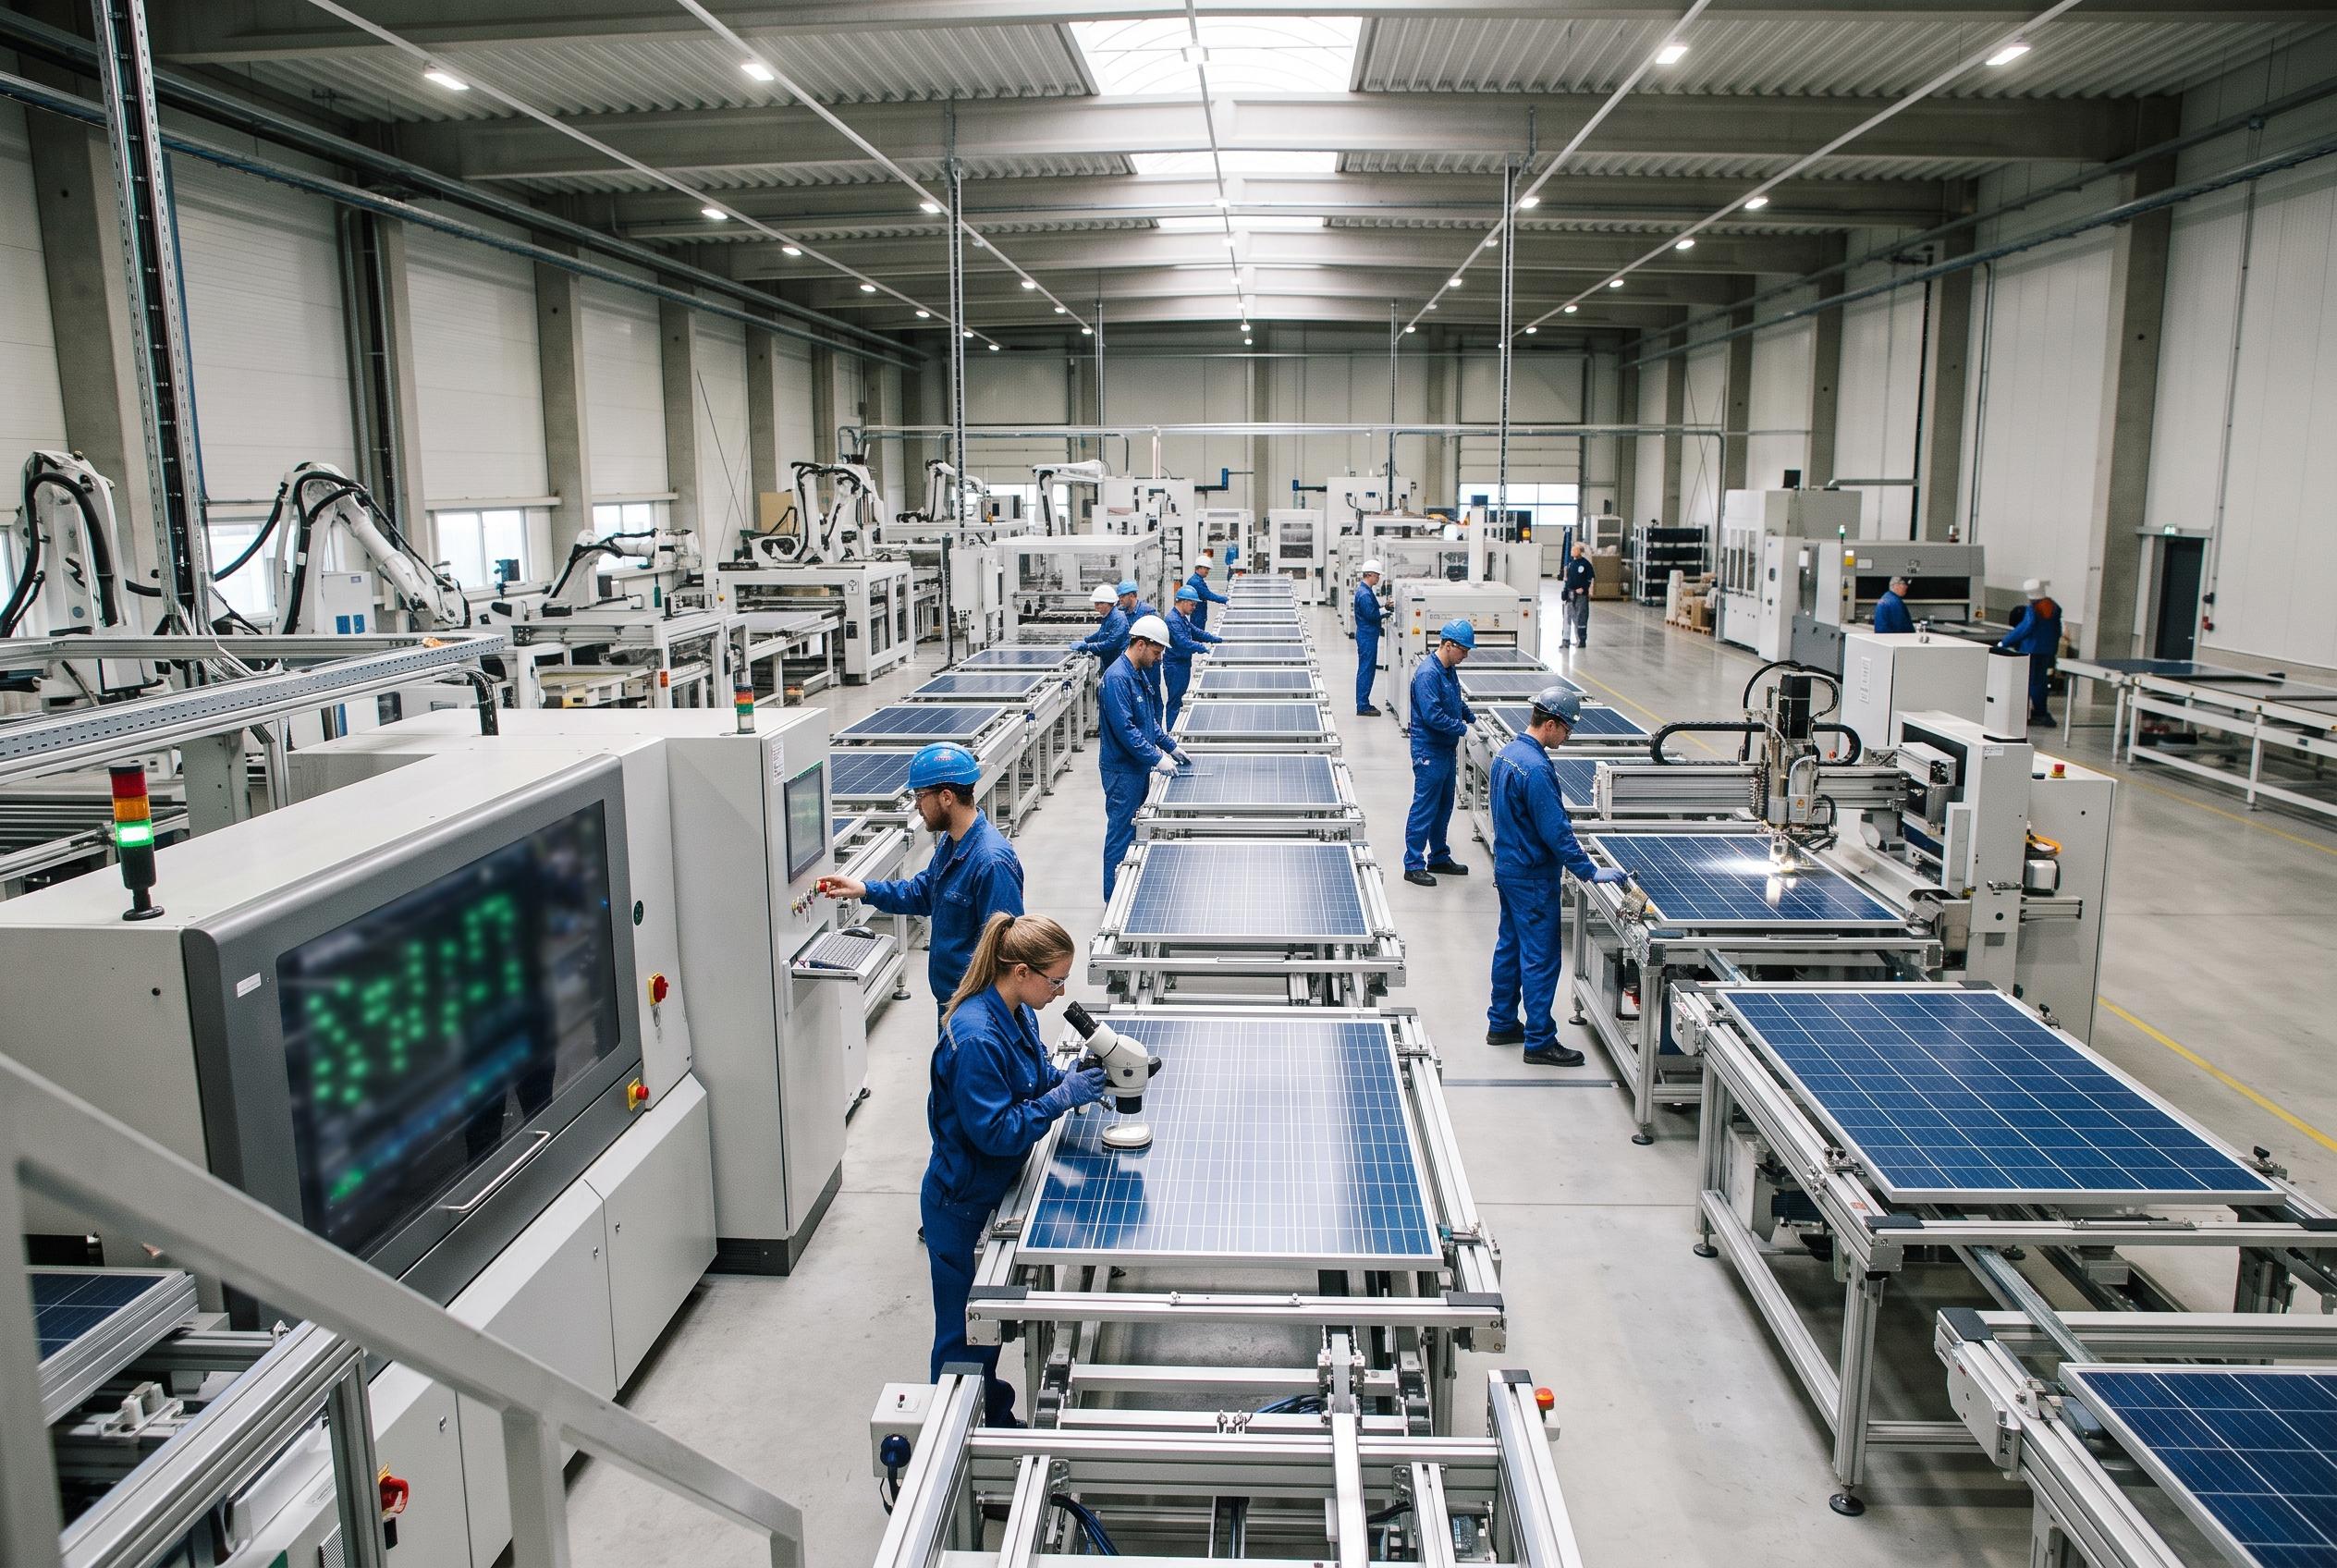

Analysts have set a ₹395 target for Emmvee Photovoltaic Power, citing its integrated manufacturing capacity, TOPCon positioning, strong order book and scope for margin growth.
Emmvee Photovoltaic Power has drawn a positive initial view from brokers, with analysts putting a target price of ₹395 on the stock against a recent market price of ₹297.05. The valuation implies meaningful upside and reflects confidence that the solar equipment maker can continue to benefit from India’s push to expand renewable power capacity.
According to the note, Emmvee is one of the country’s larger integrated manufacturers of solar photovoltaic modules and cells, with 10.3 GW of module capacity and 2.94 GW of cell capacity. The company’s website says it operates four manufacturing units across two locations in Karnataka and that its product mix includes bifacial and monofacial TOPCon modules and cells, along with Mono PERC modules. Emmvee says it was founded in 2007 and is based in Bengaluru.
The brokerage argues that the company is well placed because it is an early mover in TOPCon, a higher-efficiency solar technology that has seen supply shortages in India. Emmvee also benefits from being listed in the Approved List of Models and Manufacturers, which allows it to supply projects that require domestically made components. The company says this positioning, combined with its scale and integration across modules and cells, makes it the country’s second-largest pure-play integrated cell-and-module maker by capacity.
The note also points to a strong order book and firmer margins as evidence that Emmvee is already capturing industry tailwinds. It expects those advantages to continue as India works towards its clean-energy goals and as the company adds capacity and deepens backward integration, a move that should reduce reliance on outside suppliers over time.
On valuation, the brokerage said Emmvee is trading below some peers on forward enterprise value to earnings before interest, tax, depreciation and amortisation. It estimated the stock at 6.2 times one-year forward EBITDA and 5.7 times FY28 earnings, both at a discount to the broader sector and to larger rivals such as Waaree and Premier. On that basis, it assigned a “Buy” rating and a target based on 7.5 times its projected four-quarter ending September 2028 EBITDA.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



