

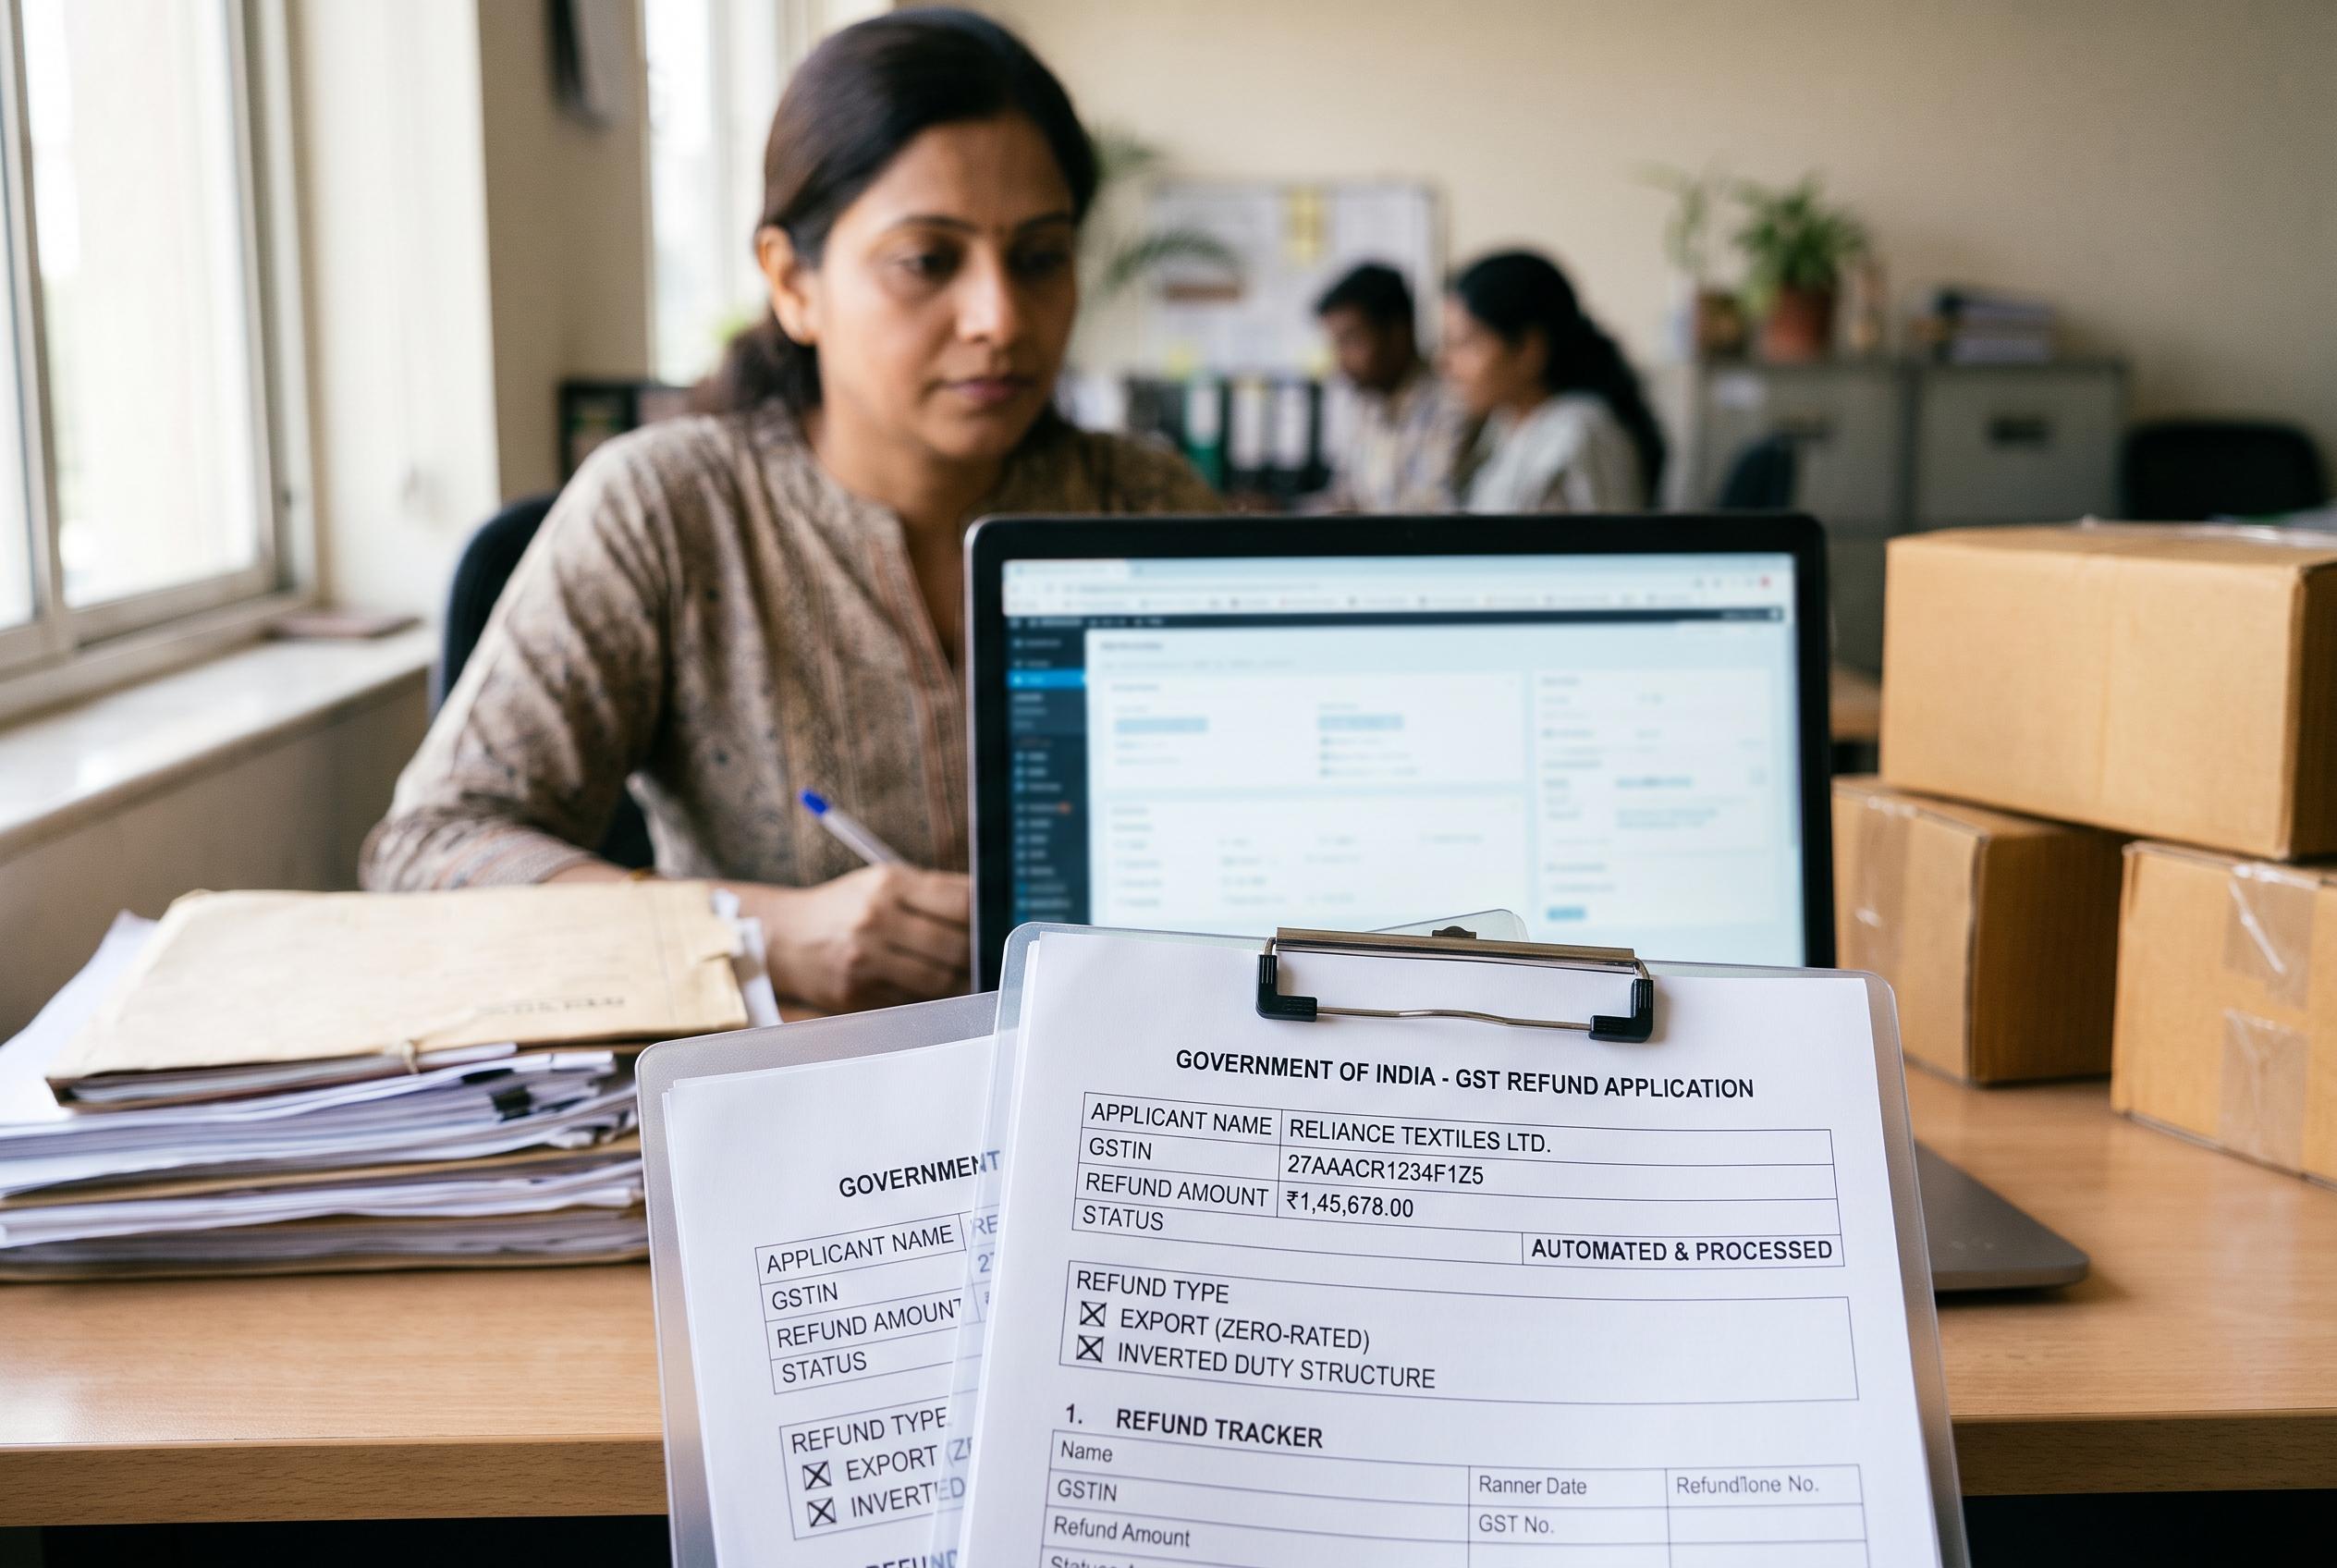

New rules cut the acknowledgement deadline to 10 days and allow 90% provisional refunds for eligible export and inverted-duty claims within three working days, putting greater emphasis on accurate digital filings.
India’s indirect tax administration has moved to speed up GST refunds, with the Central Board of Indirect Taxes and Customs introducing amendments designed to reduce delays and push more of the process on to the common portal. The changes, notified on 26 October 2026, follow recommendations made at the 57th GST Council meeting on 8 October 2026 and are aimed at exporters, businesses with inverted duty structure claims and taxpayers waiting for refunds of excess cash balances in the electronic cash ledger.
Under the revised framework, the time available for a proper officer to issue either an acknowledgement in FORM GST RFD-02 or a deficiency memo in FORM GST RFD-03 has been cut from 15 days to 10. If no action is taken within that period, the application will be treated as acknowledged by the system, and the 60-day clock for sanction under Section 54(7) will begin from the filing date. According to the Council’s October recommendations, this shift is intended to stop refund claims from languishing because of late acknowledgements or procedural objections that restart the limitation period.
The most significant operational change is the move towards automated refund processing in lower-risk cases. For zero-rated supplies and inverted duty structure claims, the common portal will now issue a provisional refund order for 90% of the claim within three working days of acknowledgement, without requiring fresh validation by an officer. The system will also generate refund orders for excess balances in the electronic cash ledger, after adjusting any outstanding demand. The Council had flagged this as a first phase, with a broader second phase expected to extend system-based processing further, including full automated sanction in zero-rated cases.
The amendments also tighten the way refund applications are filed and supported. Applications are now to be submitted electronically through the common portal, removing the earlier reference to filing directly or through a facilitation centre. From 1 December 2026, the refund form will require structured details of invoices rather than only invoice numbers and dates, and the revised FORM GST RFD-01 will be built to capture that information in a system-readable format. New declaration requirements have also been added, including a statement on prosecution history for certain large tax-evasion cases, while a separate declaration for capital goods is due to take effect from 1 April 2027.
For businesses, the changes should bring faster access to cash, but they also raise the cost of errors in filings. The new process depends heavily on matching data across returns, shipping bills, export documents and ledger balances, and the tax administration is clearly signalling that it expects the portal to validate claims with less manual intervention. EY, in a technical note on the notification, said the reforms point to a more automated refund regime, but also highlighted the practical importance of getting the form data right because the system will rely more on validation than human scrutiny.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



