

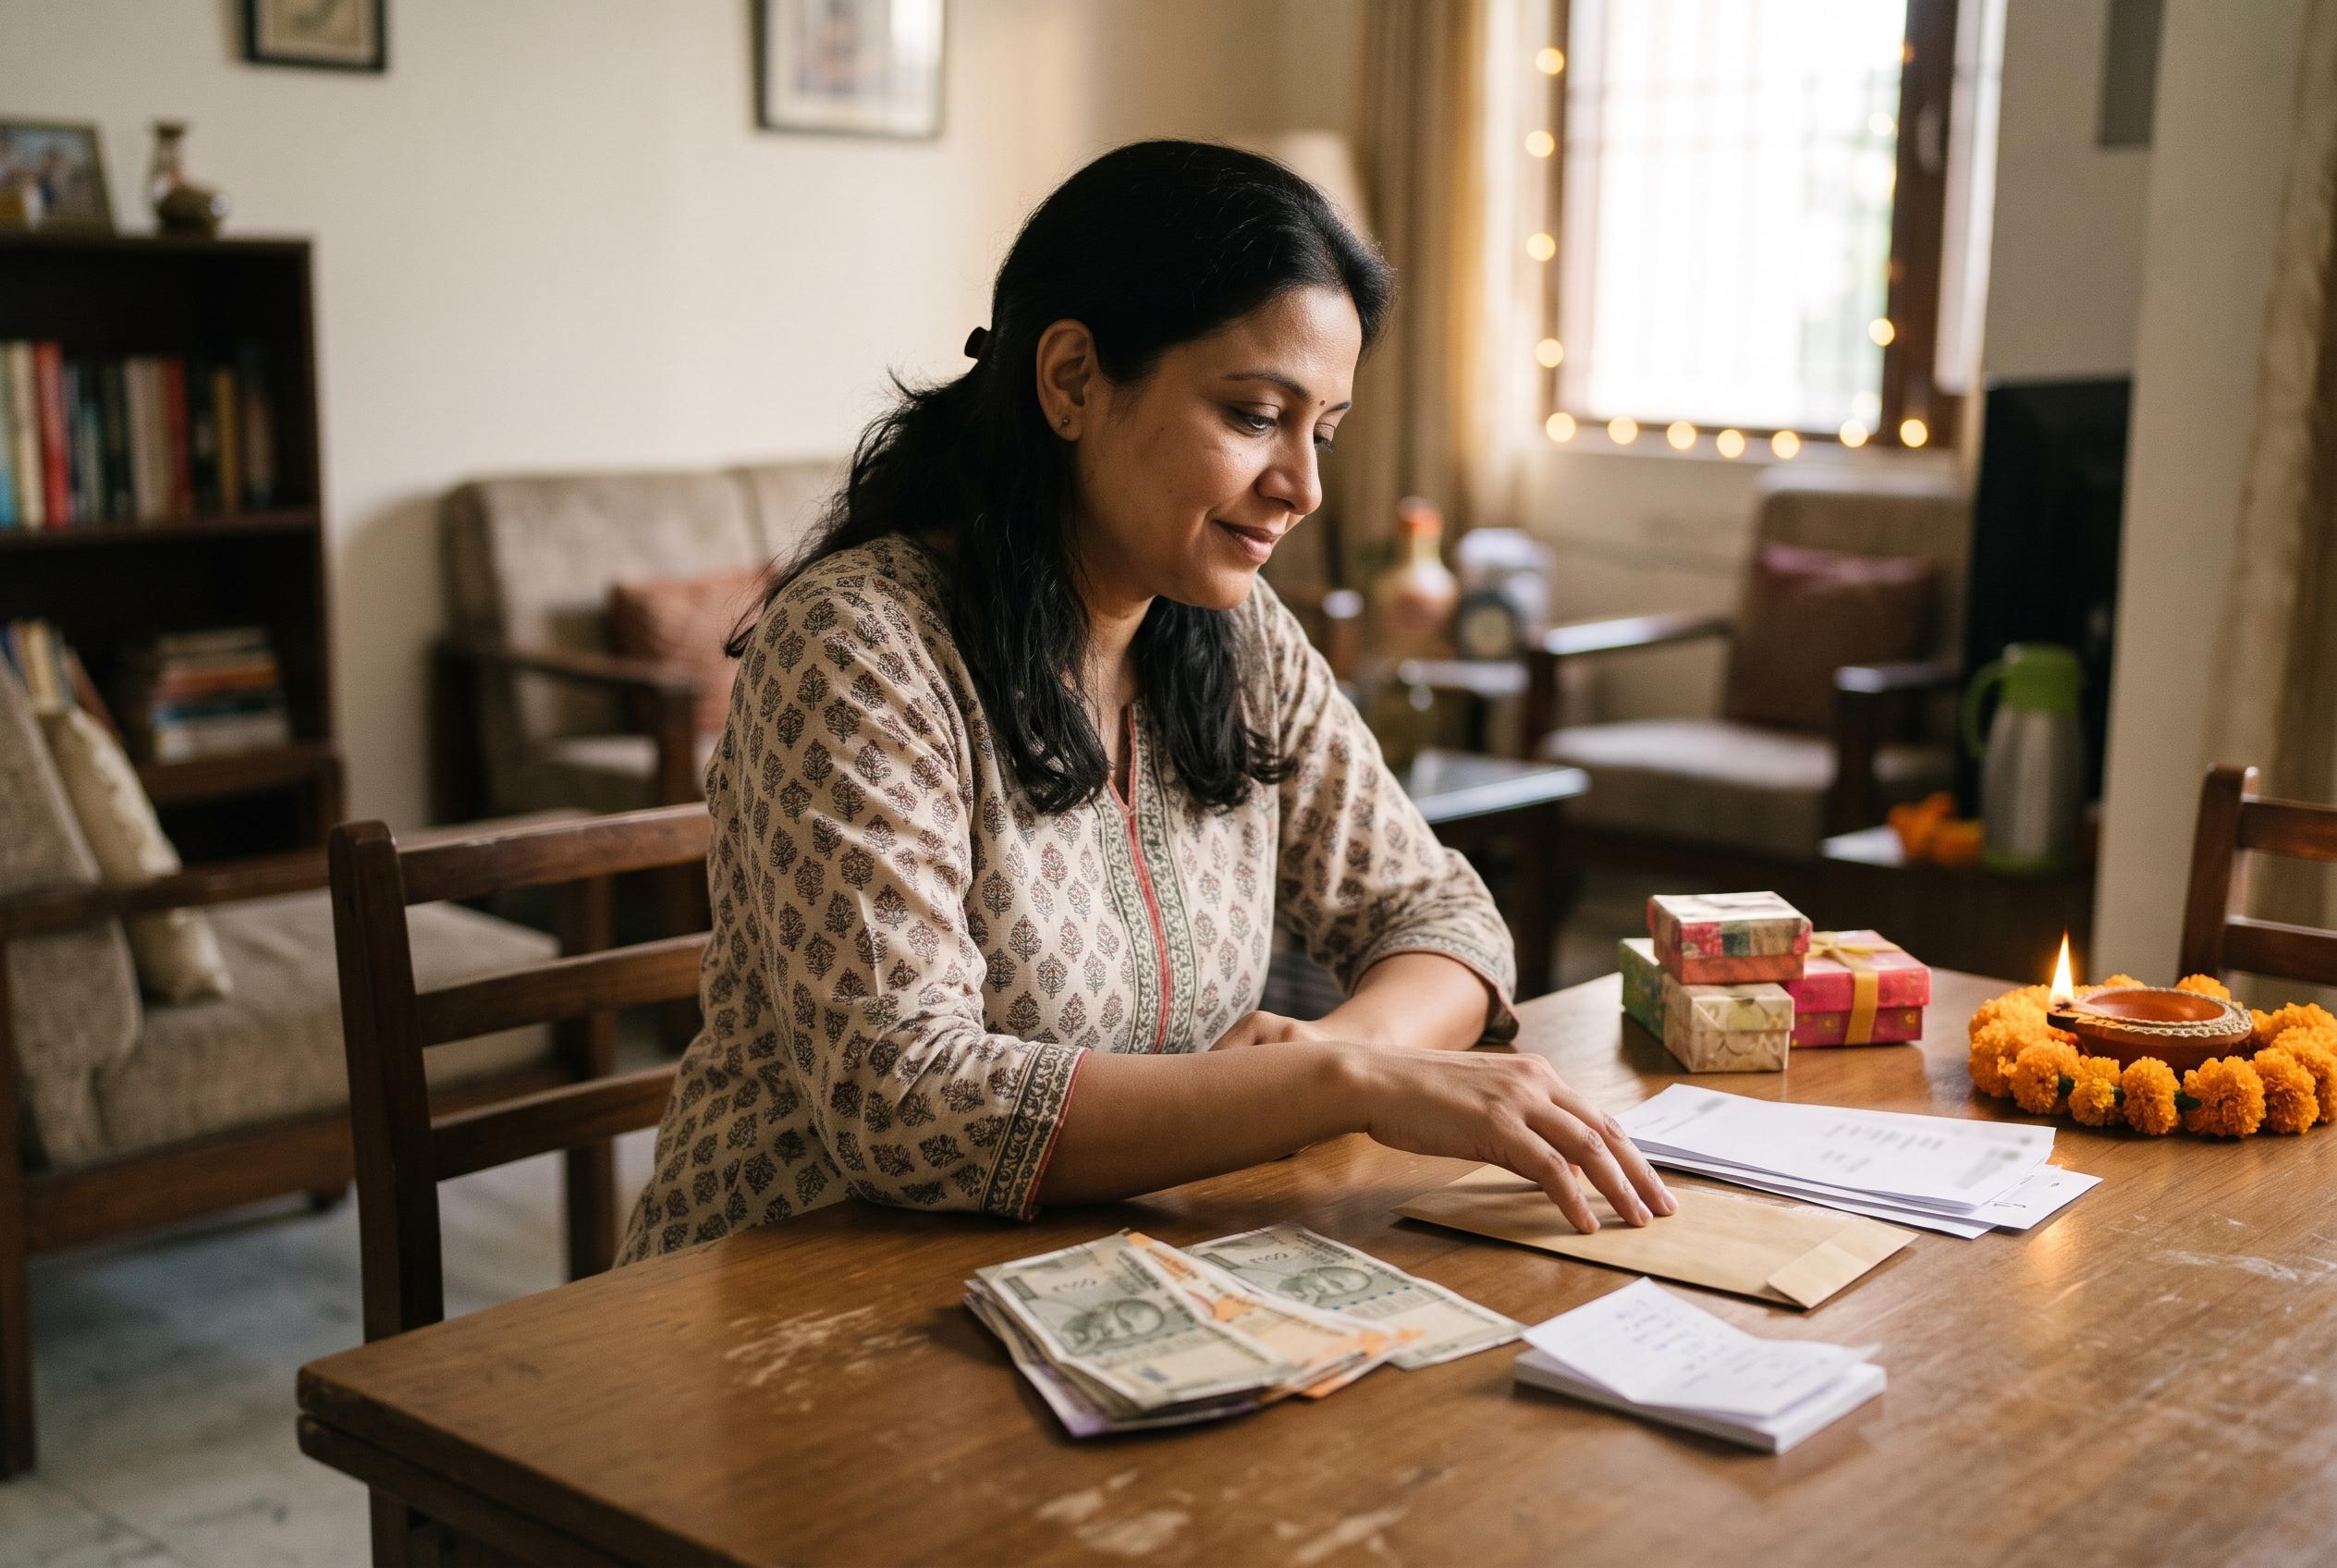

Experts recommend splitting a festive windfall between emergency savings, high-interest debt, long-term goals and predictable bills, while leaving room to celebrate.
A Diwali bonus can feel like a welcome windfall, but financial experts say the smartest move is usually to treat it as a planning opportunity rather than a licence to overspend. Instead of letting the money disappear into short-lived festive purchases, a more balanced approach is to divide it between celebration, savings and longer-term priorities. That is especially important when households may already be juggling rising costs, loan repayments and seasonal bills.
One of the first places to direct part of the bonus is an emergency fund. The Consumer Financial Protection Bureau says emergency savings are meant to cover unplanned costs such as medical bills, car repairs or a sudden loss of income, while FINRA recommends aiming for roughly three to six months of essential expenses if possible. Even if that target feels ambitious, saving something is better than saving nothing, and the money should be kept in a safe, easy-to-reach account rather than tied up in a product that is difficult to access quickly.
Another sensible use is to pay down expensive debt. Investor.gov warns that credit card balances can become costly very quickly, especially when interest charges are left to compound. If a household has more than one debt, the guidance suggests concentrating extra payments on the highest-rate balance while still keeping up with minimum payments elsewhere. For borrowers with personal loans, it is also worth checking for prepayment fees before making an early repayment.
Once short-term vulnerabilities are under better control, the bonus can be put to work for longer-range goals. The U.S. government’s Investor.gov says people should think about their time horizon, risk tolerance and the mix of assets they hold before investing. That could mean adding to retirement savings, building a home deposit or putting money into diversified funds, which spread risk across different holdings. The key point is to match the investment to the goal rather than chasing returns without a clear plan.
It is also wise to reserve part of the bonus for expenses that are already on the calendar. The Consumer Financial Protection Bureau says a realistic budget should include less frequent but predictable costs such as insurance premiums, tuition, school expenses, gifts and family support. Setting aside money for these commitments now can help households avoid relying on credit later, which can make the months after Diwali less financially stressful.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



