

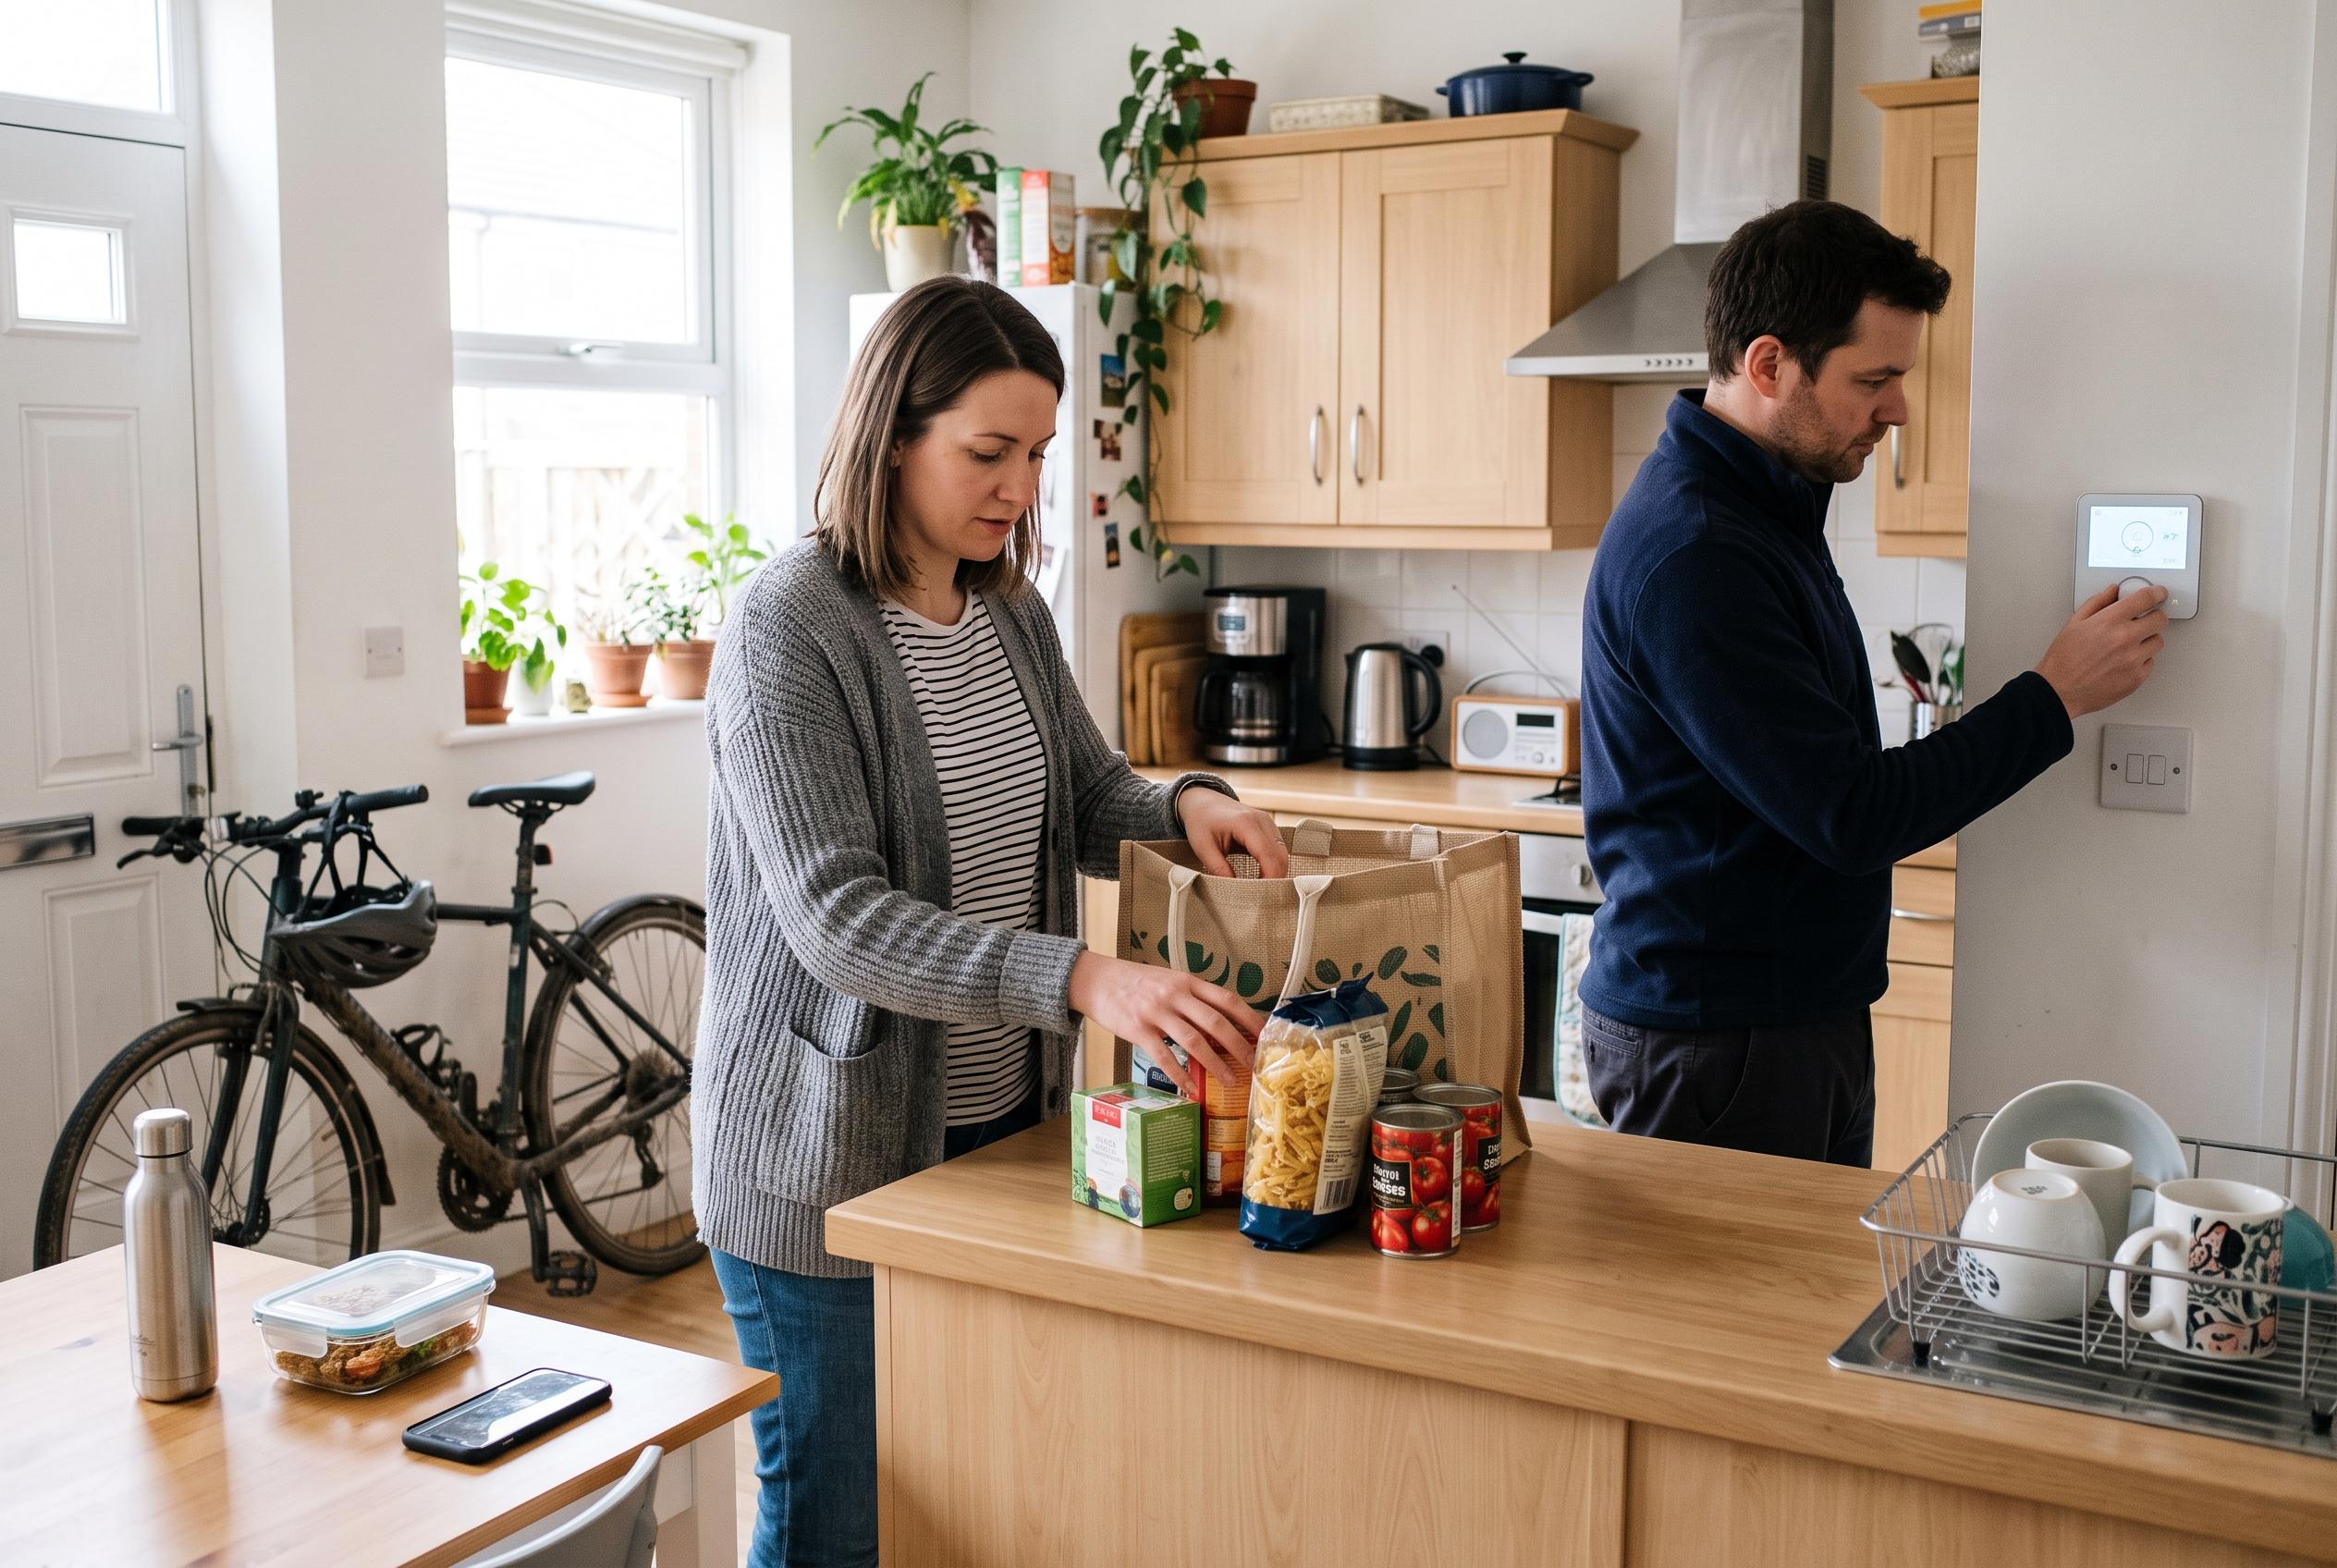

Small, consistent money habits focused on transport, food, energy, and subscriptions can help families stabilise their budgets more effectively than major sacrifices, according to experts and recent initiatives like the UK summer savings scheme.
Small, everyday money habits can do more to steady a family budget than dramatic cutbacks ever will. With food, energy, transport, childcare and leisure all competing for attention, households often need practical routines rather than one-off sacrifices. The most effective changes are usually the ones that can be repeated week after week, gradually easing pressure and creating a little more breathing room by the end of the month.
One of the most useful places to start is with transport, which remains a major expense for many families. Comparing insurance, fuel consumption, maintenance costs and lease deals can uncover savings that are easy to miss. The UK government has also been trying to soften the cost of family travel, saying its Great British Summer Savings Scheme delivered more than 14.5 million free bus journeys for children aged five to 15 in England during the school holidays. That initiative was designed to make days out more affordable while ministers continue a wider push to reshape bus services, including a planned £2 fare cap from January next year.
Budgeting remains the central discipline behind better household finances, but experts say it works best when it is realistic rather than punishing. MoneyHelper, Nationwide and Barclays all recommend starting with take-home income, then listing fixed bills, regular spending and savings or debt repayments before reviewing the numbers each month. Methodwise advises families to include annual or irregular costs such as birthdays, uniforms, servicing and holidays by converting them into monthly amounts, so they do not arrive as unwelcome shocks. Some budgeting guides also point to simple frameworks such as the 50/30/20 rule, which divides after-tax income between needs, wants and savings or debt.
Food spending is another area where modest changes can add up quickly. Planning meals around what is already in the cupboard, fridge and freezer can reduce duplicate purchases and impulse buying, while shopping with a list makes it easier to stick to essentials. Batch cooking, using leftovers for lunches and freezing extra portions can also cut waste and reduce reliance on costly convenience food. For many households, this is one of the easiest ways to trim costs without feeling deprived.
Energy use offers similar opportunities for savings. Turning off lights, washing at lower temperatures and running dishwashers or washing machines only when full can all make a difference over time. Draught-proofing, using thicker curtains and nudging the thermostat down a little may help keep heating bills under control, especially in colder months. Encouraging children to switch off devices rather than leaving them on standby can also turn savings into a shared household habit.
Another regular source of hidden spending is subscriptions and direct debits. Streaming services, apps, magazines, gym memberships and subscription boxes often continue long after the novelty has worn off, which makes periodic checks worthwhile. Families can also save by shopping around before renewing insurance, broadband, mobile phone or utility contracts, since loyalty does not always lead to the best price. Setting reminders before renewal dates can help households avoid drifting on to expensive standard rates.
Second-hand buying can be a sensible and practical option, particularly for families with growing children. Clothes, toys, books, bikes and furniture are often available in good condition through charity shops, local selling groups, school fairs and online marketplaces. Selling items no longer needed can bring in extra cash as well as clear space at home. That approach can also help children understand that used does not mean lesser value.
Building an emergency fund is another habit that can protect a family from sudden disruption. A broken appliance, urgent repair, vet bill or school trip can quickly upset even a carefully planned budget. Saving a small, regular amount into a separate account can create a useful buffer over time, especially if the transfer is automated. Even modest contributions can make unexpected costs feel far more manageable.
The broader lesson is that family finances often improve through consistency rather than sacrifice alone. Involving children can help too, whether that means switching off lights, wasting less food or saving towards a shared goal. When budgeting, shopping and spending become family routines rather than sources of conflict, the result is not only lower costs but often less stress and greater control.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



