

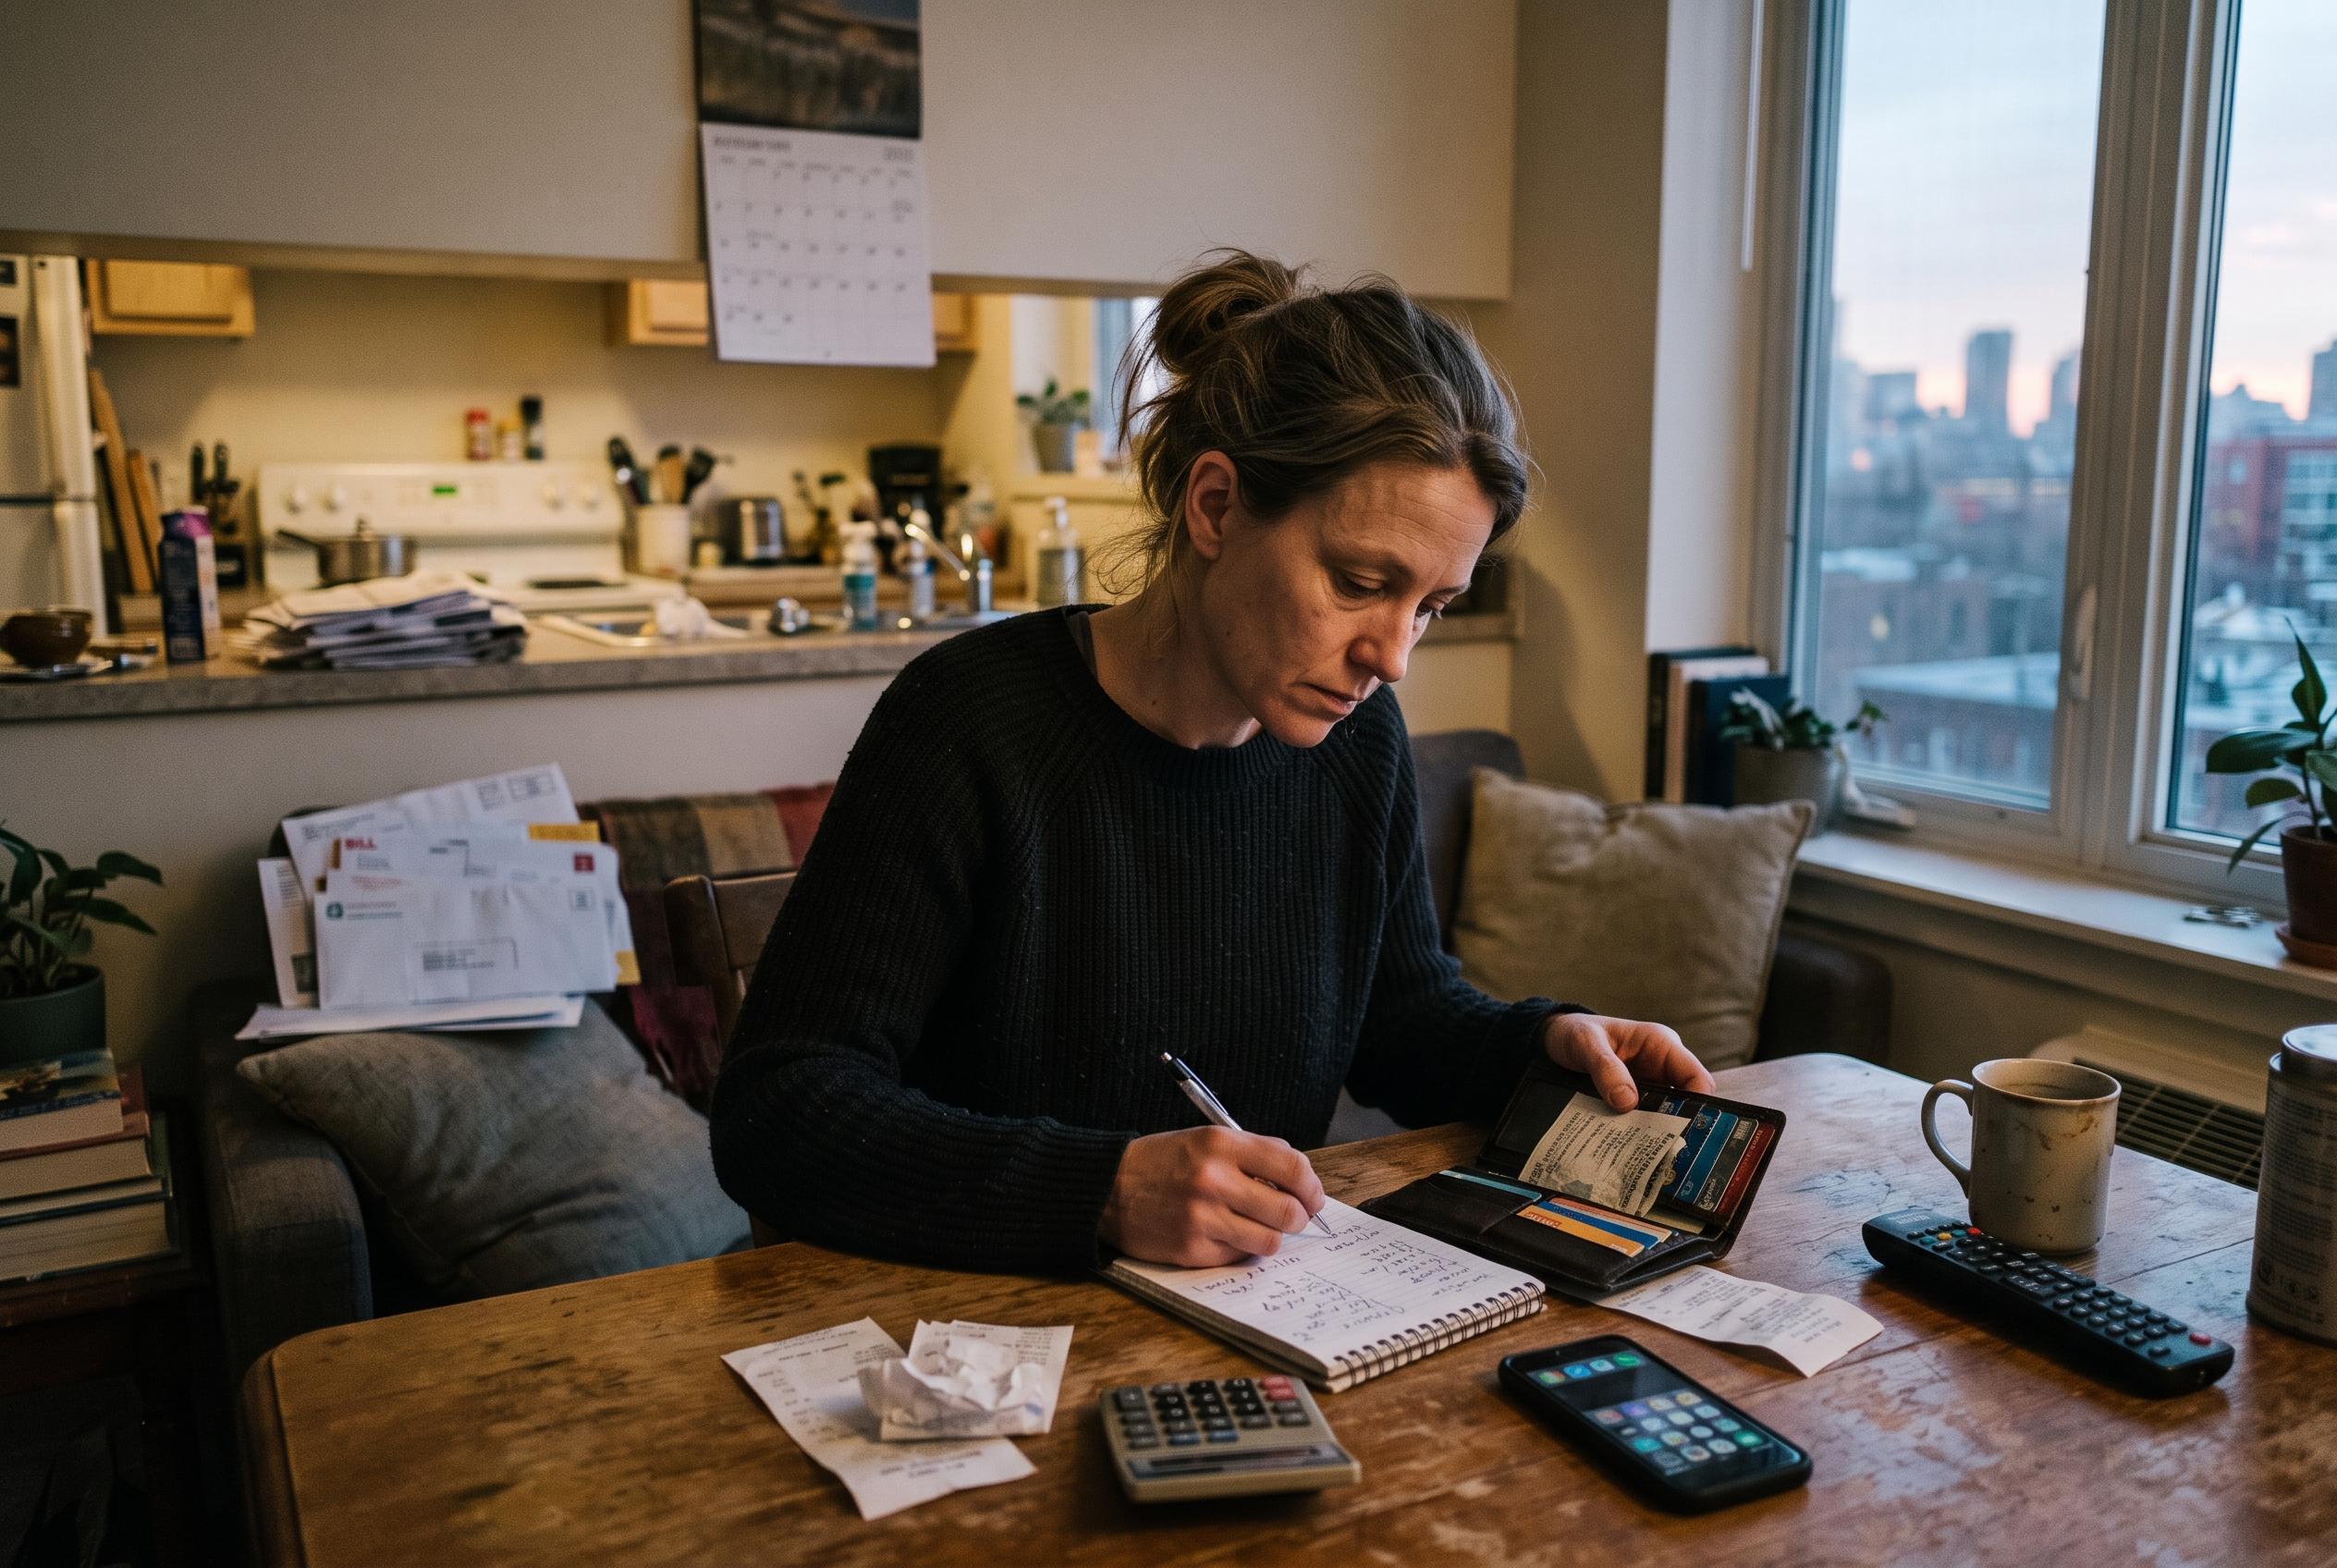

Uncover how everyday financial decisions, like misjudging credit, subscriptions, and budgeting, contribute to growing household stress and debt, highlighting practical strategies for sustainable money management.
Money stress rarely starts with a single crisis. More often, it builds from ordinary habits that seem harmless in isolation but steadily tighten a household’s room to breathe. According to the lead article, the problem is not always reckless spending; it is often the slow accumulation of small decisions that make cash flow harder to manage and debt harder to escape.
One of the most common traps is treating unused credit as if it were the same as money in the bank. NerdWallet explains that credit cards are revolving borrowing tools, not spending power that belongs to the cardholder, and that balances can become costly once interest is added. The risk is not only financial but psychological: when people mentally count available credit as part of their safety net, they can misjudge what they can truly afford.
Subscriptions create a similar illusion. Each individual charge may look insignificant, but the total can quietly drain a budget month after month. Kiplinger has recently described a broader trend in so-called “moneymaxxing”, in which people scrutinise every dollar for value, including cancelling unused services. That approach can help, but the article also warns that chasing small savings should not become its own source of stress. The useful middle ground is not eliminating every convenience, but regularly checking which recurring charges still earn their place.
Another source of strain is budgeting for an idealised version of life rather than the one that actually exists. A plan that assumes perfect lunches, no car repairs and no social spending is likely to collapse the first time reality intrudes. The clearest budgets, according to the article, leave room for birthdays, repairs, annual fees and the occasional bad day, because a budget that cannot absorb ordinary life tends to be abandoned rather than adjusted.
That point becomes even more important when annual costs are involved. Insurance bills, registration fees, holiday spending and home maintenance do not arrive every month, which makes them easy to ignore until they create a cash squeeze. The practical answer is to divide known yearly expenses across 12 months and save incrementally. Kiplinger’s guidance on personal finance makes a related point elsewhere: the cheapest-looking option is not always the least expensive over time, especially when it wears out quickly or creates extra hassle. Planning for predictable irregular costs can be far cheaper than scrambling to cover them later.
Perhaps the most damaging habit is protecting every other line item before savings. When budgets feel tight, it is tempting to cut retirement contributions or raid emergency funds first. That may solve a short-term problem, but it leaves less protection for the next one. Equally costly is avoiding the numbers altogether. Looking away from account balances, bills and card statements may feel easier in the moment, yet it allows overdrafts, late fees and growing debt to do their work unnoticed. A brief, regular review is often enough to catch a problem before it grows into a bigger one.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



