

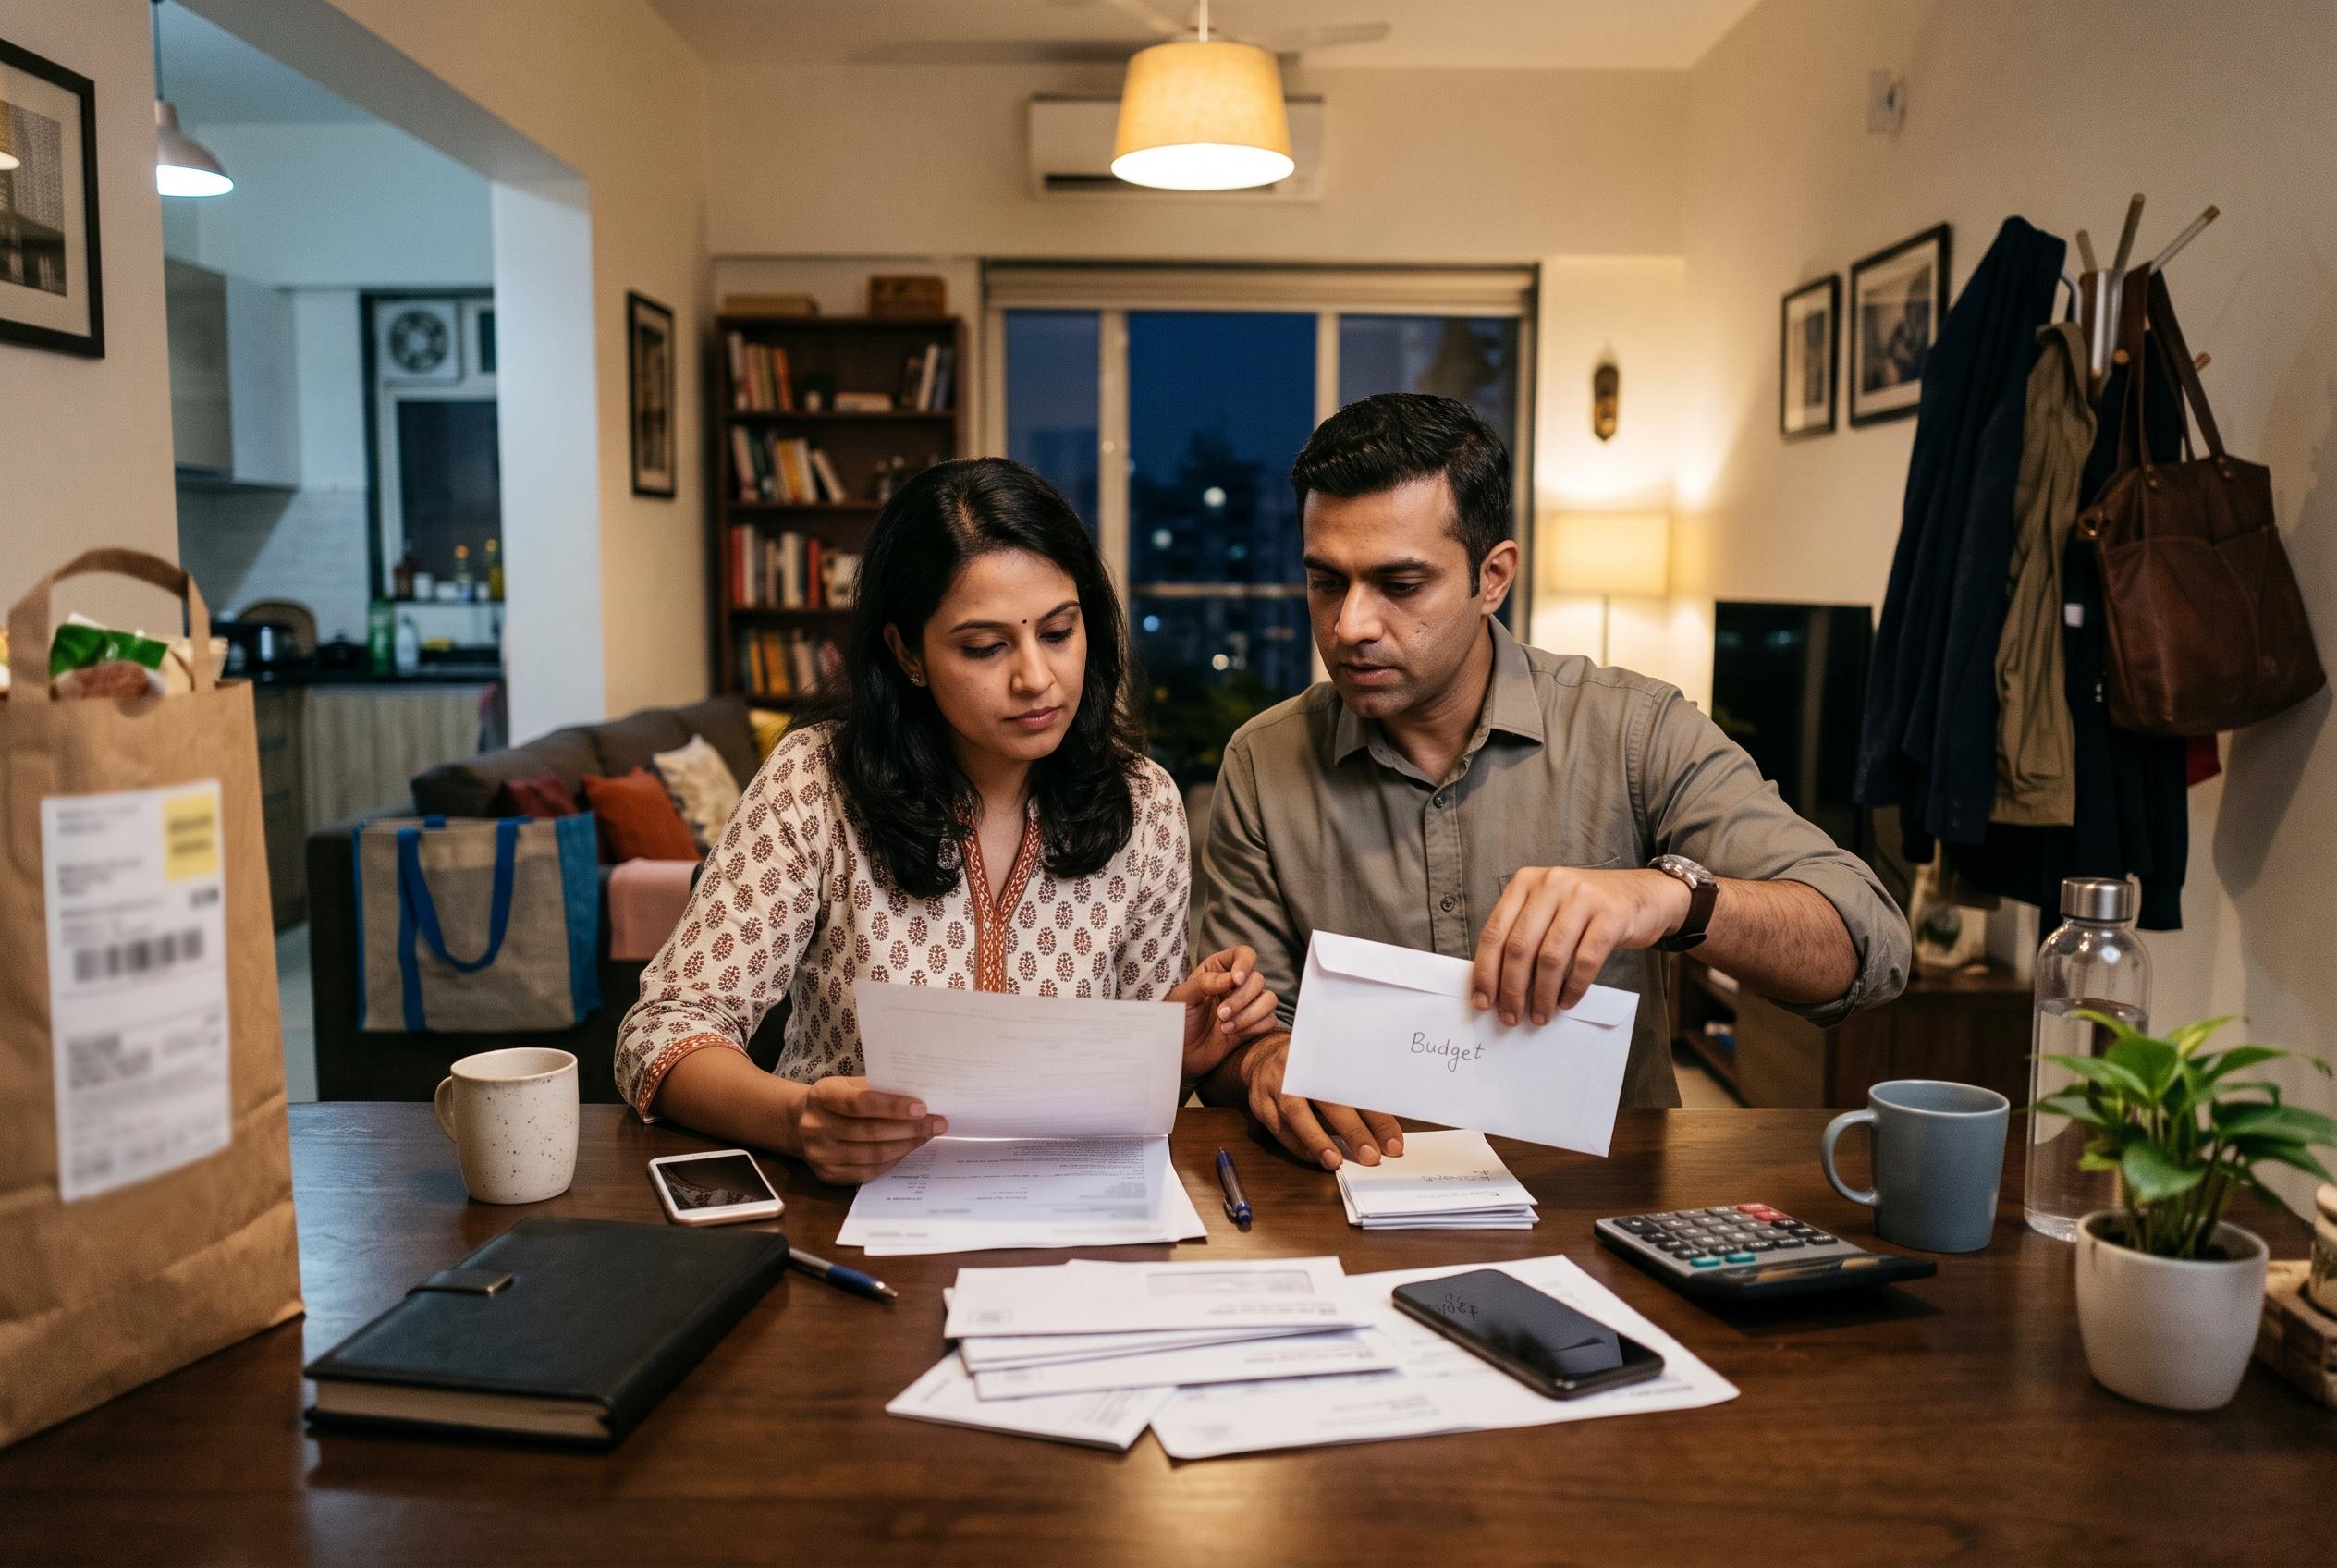

Many middle-class Indian couples earning double incomes are finding it difficult to manage their finances, as lifestyle inflation, poor coordination, and credit dependence undermine their financial stability, prompting calls for disciplined spending and joint planning.
In India’s large cities, many dual-income households are discovering that a bigger pay packet does not always translate into financial breathing room. Two salaries can still disappear before month-end, leaving couples puzzled about where the money went and why credit card statements feel so punishing. Financial advisers say the problem is less about insufficient earnings than about weak coordination, loose spending habits and a failure to set clear money goals together.
One of the biggest fault lines is the absence of a shared plan. Couples often split bills informally, with one partner covering rent or utilities and the other taking on groceries or dining out, but without agreeing on how much they should save each month or what they are saving for. That gap matters because long-term aims such as buying a home, building a retirement corpus or funding children’s education can be pushed aside when day-to-day spending is left to drift. Kiplinger has described this pattern as the high-earning trap, in which rising income is absorbed by rising expenses unless households deliberately cap fixed costs and automate saving.
Another force is lifestyle inflation. As salaries climb, spending often rises just as quickly, particularly in metros where restaurants, gadgets, branded clothing and aspirational holidays are easy to normalise. Social media intensifies that pressure by turning other people’s lifestyles into a benchmark. Moneycontrol reported that a 2024 YouGov survey found 64% of Indian millennials and Gen Z respondents admitted to impulse purchases triggered by social media posts, a sign that online comparison is now influencing real-world finances. The result is not always a dramatic spending spree; more often it is a steady drift into higher monthly outgo that quietly erodes savings.
Credit is making that drift easier to sustain. NDTV has reported that many young urban Indians are not being undone by a single large loan but by a stack of small EMIs and card payments that gradually consume cash flow. Once salaries are absorbed by repayments, households are forced to lean on credit again for routine expenses, creating a cycle that is difficult to break. Analysts also warn that many dual-income couples overestimate their resilience and neglect emergency reserves. Without a fund covering several months of expenses, even a short spell of joblessness or a medical crisis can push families into costly borrowing or force them to sell investments at the wrong time.
The damage is compounded when tax planning and disciplined investing are left until the end of the financial year. India.com has noted that even well-paid professionals can end up with little disposable income when spending rises faster than earnings, while a study on middle-income households found that inflation itself also reshapes spending patterns and squeezes budgets. The practical answer is not complicated, though it does require consistency: couples need a transparent joint budget, a clear split between household and personal spending, regular reviews, and an automatic transfer into savings and investments. A simple framework such as the 50:30:20 rule, with necessities, lifestyle spending and savings kept separate, can help make sure that higher income turns into lasting financial stability rather than a more expensive version of the same month-to-month scramble.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



