

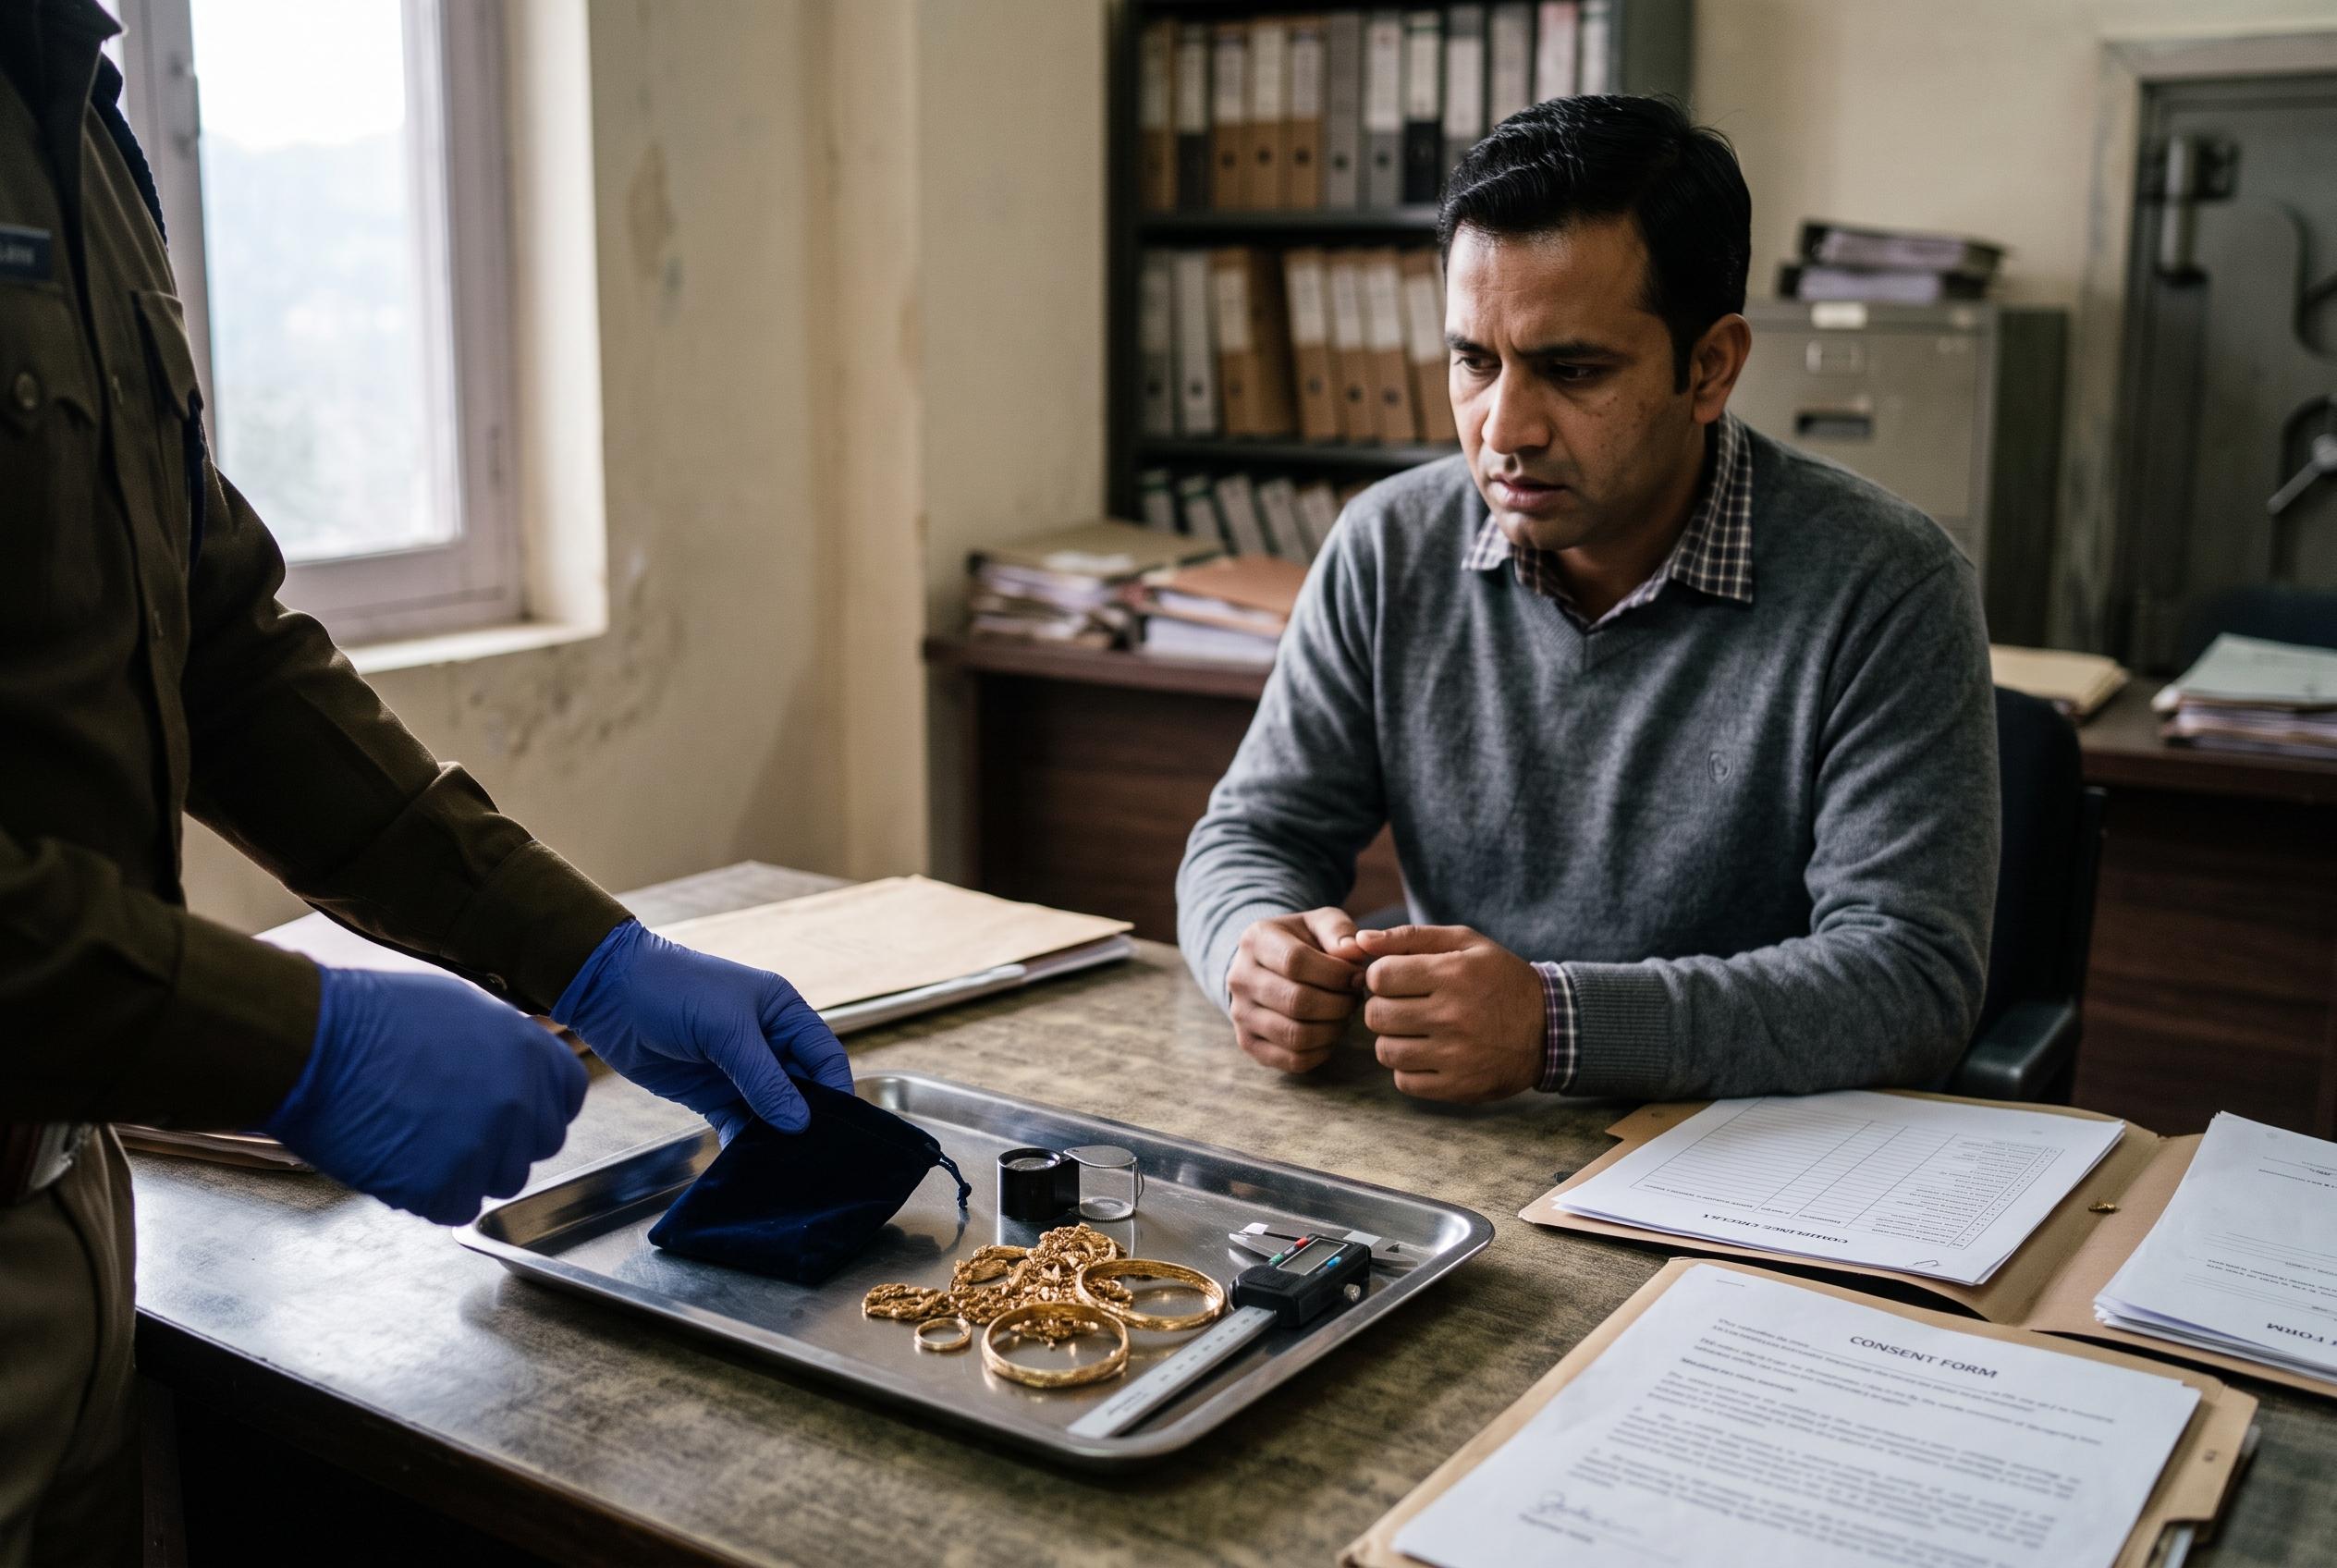

A Shimla-based consumer commission has held a private bank accountable for misleading practices after an unauthorised surprise verification of pledged gold found the items to be fake, highlighting new RBI guidelines on transparency and borrower consent in gold loans.
A consumer commission in Shimla has held a private bank liable for deficiency in service and unfair trade practice after it told a borrower that his pledged gold was “spurious” following an internal audit that the customer said he had never been told about.
The Shimla District Consumer Disputes Redressal Commission ordered the bank to pay the market value of 103 grams of 22-carat gold, along with compensation and litigation costs, after finding that the lender had not shown that the surprise verification was carried out with the borrower’s consent or prior notice. According to the commission, the bank also failed to prove that its loan documents clearly allowed such checks in the customer’s absence. Industry summaries of the Reserve Bank of India’s gold-loan framework say lenders must now build borrower consent for surprise verification into the loan agreement and communicate that clause at the time of sanction.
The dispute arose after the borrower took three loans against gold jewellery in 2022 and 2023, with the bank repeatedly accepting the ornaments as security before later informing him that a subsequent verification had found the pledged items to be entirely fake. The borrower rejected that conclusion and argued that any later inspection had been done behind his back, warning that the jewellery may have been tampered with or swapped. The bank, by contrast, said its empanelled assayer had found the items to be 100% spurious and blamed the original valuer, even saying it had filed a police complaint against that person.
In its September 23 order, the commission said the customer could not be blamed for an impurity finding made without his knowledge and noted that the same jewellery had already been accepted on earlier occasions. The bench also pointed to the RBI’s gold-and-silver lending directions, which industry summaries say were issued in June 2025 to standardise loan conditions, disclosure requirements and collateral management across regulated lenders. Those summaries add that the rules are meant to tighten transparency and accountability in a segment where valuation, storage and disclosure are central to borrower protection.
The ruling also fits a wider regulatory shift. According to later industry guidance on the RBI’s supervisory approach, valuation of pledged gold should be done in the borrower’s presence, with a copy of the valuation record given to the customer, and lenders remain responsible even when they outsource the work. Separate 2026 guidance on digital KYC says identity checks may now be completed through digital channels, but physical gold verification and pledging still have to follow branch-level or authorised operational procedures.
For borrowers, the case underlines the importance of reading gold-loan terms carefully, checking that the pledged items are described and valued in writing, and ensuring that any consent for later inspections is clearly set out. It also reinforces the commission’s view that a lender cannot simply shift responsibility to the customer after an undisclosed verification uncovers a problem with collateral already accepted several times before.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



