

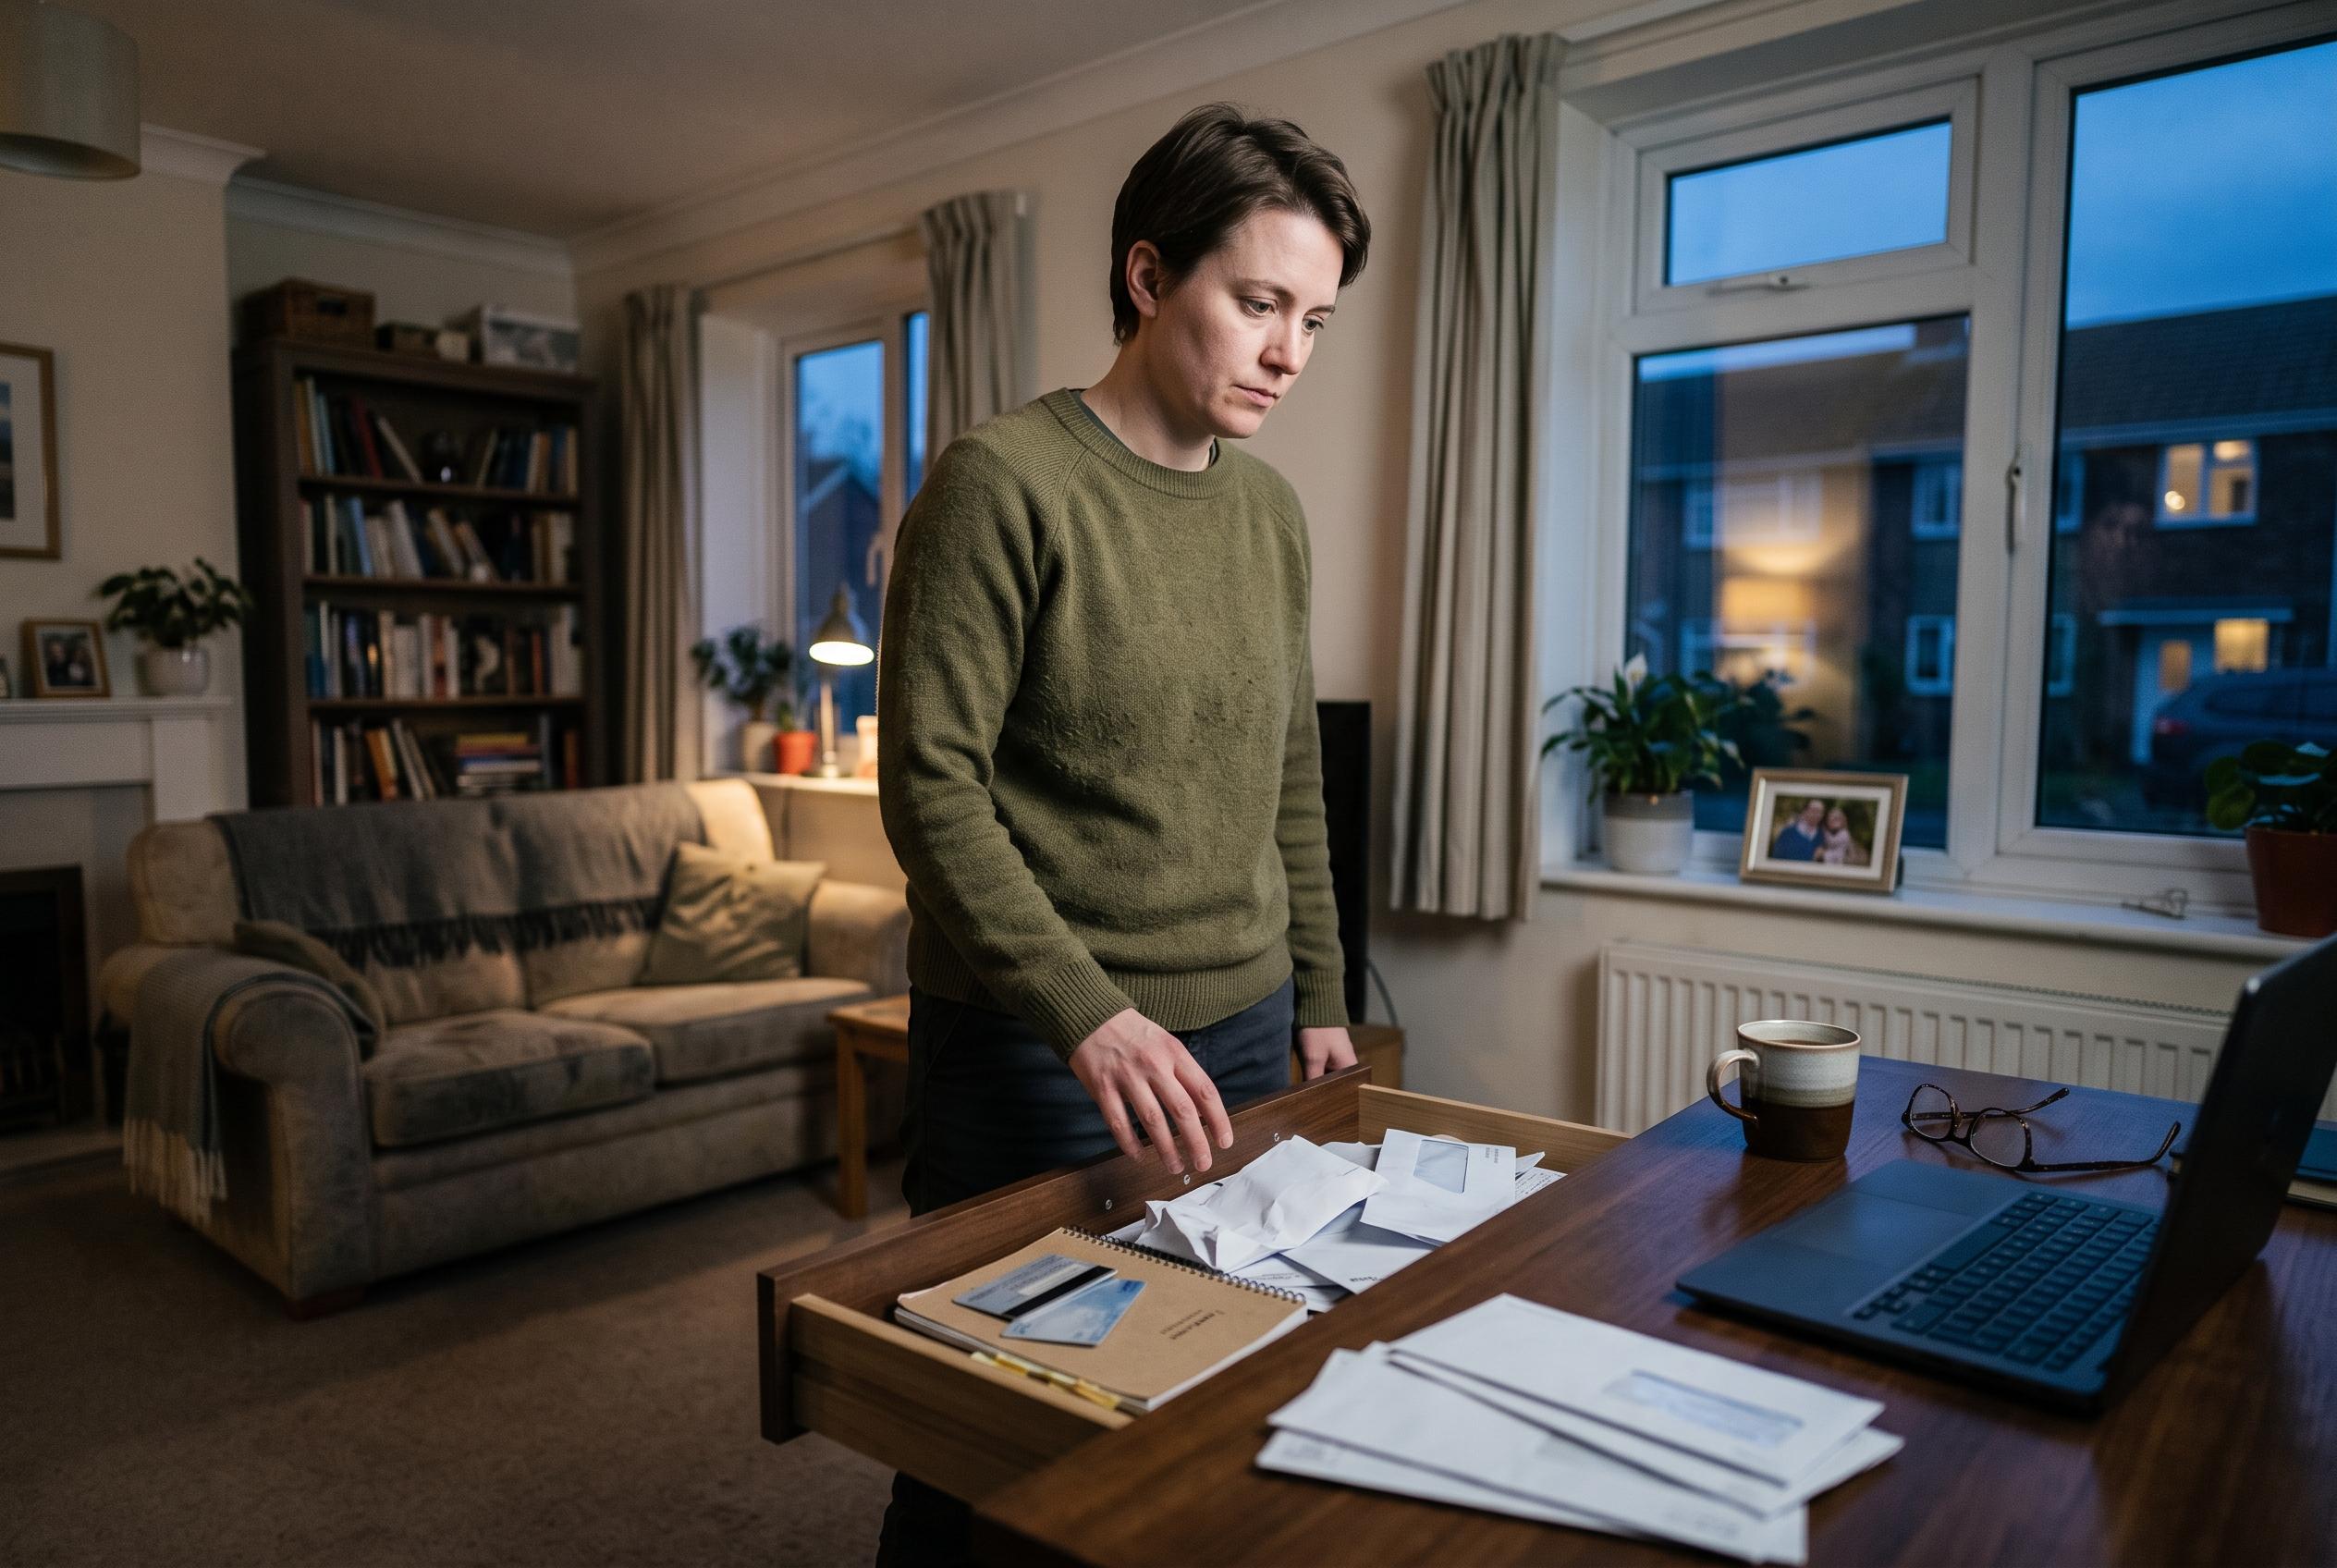

Early exposure to household financial stress can shape adult behaviours such as compulsive checking, self-guilt, secrecy, and avoidance, with some patterns rooted in childhood anxieties that outlive the original circumstances.
Children who grow up around constant money worry often carry that feeling into adulthood, even when their own finances are no longer precarious. Style Girlfriend says the anxiety can be absorbed from the atmosphere of a household as much as from any explicit lesson: a tense pause at the checkout, a parent quietly counting bills, or an argument that seems bigger than the numbers on the page. The result, the article argues, is a set of habits that can linger long after the childhood circumstances have changed.
One common pattern is compulsive checking. Some adults open their banking app before buying a sandwich or a coffee, not because they lack discipline but because uncertainty itself feels intolerable. Financial psychology research describes this as money vigilance, one of several “money scripts” people absorb early in life. Simply Psychology notes that these scripts are often formed in childhood and can shape behaviour more strongly than income alone, while the academic paper shared in the source material describes how repeated exposure to financial fear can produce either hyper-control or avoidance later on.
That same background often breeds guilt around self-spending. People may happily pay for a friend’s dinner, a child’s activity, or a family repair, but hesitate over a coat, a haircut, or a modest treat for themselves. Style Girlfriend links that pattern to the belief that spending on oneself is indulgent. The broader psychology literature in the supplied sources supports that view, describing how shame and fear can make even routine purchases feel morally loaded rather than simply practical.
The worry can persist even when the numbers are objectively sound. A person may have savings, a stable salary and no credit card debt, yet still spend nights calculating worst-case scenarios. Research cited in the article on family financial stress suggests that children’s perceptions of strain may matter more than the actual figures on a balance sheet, because what shapes memory is not just poverty or plenty, but the emotional climate surrounding money. That helps explain why a bigger pay cheque does not necessarily quiet an older fear.
Another lasting habit is silence. Many adults raised in anxious households avoid discussing money with friends, partners or colleagues, treating it as private and potentially dangerous territory. Style Girlfriend notes that this secrecy can protect people from embarrassment, but it can also leave them isolated with fears that others share. The academic paper in the source set describes a similar pathway: parental silence, conflict or instability can teach children that money is something to hide rather than manage openly.
At the other end of the spectrum are people who avoid looking at their finances altogether. Unopened bills, ignored statements and a banking app buried on a home screen are not always signs of carelessness; they can be forms of self-protection. The avoidance research supplied with the brief refers to the “ostrich effect”, in which people look less often when they expect bad news, even though that usually makes matters worse. In these cases, the fear of confirming a problem becomes more powerful than the cost of leaving it unresolved.
Some adults respond by overcompensating in other directions. They may overspend on visible status items to prove they are no longer struggling, or they may refuse to replace worn-out possessions for far too long. Style Girlfriend describes both behaviours: the impulse to signal that one has “made it”, and the opposite instinct to squeeze every last month out of a cracked phone or damaged shoes. The psychology sources suggest both can come from the same root feeling , that every financial decision is haunted by the possibility of going back to a time when money felt unstable.
Taken together, these habits show how deeply early money experiences can shape adult life. The point is not that everyone raised in a worried household will react the same way, or that caution is always a problem. Some of these tendencies are plainly sensible. But when vigilance becomes fear, when privacy turns into shame, or when avoidance starts to rule ordinary decisions, the childhood lesson has outlived its usefulness.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.



