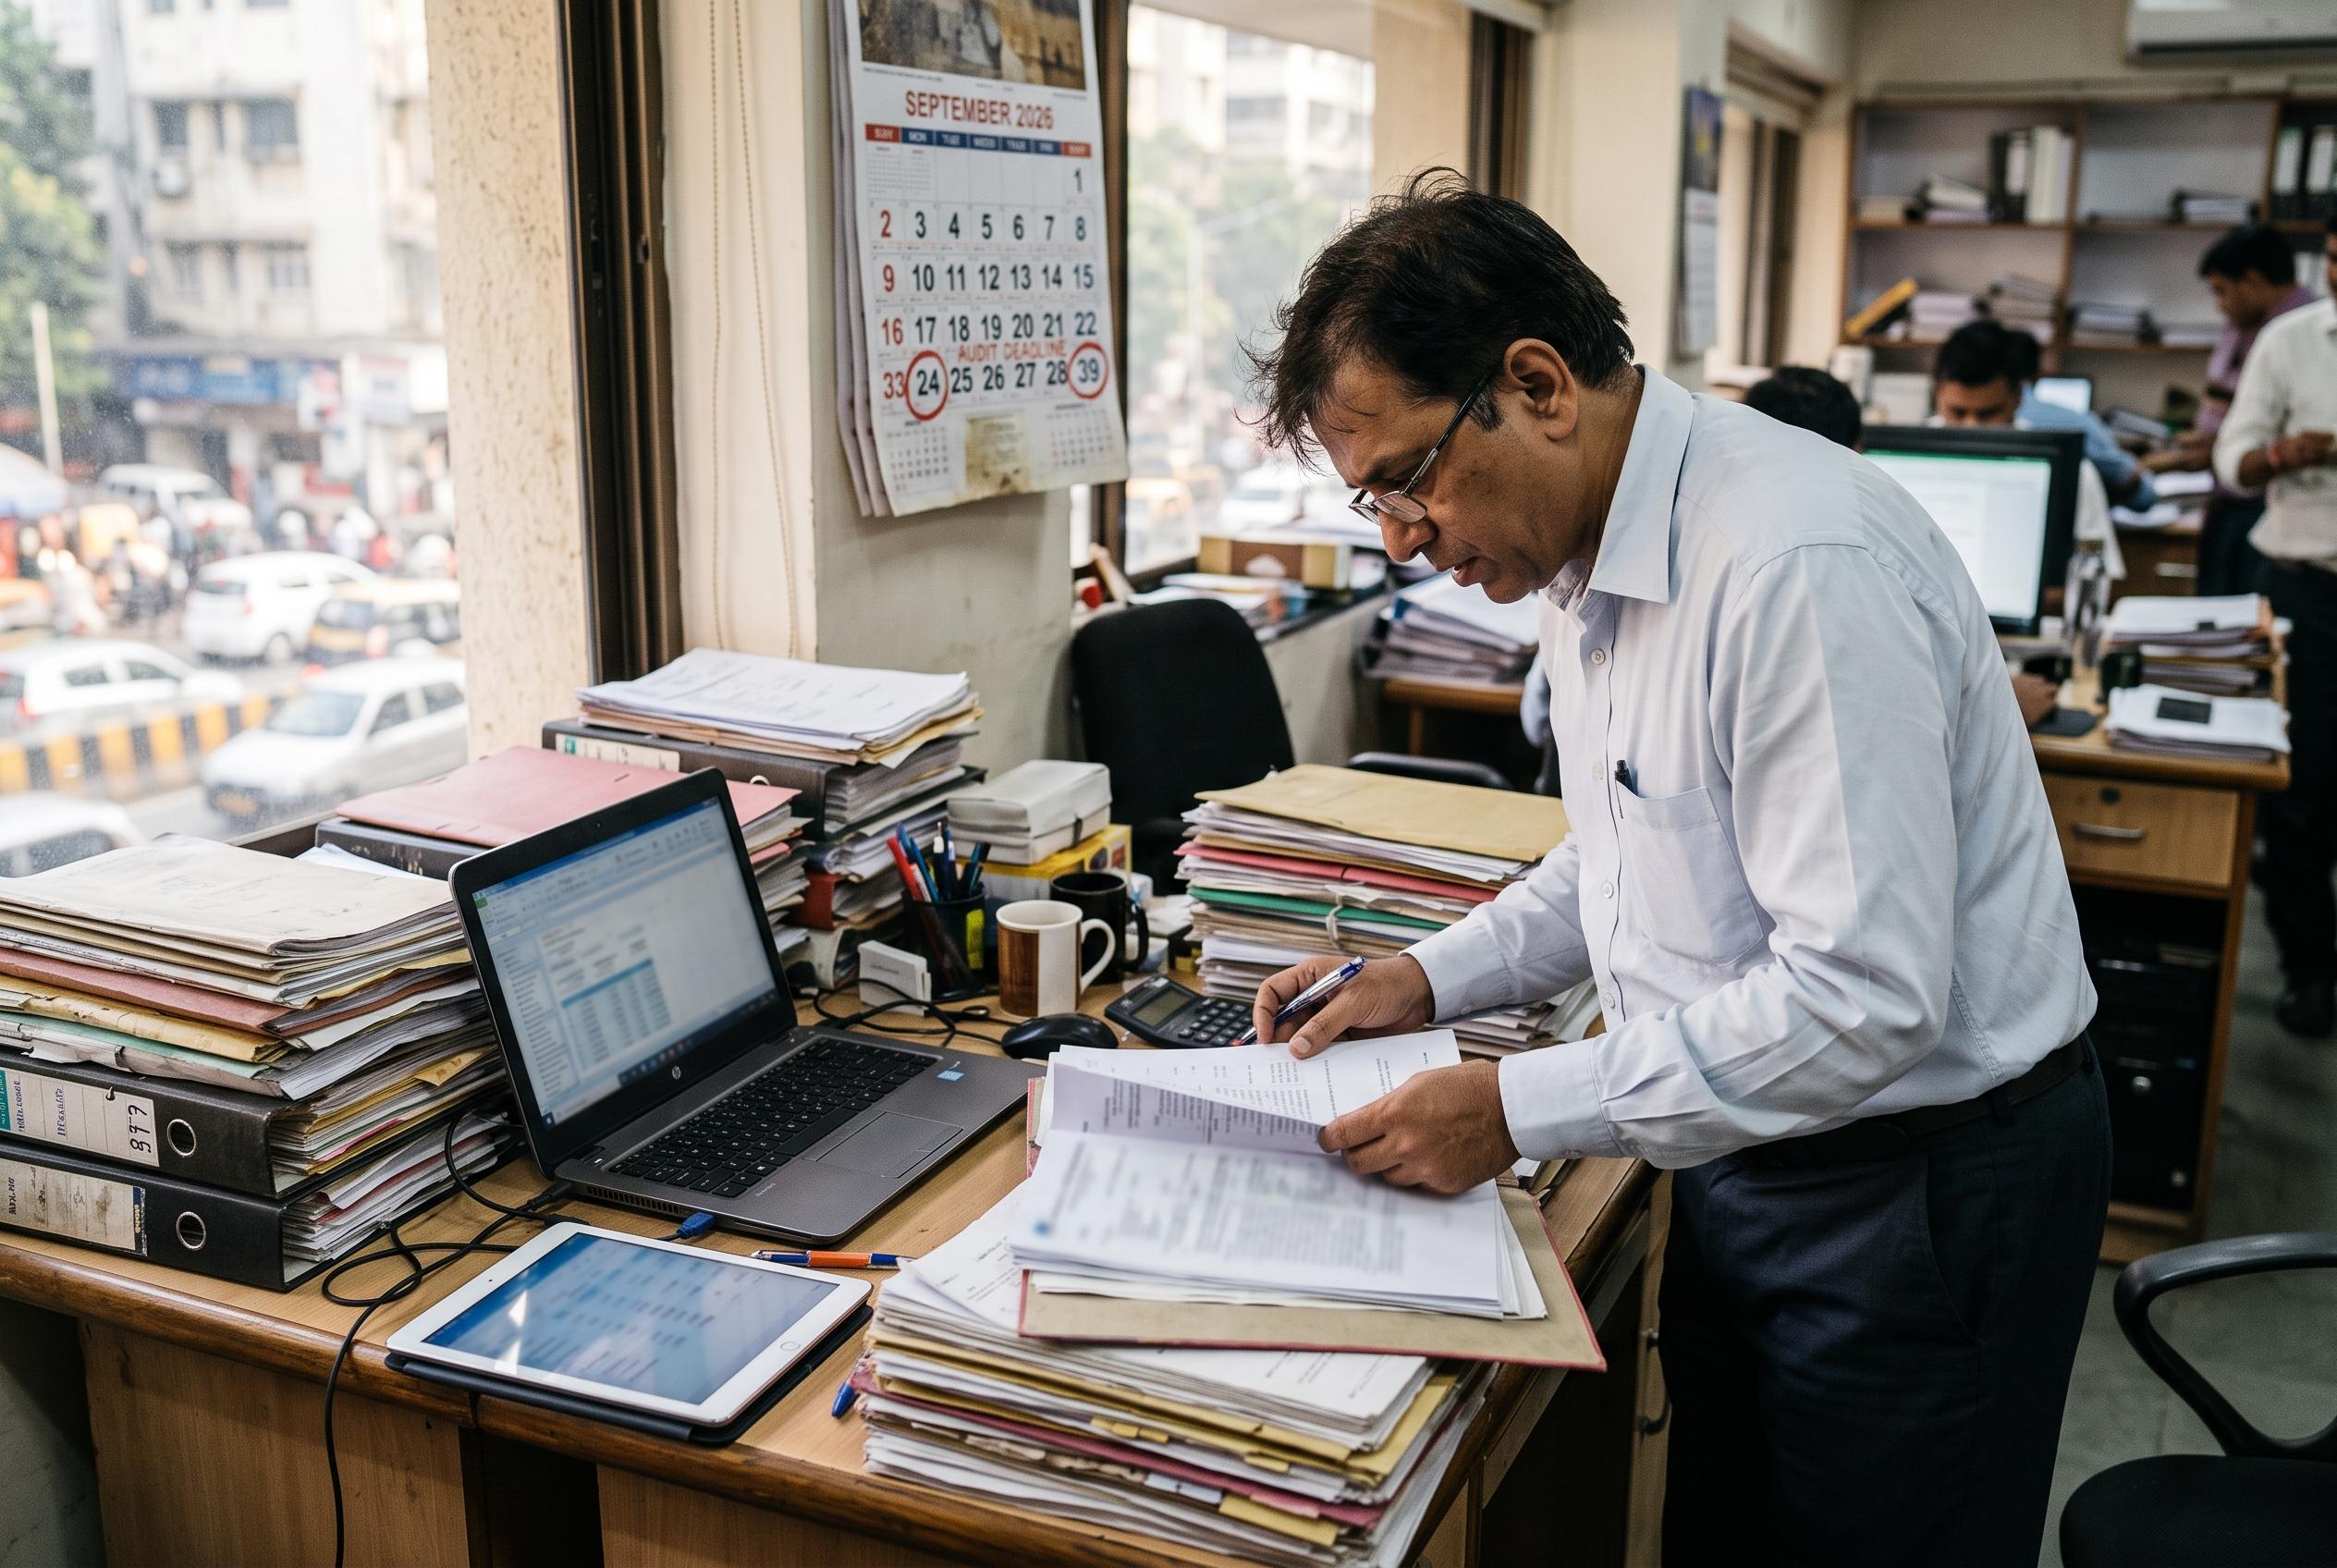

As India’s tax audit deadline looms, chartered accountants navigate last-minute digital hurdles and detailed reporting requirements to ensure compliance before September 30, 2026.
India’s tax audit season is entering its final stretch, with just 12 days left before the September 30, 2026 deadline for Assessment Year 2026-27. For chartered accountants, the immediate challenge is less about the rules themselves than about avoiding last-minute bottlenecks: report uploads can still fail if approvals, signatures or supporting data are not aligned, and the taxpayer must accept the audit report on the portal after filing.
Section 44AB remains the key filter for whether an audit is required. According to guidance from ClearTax, TaxClue, Ravel Consultant and IndeFine, businesses generally face mandatory audit once turnover crosses Rs 1 crore, though the threshold rises to Rs 10 crore when cash receipts and payments remain within 5 per cent. Some smaller businesses can stay outside the audit net by choosing presumptive taxation under Section 44AD, which can apply up to Rs 3 crore under the same cash-condition test. The Income Tax Department’s own text of Section 44AB sets out the legal framework for these obligations.
Once a case is identified, the next step is choosing the right form and clearing the basic particulars. Form 3CA is used where accounts are already audited under another law, while Form 3CB applies in other cases, with Form 3CD carrying the detailed audit disclosures. The practical advice from the CareerIndia checklist is to verify names, PAN, assessment year and clause mapping before drafting, because small mismatches often lead to avoidable revisions and delay the final upload.
The compliance pressure point now is the supporting infrastructure around the report. The checklist highlights the need to generate and secure the Unique Document Identification Number before upload, to make sure the digital signature certificate is active and correctly linked to the PAN, and to remember that reports without a valid UDIN can become invalid after 15 days. It also advises filers to use off-peak hours, including early mornings, late nights and Sunday afternoons, because portal congestion tends to worsen as the deadline approaches.
A one-page red-flag review can save more time than repeated corrections after filing. Particular attention should be paid to MSME-related payment rules under Section 43B(h), statutory dues and year-end cut-offs, TDS and TCS reconciliation against Form 26AS and AIS, depreciation entries, and GST turnover matching against books and returns. Before submission, practitioners are also being urged to freeze a record of the version, timestamp, UDIN and signer, then download acknowledgements and keep a fallback plan ready for payment issues or rejected uploads.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.