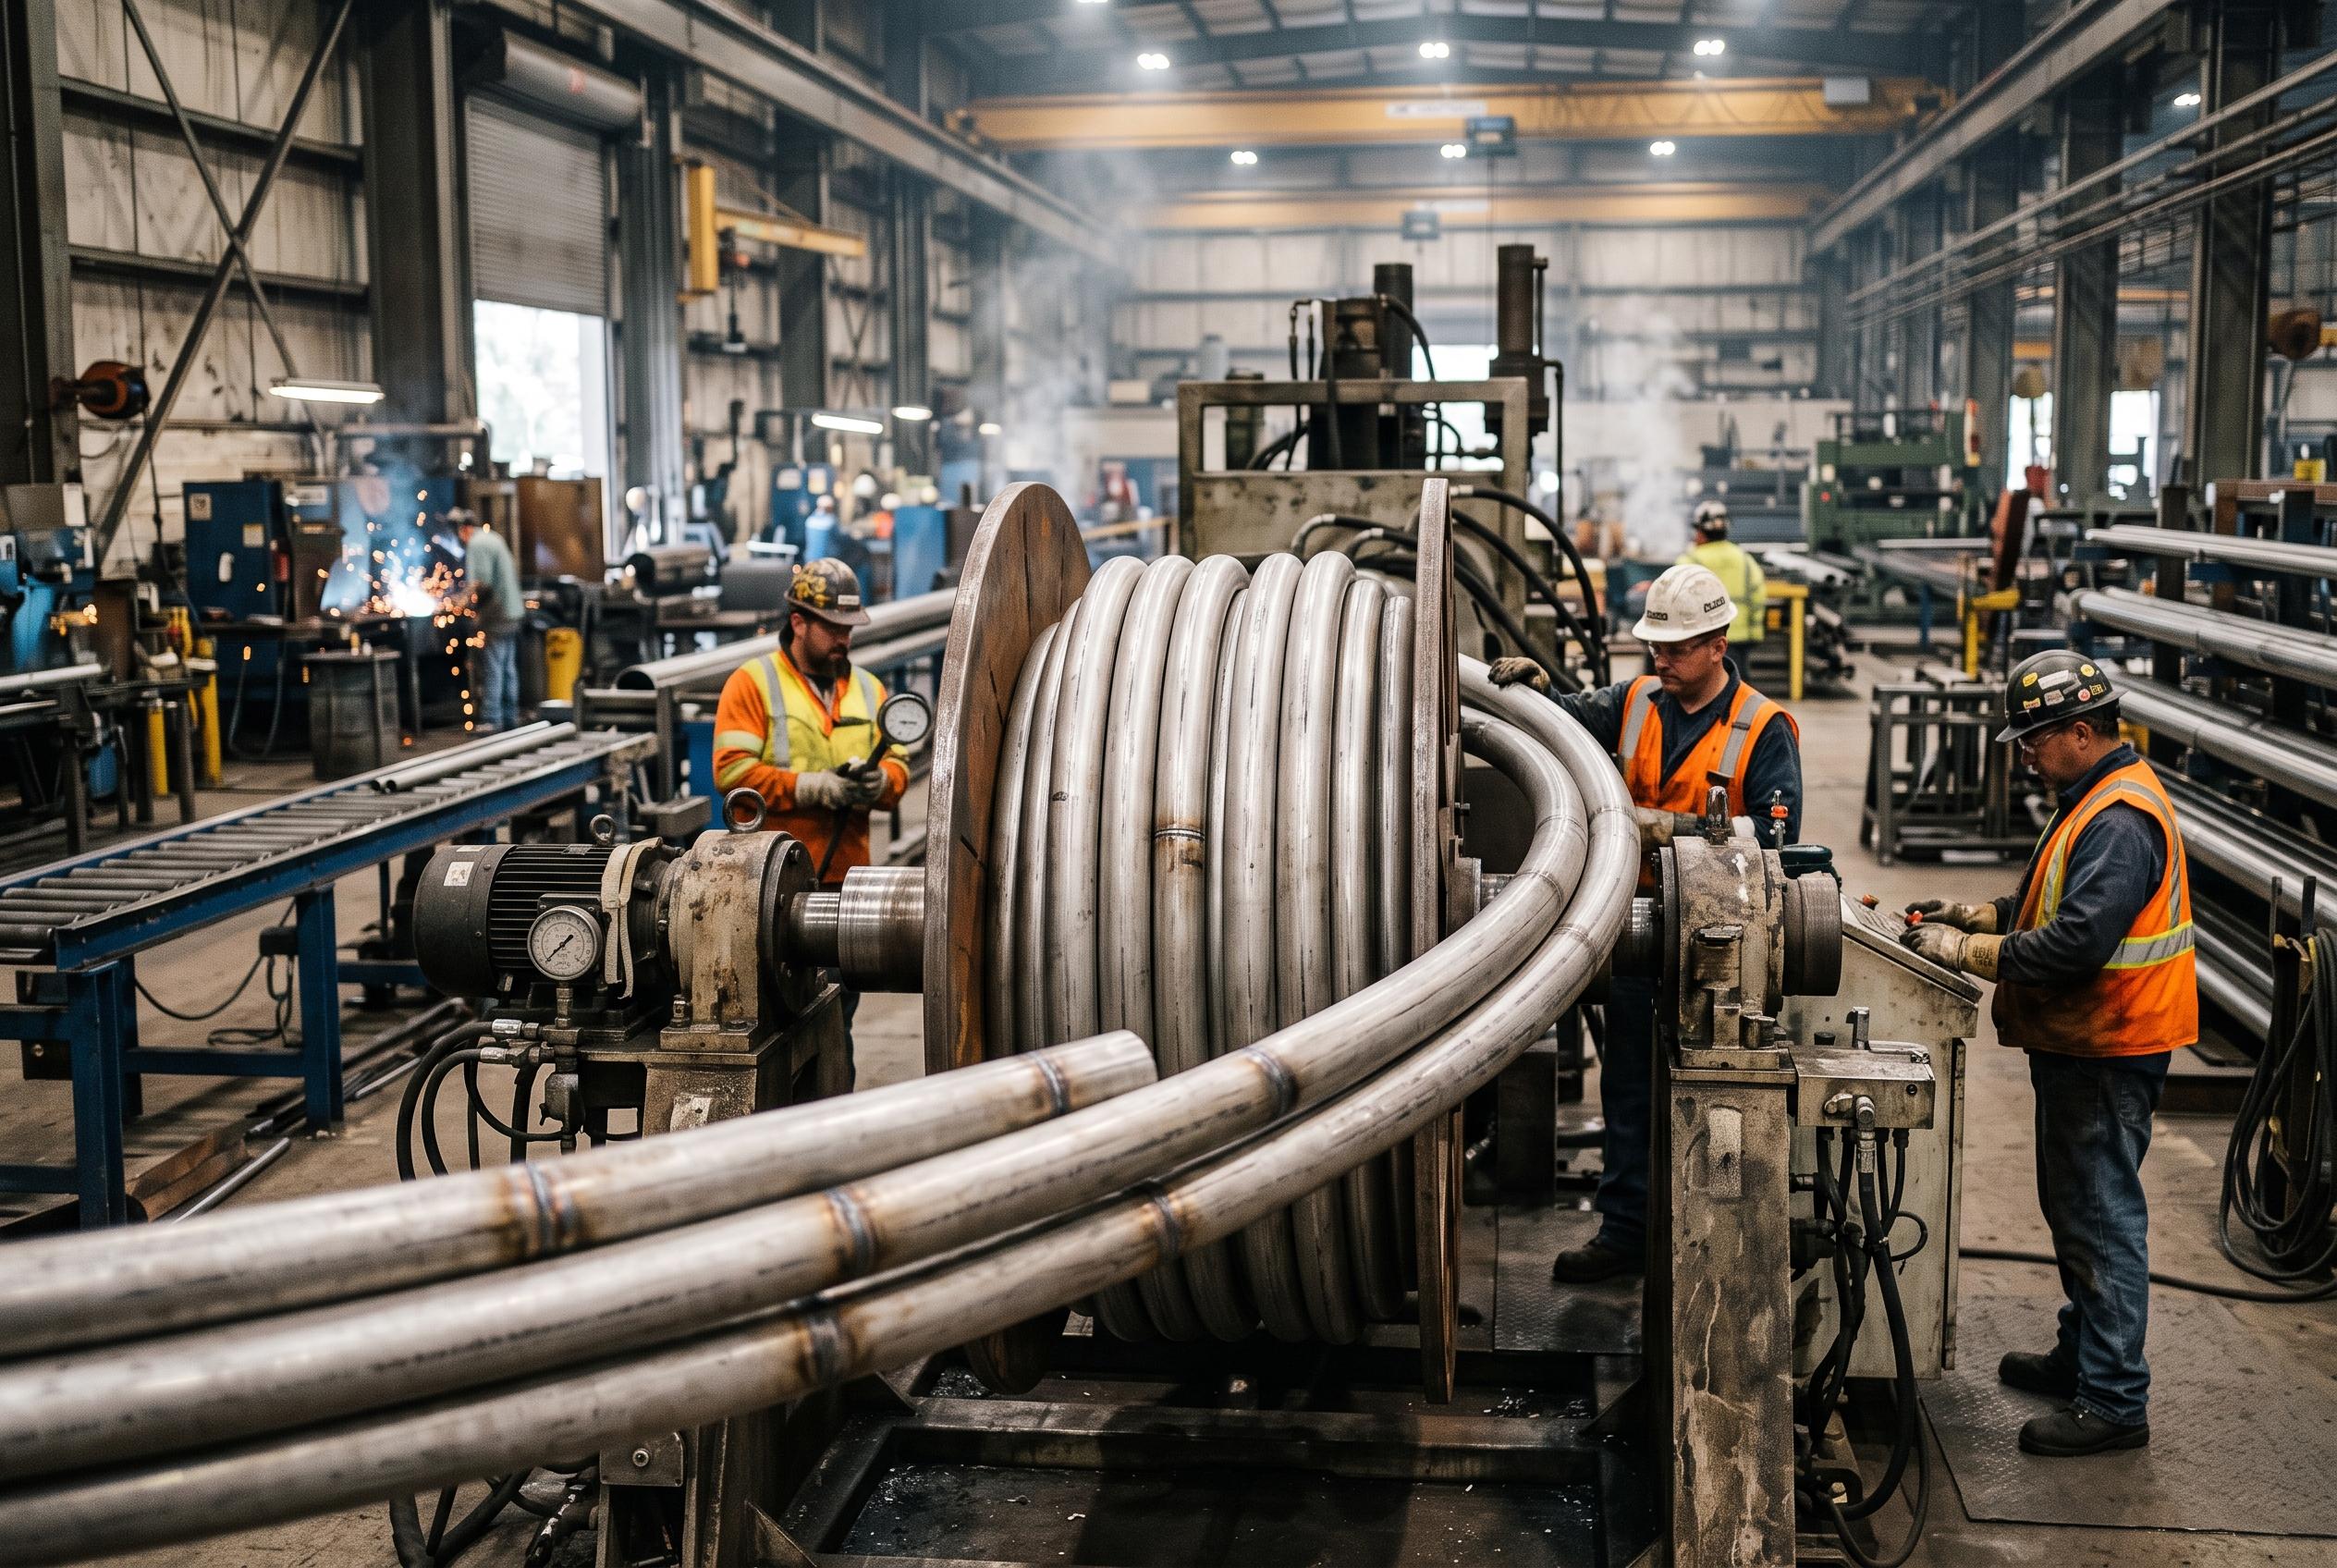

Venus Pipes & Tubes demonstrates robust growth with record quarterly revenue and moving into piping optimisation, signalling a strategic shift towards higher-margin, integrated solutions amid expanding order pipelines.
Venus Pipes & Tubes is beginning to look less like a niche industrial stock and more like a company trying to build a broader manufacturing platform. The shares were trading at ₹1,912.35, giving the business a market capitalisation of about ₹3,961 crore and a valuation of 38.24 times earnings, after the stock slipped 1.34% from the previous close of ₹1,938.30. What has caught investors’ attention is not just the price action, but a combination of record revenue, a stronger product mix and a new growth opportunity in pipe spooling.
According to the company’s June quarter results, Venus Pipes & Tubes posted its highest-ever quarterly revenue of ₹320.5 crore in the first quarter of FY27, up 15.96% from a year earlier and 6.07% from the previous quarter, according to ICICI Direct and the company’s regulatory filing. EBITDA rose 14.7% to ₹51.5 crore, while profit after tax increased 6.5% to ₹26.4 crore. The EBITDA margin held at 16.1%, suggesting the business was able to grow without sacrificing profitability. The revenue mix also showed how the company is evolving: seamles pipes accounted for 55% of sales, welded products 39% and other products 6%, according to industry summaries of the results.
The most interesting development is Venus Pipes’ move into pipe spooling, a higher-value business that could lift margins and deepen customer relationships. The company has secured a ₹185 crore letter of intent from a data-centre customer and plans to invest about ₹70 crore to build the facility, according to reports on its earnings update. In simple terms, pipe spools are pre-assembled piping units that are welded and tested before they reach the site, which can make them more attractive than selling standalone pipes and fittings. That shift could help Venus move further up the value chain, especially as data-centre construction continues to create demand for integrated industrial solutions.
The company is also being helped by a sizeable order pipeline. One summary placed the order book at ₹450 crore as of FY26, while another cited a figure of ₹600 crore, reflecting the strength of recent order inflows and different reporting cut-offs. Either way, the backlog has expanded sharply over the past three years and now gives the company more visibility on future revenue. Management is targeting about 20% revenue growth in FY27 and expects margins to rise towards 18% over the next couple of years as capacity utilisation improves and the share of value-added products increases.
Exports remain a softer spot, but they also point to room for recovery. Venus generated about 30% of revenue overseas in the quarter, yet more than 40% of the current order book is export-linked, according to company-linked summaries. That gap suggests international demand could strengthen as geopolitical disruptions ease. For now, the investment case rests on whether Venus can keep executing on several fronts at once: scaling its traditional pipe business, widening into fittings and spooling, and turning a strong order book into sustained earnings growth.
Disclaimer: This article is intended to inform and educate, not to recommend or endorse any financial product, investment or strategy. Please consider your own financial circumstances and seek professional advice where appropriate before making financial decisions.